GeTax · Chapter 6/11
Securities list in GeTax: bank accounts, shares, crypto and withholding tax
Key points
- All accounts and securities, in Switzerland and abroad, go in the securities list (« Etat des titres », schedule F), with their balance or value on 31 December and their income.
- Each line has a type: CPT (account), ACT (share), OBL, FDS (fund), CRY (crypto), RF or ERF (bank tax statement, simplified entry), etc.
- Income subject to withholding tax gives a refund of the 35% withheld, credited against cantonal tax. Foreign accounts go in the "not subject" column.
- Account maintenance and safe deposit fees are deductible; card fees, e-banking and withdrawal fees are not.
Preliminary questions
GeTax first asks whether you are a US citizen (dual nationality or « US Person » status) and whether you hold stakes in partnerships (« société en nom collectif », « commandite »). Answer for the whole household.
Detailed or simplified entry
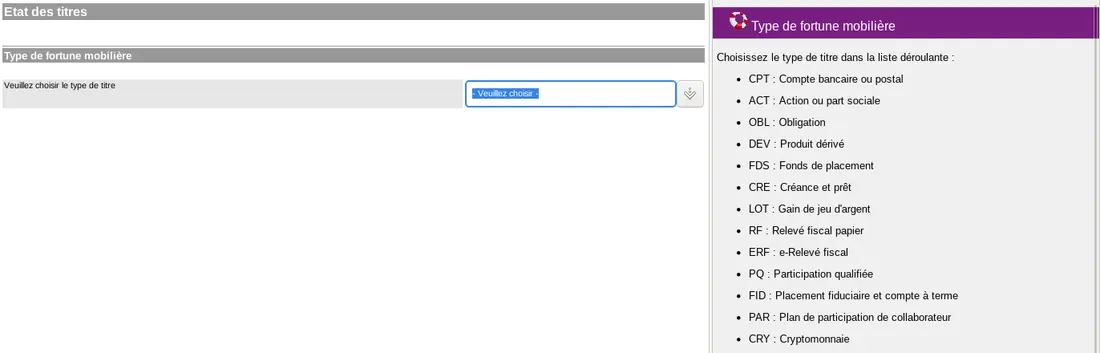
| Code | Type | When to use it |
|---|---|---|
| CPT | « Compte bancaire ou postal » (bank or postal account) | Private, savings and foreign accounts, crypto held in an account |
| ACT, OBL, FDS | Share, bond, investment fund | Securities held directly, detailed entry |
| DEV, CRE, FID | Derivative, receivable or loan, fiduciary deposit | Special cases |
| LOT | Gambling winnings | Taxable lottery winnings |
| RF | « Relevé fiscal papier » (paper bank tax statement) | Simplified entry: one line copies the bank statement's summary |
| ERF | « e-Relevé fiscal » (electronic tax statement) | Import of the bank's electronic file |
| PQ | Qualifying holding | At least 10% of a company's capital |
| PAR | Employee participation plan | Employer shares or options |
| CRY | Cryptocurrency | Bitcoin, Ether, etc. |
With a bank tax statement, simplified entry saves you copying every security: choose RF and copy the totals from the summary page, or ERF to import the e-statement. Imported lines appear under « Affichage des titres importés par e-relevé ».
Declaring a bank account
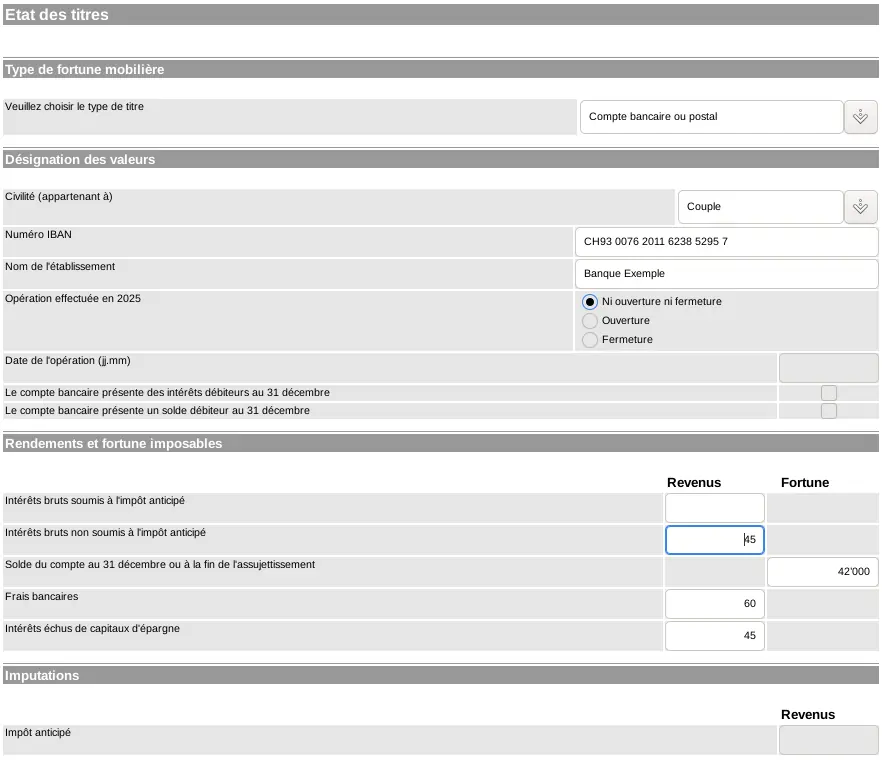
- Owner (« Civilité »): taxpayer A, B, couple or child(ren). Minor children's accounts are declared with the parents'.
- Transaction: account opened or closed during the year, with the date.
- Gross interest subject to withholding tax (« soumis à l'impôt anticipé »): Swiss accounts with 35% withheld. Interest of CHF 200 or less on an account in the year is normally exempt from withholding tax: put it under "not subject".
- Gross interest not subject (« non soumis »): foreign accounts, small Swiss interest.
- Balance on 31 December (or at the end of tax liability), converted into francs.
- Bank fees: account maintenance and safe deposit rental. Card fees, e-banking and withdrawal fees are not accepted.
Withholding tax and other credits
GeTax computes 35% of income subject to withholding tax and shows it in « Résumé des imputations » (summary of credits). The AFC credits it against cantonal and communal tax: it appears under « Imputations » on the tax bill. Two more columns concern foreign securities:
| Column | Meaning | Mandatory form |
|---|---|---|
| RSI | Additional withholding on US dividends and interest received through a Swiss bank | Form R-US 164 |
| IES | Credit for foreign withholding taxes under a double tax treaty | Form DA-1 (dividends, interest) or DA-3 |
Cryptocurrencies
Cryptocurrencies are treated as foreign currencies: they are part of your wealth at the 31 December tax rate published by the Swiss Federal Tax Administration ("Crypto-monnaies" list of official rates, on ictax.admin.ch). Multiply the rate by the number of units. For an individual managing private wealth, capital gains are not taxable and losses are not deductible; income (staking, interest) is declared as investment income.
Accounts and securities in foreign currency
Use the year's official exchange rates: annual average rates to convert income, 31 December rates for wealth. The AFC publishes them on ge.ch and the Confederation on ictax.admin.ch. GeTax includes a database of listed securities prices, updated during the year.
For qualifying holdings (10% of the capital or more), dividends from private wealth get a 30% reduction for cantonal tax. Declare them with type PQ.
Frequently asked questions
Do I have to declare a foreign bank account in Geneva?
Yes. All accounts, in Switzerland and abroad, go in the securities list with their 31 December balance in francs and their interest in the column « non soumis à l'impôt anticipé ».
How do I get the 35% withholding tax back?
By declaring the income in the column « soumis à l'impôt anticipé » of the securities list. GeTax computes the 35% and the AFC credits it against your cantonal and communal tax.
How do I declare bitcoin in GeTax?
With type CRY (or as an account), at the 31 December tax rate published by the Swiss Federal Tax Administration, multiplied by the number of units. Private capital gains are not taxable.
Are bank fees deductible?
Account maintenance and safe deposit fees, yes. Credit or debit card fees, e-banking and ATM withdrawal fees, no.
Rather hand it over?
NeoFidu prepares and files your Geneva tax return for you, including source tax and TOU cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from official publications of the Geneva cantonal tax administration (AFC) and the Swiss Federal Tax Administration. GeTax offers an English interface, but the return itself is French: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show GeTax 2025 with fictitious data. If in doubt, the official AFC instructions prevail.