GeTax · Chapter 4/11
Work expenses in GeTax: 3% flat rate or actual costs, cantonal and federal 2026
Key points
- Cantonal tax (ICC): a single 3% flat rate of net salary (code 31.50), between CHF 641 and CHF 1,817 in 2026, covers commuting, meals and other costs together.
- With actual costs, commuting is capped at CHF 536 (code 31.70) whatever the means of transport, and meals only count if the public transport journey exceeds two hours a day.
- Federal tax (IFD): the choice is made separately. The federal flat rate (3%, CHF 2,000 to 4,000 in GeTax 2025) comes on top of commuting (max. CHF 3,300) and meals.
- Married couple with two incomes: GeTax computes the CHF 1,054 deduction (cantonal, 2026) and the federal two-earner deduction itself.
The Geneva principle: one flat rate for everything
For each employed taxpayer, GeTax asks for two separate choices: « Frais forfaitaires » (flat rate) or « Frais effectifs » (actual costs) for IFD (federal), then for ICC (cantonal). In Geneva the cantonal flat rate is a single amount covering commuting, meals away from home and other costs (special clothing, tools, professional literature). That is the big difference from cantons with a flat rate per category.
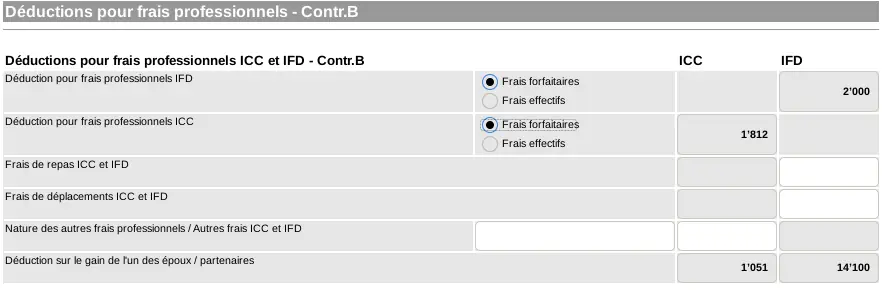
The cantonal flat rate: 3%, CHF 641 to 1,817
The flat rate is 3% of gross income minus AHV/AI/APG/unemployment and pension contributions (code 11.00 minus 31.10 and 31.12, before buy-ins). Example: gross salary CHF 104,000, contributions CHF 13,960, balance CHF 90,040 × 3% = CHF 2,701, reduced to the CHF 1,817 cap. From a net salary of about CHF 60,600, the cap is reached.
| Cantonal flat rate (code 31.50) | 2025 | 2026 |
|---|---|---|
| Rate | 3% | 3% |
| Minimum | CHF 640 | CHF 641 |
| Maximum | CHF 1,812 | CHF 1,817 |
Cantonal actual costs: when are they worth it?
| Cantonal actual costs | Code | Rule |
|---|---|---|
| Home-to-work commuting | 31.70 | max. CHF 536 in 2026, whatever the means of transport |
| Meals | 31.60 | only if the public transport journey exceeds 2 hours a day: CHF 15 a day, max. CHF 3,200 (half if box G is ticked) |
| Other costs (union fees, etc.) | 31.63 | with receipts |
With commuting capped at CHF 536, actual costs only beat the flat rate if you qualify for meals (long journey) or have large other costs. The AFC guide's example: a resident of Hermance with over two hours of travel a day reaches CHF 3,854 (commuting 534, meals 3,200, union fees 120) against a flat rate of 1,812. A resident of Carouge working in the city is better off with the flat rate.
You work outside the canton of Geneva
For an employer outside the canton, meals are accepted under federal rules (CHF 15 a day, max. CHF 3,200). If you stay near your workplace during the week, lunch and dinner are accepted up to CHF 6,400 and the room rent up to CHF 500 a month for cantonal tax (code 31.63, stating « Frais de logement »). Commuting remains capped at CHF 536 for cantonal tax.
Federal tax: flat rate and separate costs
| Federal tax (IFD) | Code | Amount (GeTax 2025) |
|---|---|---|
| Flat rate for other work expenses | 31.20 | 3%, min. CHF 2,000, max. CHF 4,000 |
| Commuting (public transport, or car if justified) | 31.71 | max. CHF 3,300; bicycle CHF 700; car CHF 0.70 per km |
| Meals | 31.60 | CHF 15 a day, max. CHF 3,200 |
| Two-earner couple | 31.90 | 50% of the lower income, max. CHF 14,100 |
For federal tax, the flat rate only covers "other costs": commuting and meals are entered on top, in the fields « Frais de repas ICC et IFD » and « Frais de déplacements ICC et IFD ». If you chose the cantonal flat rate, GeTax only uses them in the IFD column.
Home office
A home office is only deductible if a room is used exclusively for work and your employer provides no workplace. You then deduct the share of rent for that room, with a detailed list and a copy of the lease, provided it exceeds the flat rate. Working from the living room gives no specific deduction. On home-office days, neither meals nor commuting are deductible.
Two-earner couples
When both spouses or registered partners work, cantonal tax grants CHF 1,054 in 2026 (CHF 1,051 in 2025) on the lower income, under code 31.95. Federal tax grants 50% of the lower earned income, minimum CHF 8,600 (or the income if lower) and maximum CHF 14,100. GeTax fills in both fields itself on taxpayer B's screen.
Frequently asked questions
What is the flat-rate work expense deduction in Geneva for 2026?
3% of net salary (gross minus AHV and pension contributions), minimum CHF 641 and maximum CHF 1,817 for cantonal and communal tax. It covers commuting, meals and other costs.
Can I deduct my public transport pass on top of the flat rate?
Not for cantonal tax: the flat rate already covers commuting, and as actual costs commuting is limited to CHF 536. For federal tax, yes: commuting (max. CHF 3,300 in 2025) is added to the federal flat rate.
Are meals deductible in Geneva?
For cantonal tax, only as actual costs and if the public transport journey exceeds two hours a day, or if your employer is outside the canton: CHF 15 a day, max. CHF 3,200. For federal tax, they are deducted on top of the flat rate.
Can I use the flat rate for cantonal tax and actual costs for federal tax?
Yes. GeTax offers the choice separately for federal and cantonal tax, for each taxpayer.
Rather hand it over?
NeoFidu prepares and files your Geneva tax return for you, including source tax and TOU cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from official publications of the Geneva cantonal tax administration (AFC) and the Swiss Federal Tax Administration. GeTax offers an English interface, but the return itself is French: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show GeTax 2025 with fictitious data. If in doubt, the official AFC instructions prevail.