GeTax · Chapter 5/11
Pillar 3a, pension fund buy-ins and life insurance in GeTax: 2026 deductions
Key points
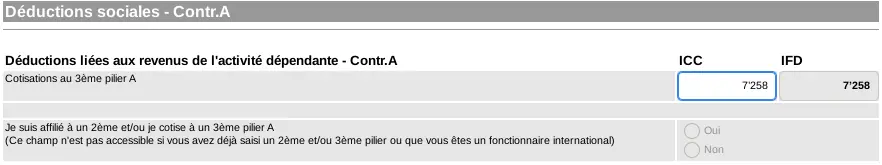
- Pillar 3a (code 31.40 for taxpayer A, 41.40 for B): up to CHF 7,258 with a pension fund, or 20% of earned income up to CHF 36,288 without a 2nd pillar. Amounts unchanged in 2026.
- New in 2026: 3a contributions not paid in 2025 can be made up in 2026 and are deductible for the first time in the 2026 return.
- Pension fund buy-ins: box 10.2 of the salary certificate or the fund's statement, code 31.30. A lump-sum withdrawal within three years cancels the deduction.
- Life insurance and savings interest (pillar 3b): 2026 cantonal cap of CHF 3,528 for a couple and CHF 2,352 for a single person, plus CHF 962 per dependant.
Pillar 3a
| Situation | Maximum deduction 2025 and 2026 |
|---|---|
| Member of a pension fund (2nd pillar) | CHF 7,258 |
| No 2nd pillar (self-employed, for example) | 20% of net earned income, max. CHF 36,288 |
Enter the payments made during the year, separately for each taxpayer, and always attach the bank or insurer's certificate. Payments above the cap are not accepted and must be refunded by the provider. Contributions to a pillar 3b (free life insurance) do not go here but under code 52.11 (see below).
New in 2026: pillar 3a catch-up payments
Since 2026, you can fill a 3a contribution gap from previous years, starting with 2025. The catch-up payment is deductible from taxable income for the first time in the 2026 return, filed in 2027. Conditions set by the Confederation and summarised by the AFC:
- AHV-liable income in Switzerland in the year being made up and in the year of the catch-up payment;
- the full ordinary contribution for the catch-up year must be paid first;
- for each missing year, the catch-up is limited to the "small contribution" (CHF 7,258 in 2026), over ten years at most.
| Example (AHV income in 2025 and 2026) | Paid for 2025 | Catch-up in 2026 | 2026 deduction |
|---|---|---|---|
| A: full contributions, no catch-up | CHF 7,258 | 0 | CHF 7,258 |
| B: nothing paid in 2025 | 0 | CHF 7,258 | CHF 14,516 |
| C: partial payment in 2025 | CHF 4,500 | CHF 2,758 | CHF 10,016 |
2nd pillar buy-ins
A pension fund buy-in often appears in box 10.2 of the salary certificate: enter it in « Rachat(s) de la prévoyance professionnelle » (code 31.30) on the employment screen. If you paid the fund directly, use its statement. Either way, attach the fund's document.
Life insurance and pillar 3b
Life insurance premiums (code 52.11) and savings interest (code 56.30, carried over from the securities list) share one cap, computed under code 52.15 for cantonal tax.
| Cantonal cap 2026 | Amount |
|---|---|
| Married couple | CHF 3,528 |
| Single person | CHF 2,352 |
| Extra per dependant | CHF 962 |
| Person or couple with no 2nd pillar or pillar 3a | caps doubled |
| Only one spouse in a pension scheme | couple cap × 1.5 |
For federal tax, the caps are set by the Confederation; GeTax applies them and shows the subtotal under code 52.10.
Frequently asked questions
How much pillar 3a can I deduct in 2026?
CHF 7,258 if you are in a pension fund, otherwise 20% of net earned income up to CHF 36,288. The amounts are unchanged from 2025.
Where do I enter pillar 3a in GeTax?
« Revenu », « Déductions sociales », field « Cotisations au 3ème pilier A » (code 31.40 for taxpayer A, 41.40 for B). Always attach the certificate.
Is a pillar 3a catch-up deductible in the 2026 return?
Yes. A catch-up made in 2026 for a 2025 gap is deductible for the first time in the 2026 return, on top of the ordinary 2026 contribution, under the federal conditions.
My pension fund buy-in is not on my salary certificate. What now?
Enter it anyway under code 31.30 with your pension fund's statement as supporting document.
Rather hand it over?
NeoFidu prepares and files your Geneva tax return for you, including source tax and TOU cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from official publications of the Geneva cantonal tax administration (AFC) and the Swiss Federal Tax Administration. GeTax offers an English interface, but the return itself is French: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show GeTax 2025 with fictitious data. If in doubt, the official AFC instructions prevail.