GeTax · Chapter 8/11
Property in GeTax: tax value, imputed rental value, upkeep costs 2026
Key points
- An owner-occupier declares the tax value of the property (« Capital selon estimation ») and its gross imputed rental value (« valeur locative brute ») in schedule D. GeTax applies a 4% reduction per year of occupation, up to 40%.
- 2026 cantonal upkeep flat rate: 15% of the reduced rental value if the building is 10 years old or less, 25% beyond. For federal tax: 10% or 20% of the gross rental value.
- The effort cap limits the rental value to 20% of gross income, if mortgage interest does not exceed it.
- Imputed rental value is only abolished from 1 January 2029: it remains in the 2026 return. Tenants cannot deduct their rent.
Which type of property?
| GeTax section | Code | Examples |
|---|---|---|
| « Immeubles occupés par le propriétaire » (owner-occupied) | 15.10 | Your home, second home in Switzerland or abroad |
| « Immeubles locatifs ou loués » (rented out) | 15.20 | Flat let to a third party, undeveloped land |
| « Immeubles commerciaux, industriels » | 15.30 | Business premises |
| « Immeubles épargne logement PPE » | 15.40 | Subsidised owner-occupied flats |
| « Immeubles HLM » | 15.50 | Subsidised rental buildings |
Property outside the canton or abroad must be declared too: it is not taxed in Geneva but counts for the tax rate. For property abroad, convert the value at the tax year's exchange rate.
Basic data and wealth
Enter the municipality, the plot number (on the AFC property notice), the address, the year of construction, the date you moved in, whether you already owned it on 31 December of the previous year and whether it is your main residence. For a couple, split ownership between A and B.
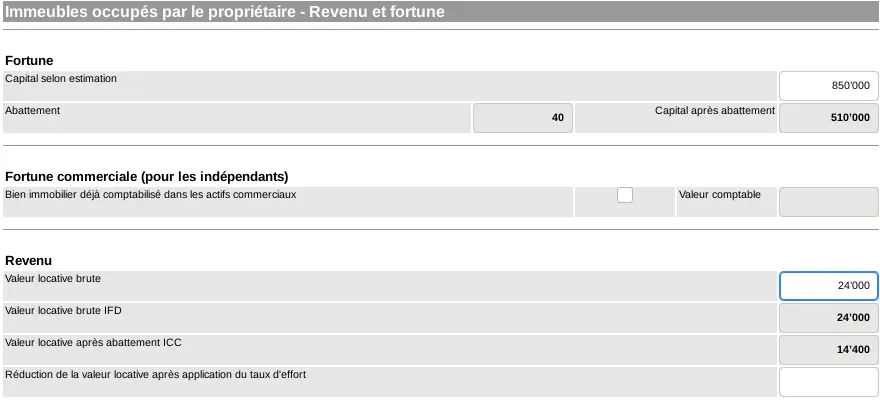
- « Capital selon estimation » (code 15.10): the tax value notified by the AFC. After the 12% increase of 2025 (LEFI law) for houses and condominiums, it is indexed every year from 2026; the figure is on the letter received before 31 March.
- « Abattement » (reduction): 4% per year of continuous occupation, up to 40% after ten years, computed by GeTax from the occupation date. It lowers taxable wealth and the cantonal rental value.
- « Valeur locative brute » (gross rental value): on the property notice. The field is mandatory (enter 0 in the rare cases where it is nil).
Upkeep costs: flat rate or actual
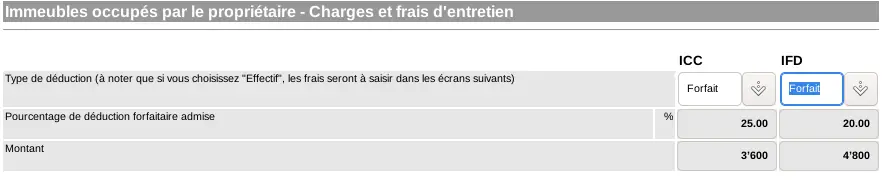
| Upkeep flat rate (code 58.10) | Cantonal, on reduced rental value | Federal, on gross rental value |
|---|---|---|
| Building 10 years old or less at the start of the year | 15% | 10% |
| Building over 10 years old | 25% | 20% |
Each year and for each property, you can choose between the flat rate and actual costs. Choosing « Effectif » opens two screens: « Frais et taxes effectifs » and « Frais d'entretien effectifs ». Deductible items include repairs and renovations that do not increase the property's value, payments to a condominium renovation fund, building insurance premiums, third-party management fees and energy-saving investments (carried forward over the next two years if they exceed the year's income). Keep the invoices; do not send them.
Complementary property tax
Geneva levies an annual complementary property tax (« impôt immobilier complémentaire », IIC) on the tax value, without deducting debts: 1‰ in general, 0.2‰ for an individual's main residence. It counts as a deductible upkeep cost when you claim actual costs. A 20-year exemption is possible for a high or very high energy performance building (OCEN certificate).
Tenants
Rent for your home is not deductible in Geneva, and GeTax no longer asks for it since the 2025 version. Only housing allowances from the OCLPF are declared (code 16.35), plus any subletting income.
What about abolishing imputed rental value?
Approved in a federal vote, the reform takes effect on 1 January 2029 (Federal Council decision of 1 April 2026). Until then, imputed rental value and the deductions for upkeep and mortgage interest continue to apply as today, including in the 2026 return.
Frequently asked questions
What is the upkeep flat rate in Geneva in 2026?
For cantonal tax, 15% of the reduced rental value if the building is 10 years old or less at the start of the year, 25% beyond. For federal tax, 10% or 20% of the gross rental value.
What is Geneva's 4% reduction?
For an owner-occupied home, the tax value and the cantonal rental value fall by 4% per year of continuous occupation, up to 40% after ten years. GeTax computes it from the occupation date.
Where do I find my property's tax value and rental value?
On the property notice the AFC sends to owners. For houses and condominiums, the tax value is indexed every year since 2026 and notified before 31 March.
Do I have to declare a flat abroad?
Yes. It is not taxed in Geneva but counts for the tax rate. Declare its value and rental value in francs at the tax year's exchange rate.
Rather hand it over?
NeoFidu prepares and files your Geneva tax return for you, including source tax and TOU cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from official publications of the Geneva cantonal tax administration (AFC) and the Swiss Federal Tax Administration. GeTax offers an English interface, but the return itself is French: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show GeTax 2025 with fictitious data. If in doubt, the official AFC instructions prevail.