VSTax · Chapter 8/11
Property in VSTax: imputed rent, chalets, furnished lets and upkeep costs
Key points
- Each property is described in schedule 2 (« Immeubles »): type, municipality, year built, imputed rent or rents, upkeep costs. Net income goes to code 1110 and the tax value to codes 2920 to 2923.
- Imputed rental value (« valeur locative ») is taxable on any home you keep for your own use, including a second home or holiday chalet, however little you actually use it.
- Upkeep: 10% flat rate of imputed rent or rents if the building is 10 years old or less, 20% if older, or actual costs. You choose each year and for each property.
- Furnished lets (including Airbnb or Booking.com): 20% flat deduction on rents. The tax value is 100% of the cadastral value (« taxe cadastrale »).
Schedule 2 « Etat et rendements des immeubles »
The schedule takes four properties per sheet, to be numbered. For each: canton or country, municipality, street or locality, type of property (flat, house, villa, chalet, « mayen » mountain hut, condominium unit, parking space), year built, purchase or sale date if in 2026, number of rooms or floor area, and period of use. The bottom of the column works out gross income, subtracts upkeep and gives net income, carried over to code 1110 (Valais), 1120 (other canton) or 1130 (abroad).
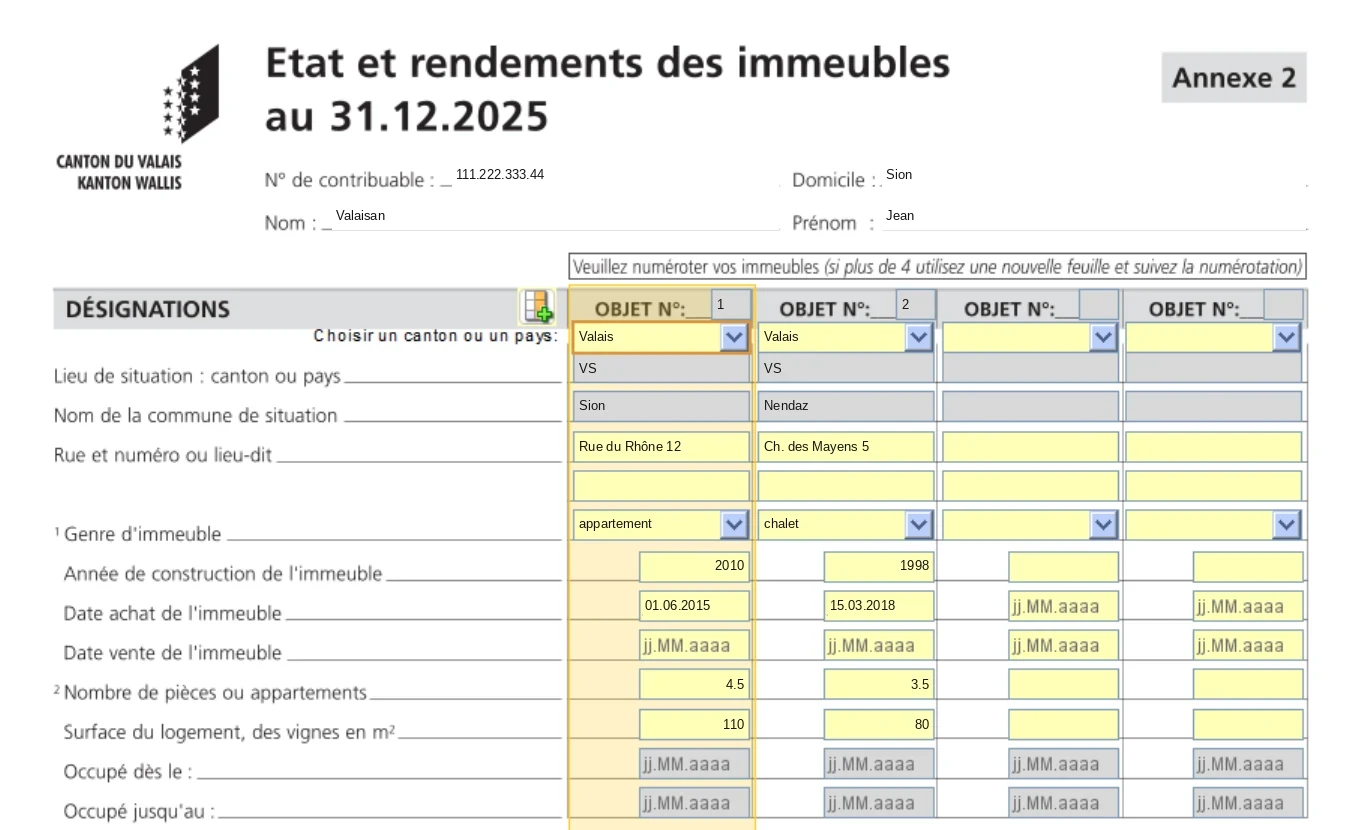
Imputed rental value and second homes
Imputed rental value is the rent you would pay for a similar home. It is taxable on the home you live in, and also on a holiday home, chalet or mayen you keep for your own use: how long you actually use it does not matter. Only a home that cannot be lived in or let has no imputed rent. The amount appears in the data carried over from last year or in your latest assessment notice; copy it as it is.
Rents, furnished lets and Airbnb
| Income | Line in schedule 2 | Treatment |
|---|---|---|
| Unfurnished let | « Loyers des immeubles loués non-meublés » | Rents received, including service charges billed above actual costs |
| Furnished let, holiday let, Airbnb, Booking.com | « Loyers des immeubles loués meublés » | Flat 20% deduction (excluding heating, electricity and water) |
| Premises let for business use | « Loyers des immeubles loués à des fins commerciales » | Actual costs only |
| Farm lease, building right, leased vineyards | « Fermages, droits de superficie » | Leased vineyards: CHF 0.25 per m² for the owner |
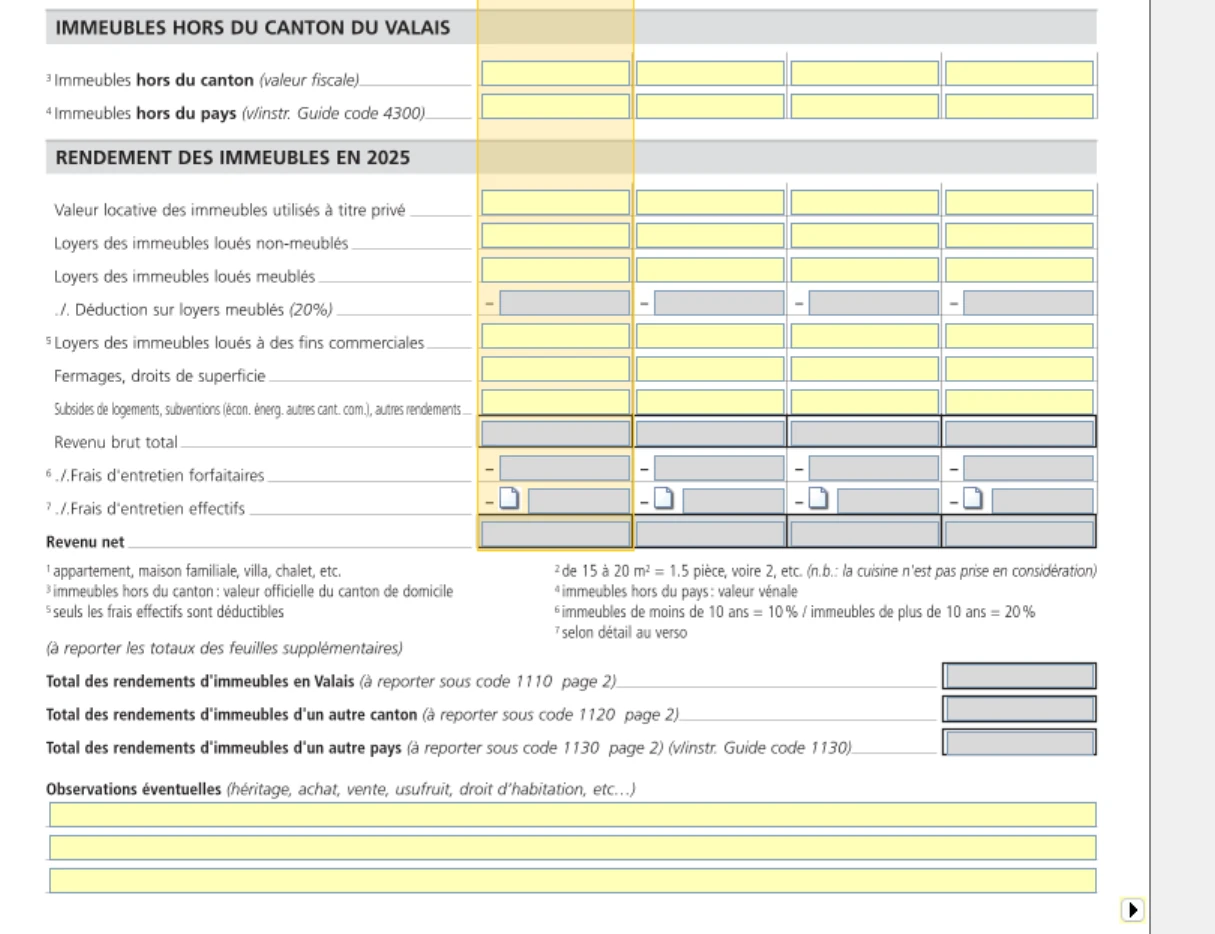
The 20% deduction on furnished lets covers, among other things, cleaning, advertising, platform and agency commissions, visitor and tourist taxes, internet and TV, and insurance and depreciation of furniture. If your letting reaches the scale of a self-employed business, you must attach a statement of income and expenses. Otherwise, the income is declared under code 1110 as above.
Upkeep: flat rate or actual costs
| Building | Flat rate (cantonal and federal tax) |
|---|---|
| 10 years old or less | 10% of imputed rent or gross rents |
| Over 10 years old | 20% of imputed rent or gross rents |
| Undeveloped land, building right, business use | No flat rate, actual costs only |
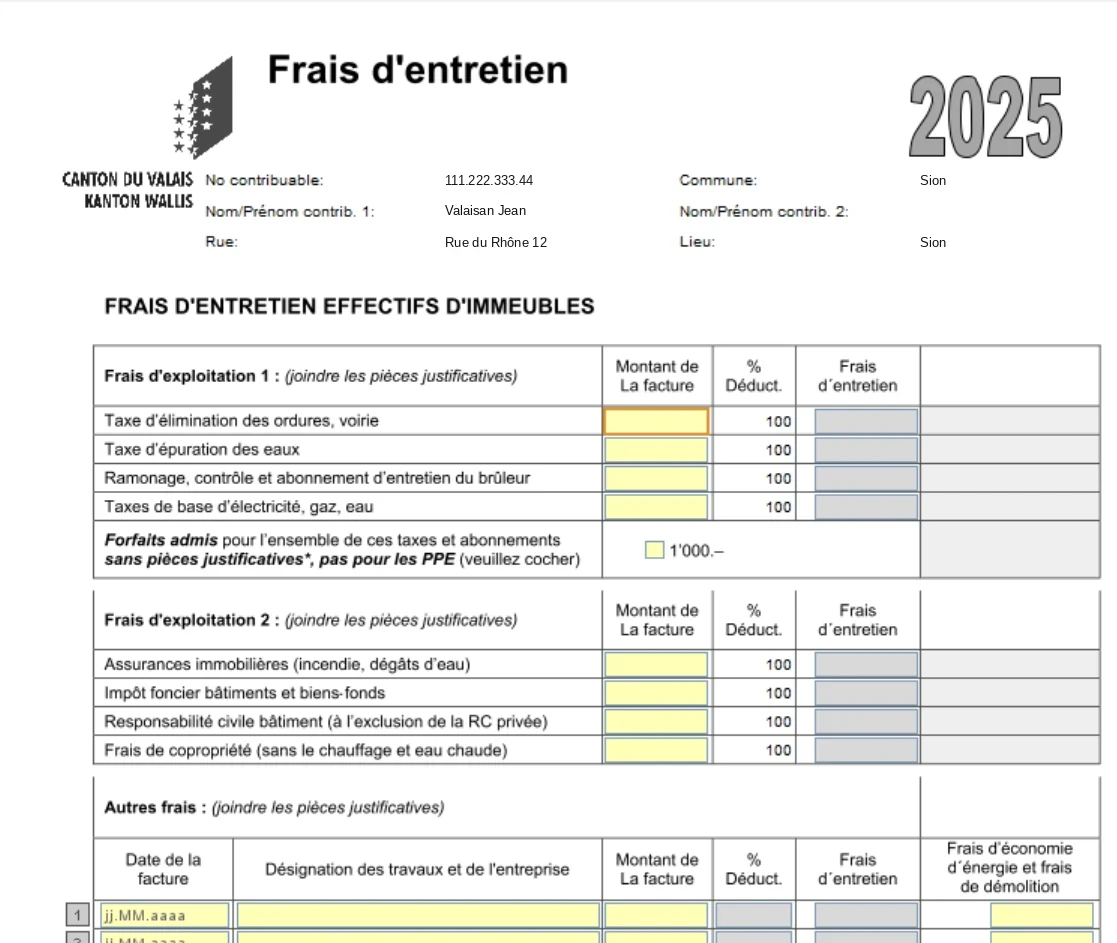
You choose each year and for each property between the flat rate and actual costs, detailed in the « Frais d'entretien » (upkeep costs) form. A building with several flats counts as one property, but each condominium unit is a separate one. For invoices, use either the invoice date or the payment date, but the same rule for all of them.
- Deductible: repairs and renovations that do not add value (painting, replacing a boiler, kitchen, windows, roof work), payments into the condominium renovation fund, building insurance, management fees paid to third parties, basic utility charges.
- Flat rate for basic charges: CHF 1,000, covering basic water, sewage, electricity and waste charges, only for the main home you occupy. Not allowed for a condominium unit, second home, mayen or let property.
- Energy saving: insulation, heat pump, district heating connection, photovoltaic and solar thermal panels (deductible immediately, directive 4.10). If these costs exceed income, the balance carries over to the next two tax years, as do demolition costs before rebuilding.
- Not deductible: purchase or sale costs (notary, land registry, mortgage note), one-off connection fees, heating energy and hot water, work that adds value to the property.
Tax value of the property (codes 2920 to 2923)
The tax value of a Valais property is 100% of the cadastral value (farmland is taxed at 15%). It is declared on page 4, separating buildings (« bâtiments ») and land (« biens-fonds »), in your home municipality (2920, 2921) or in other municipalities (2922, 2923). Mortgages go in the debts list.
| Property outside Valais | Value to give (for the rate) |
|---|---|
| In another canton | Official tax value, code 4200 |
| Abroad, country with a cadastral value | Cadastral value x 1.5, converted to francs, code 4300 |
| Abroad, no cadastral value | Purchase price converted to francs, code 4300 |
| Imputed rent of a property abroad | 3% of the tax value, code 1130 |
Frequently asked questions
Do I pay imputed rent on a chalet I rarely use?
Yes. In Valais, the imputed rent of a holiday home is taxable as soon as you keep it for your own use, however little you actually stay there. Only a home that cannot be used or let is exempt.
What is the upkeep flat rate for property in Valais?
10% of imputed rent or rents if the building is 10 years old or less, 20% if older. You can choose actual costs instead, each year and for each property.
How do I declare Airbnb income in Valais?
In schedule 2, on the line for furnished lets. A flat 20% deduction covers commissions, cleaning, visitor taxes and furniture depreciation, among other things.
What is the CHF 1,000 flat rate in Valais?
A flat rate for basic utility charges (water, sewage, electricity, waste), only for the main home occupied by the owner. It is not allowed for condominium units, second homes or let property.
Rather hand it over?
NeoFidu prepares and files your Valais tax return for you, including holiday homes and source tax cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from official publications of the Valais cantonal tax service (SCC) and the Swiss Federal Tax Administration. VSTax is only available in French and German: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show VSTax 2025 with fictitious data. If in doubt, the official SCC guide prevails.