VSTax · Chapter 3/11
Salary, pensions and side income in VSTax: schedule 5, schedule 1 and codes 310 to 721
Key points
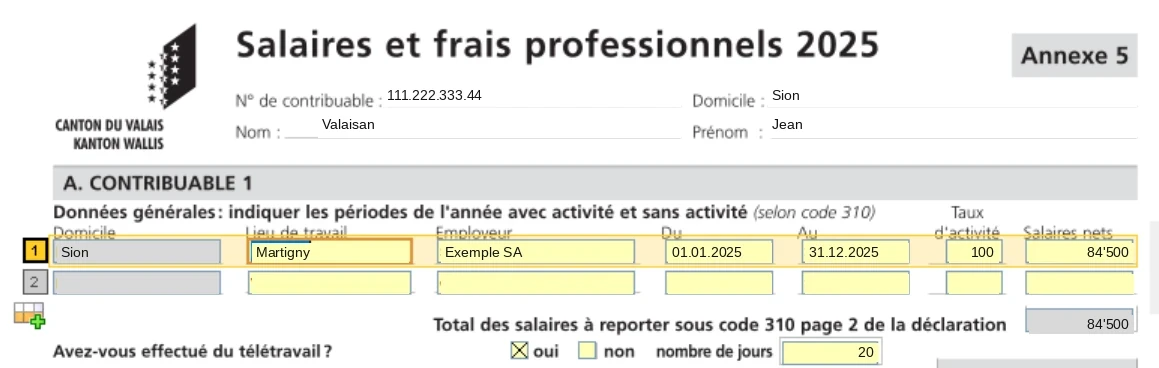
- In Valais you declare your net salary: gross salary minus AHV/IV/EO/ALV/NBU and pension fund contributions, i.e. box 11 of the salary certificate. It goes in schedule 5, then appears under code 310 (310a for taxpayer 2).
- Income without a salary certificate (unemployment benefits, benefits in kind) goes under code 320.
- Side income: declare the net amount, then a flat 20% is deducted, at least CHF 800 and at most CHF 2,400 (codes 410 and 420).
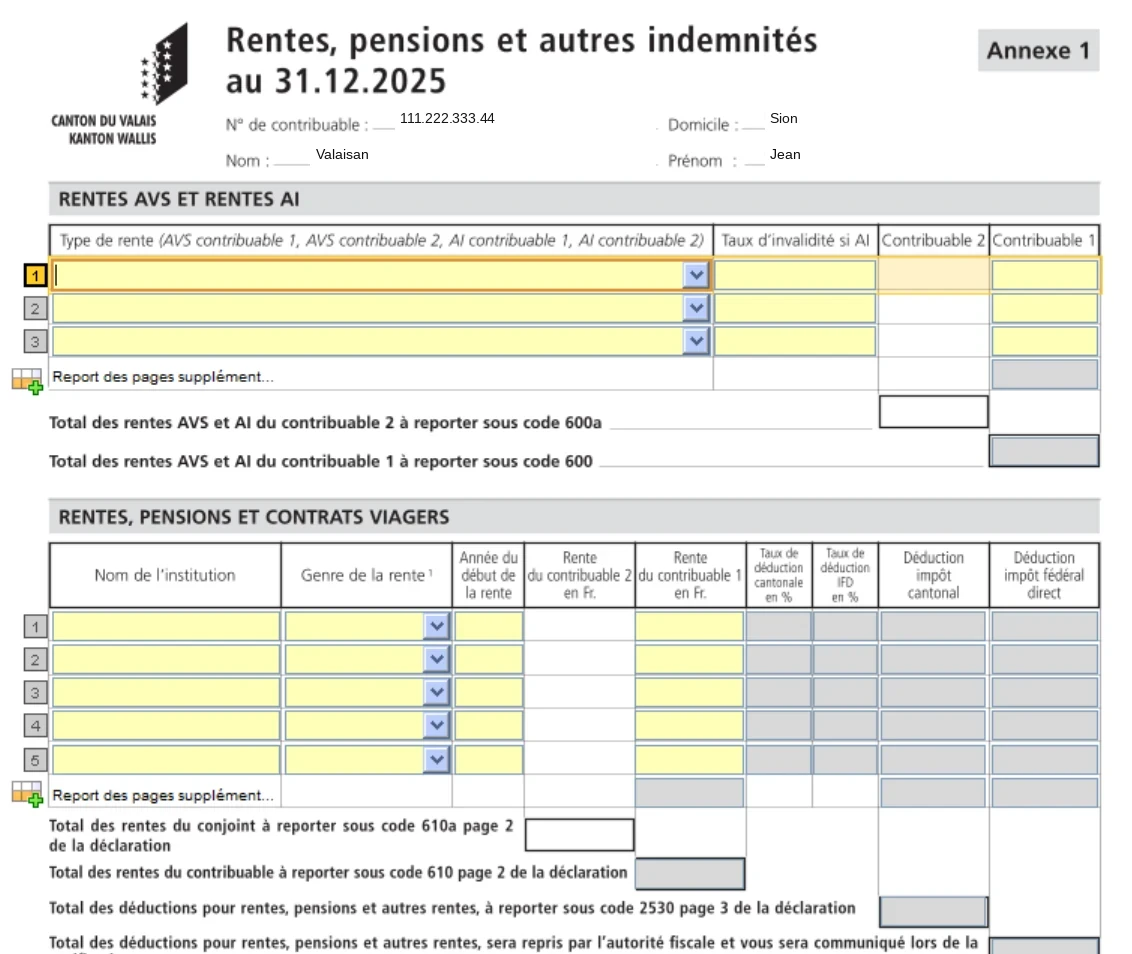
- AHV and disability pensions go under code 600, pension fund pensions and life annuities under code 610, via schedule 1.
Salary in schedule 5 « Salaires et frais professionnels »
The top of schedule 5 lists your work periods for the year: home, place of work, employer, from, to, work rate and net salary (« Salaires nets »). Add one line per employer and per period, including periods without work (unemployment, unpaid leave). The total is carried over automatically to code 310 on page 2 of the return. Taxpayer 2 has their own part B, carried over to code 310a.
| Salary certificate | Where it goes in VSTax |
|---|---|
| Box 11, net salary | Schedule 5, « Salaires nets » column (code 310) |
| Box 1: family allowances paid by the employer | Included in the net salary under code 310 |
| Box 2.2: private share of a company car | Included in the net salary; also answer « oui » to the company car question |
| Box 10.2: pension fund buy-in | Page 3, code 2100 (see Pension savings) |
| Boxes 13.1 and 13.2: expense allowances | Do not add them, but they limit your deductible expenses |
| Box G ticked (canteen, subsidised meals) | Meals at CHF 7.50 per day in expenses (see Work expenses) |
Income without a salary certificate (code 320)
Code 320 takes employment income that is not on a salary certificate: unemployment benefits, benefits in kind, private share of overheads, family or birth allowances paid directly by the fund, research grants. A salary must be declared even if the employer gave you no certificate.
Side income (codes 410 and 420)
A small income alongside your main job (teaching, refereeing, one-off work) goes in the « Détail gains accessoires » (side income details) form. State what it is and separate employed work (code 420, net of social contributions) from self-employed work (code 410, gross amount, then AHV contributions under code 411). VSTax then deducts a flat 20%, at least CHF 800 and at most CHF 2,400. If the gross amount is below CHF 800, only that amount can be deducted. Higher costs can be claimed with receipts.
Pensions and annuities (schedule 1)
| Income | Code | Taxed at |
|---|---|---|
| AHV and disability (AI) pensions | 600 | 100% |
| Pension fund (2nd pillar) pensions starting from 2002 | 610 | 100% |
| Pillar 3a annuities | 610 | 100% |
| Pension fund pensions starting before 2002 | 610, deduction 2530 | 60%, 80% or 90% depending on date and your share of funding |
| Private life annuities | 610 | income portion only |
| Loss of earnings, military insurance, sickness, accident or disability daily allowances | 720 | 100%, if not already on the salary certificate |
| Other benefits | 721 | specify |
Not taxable and not declared: AHV/disability supplementary benefits, helplessness allowances, social assistance and bridging benefits for older unemployed people. For each pension, give the institution, type of pension and start year: this avoids follow-up questions. If you still pay AHV contributions on a pension, you can deduct them under code 2000.
Maintenance payments and other income
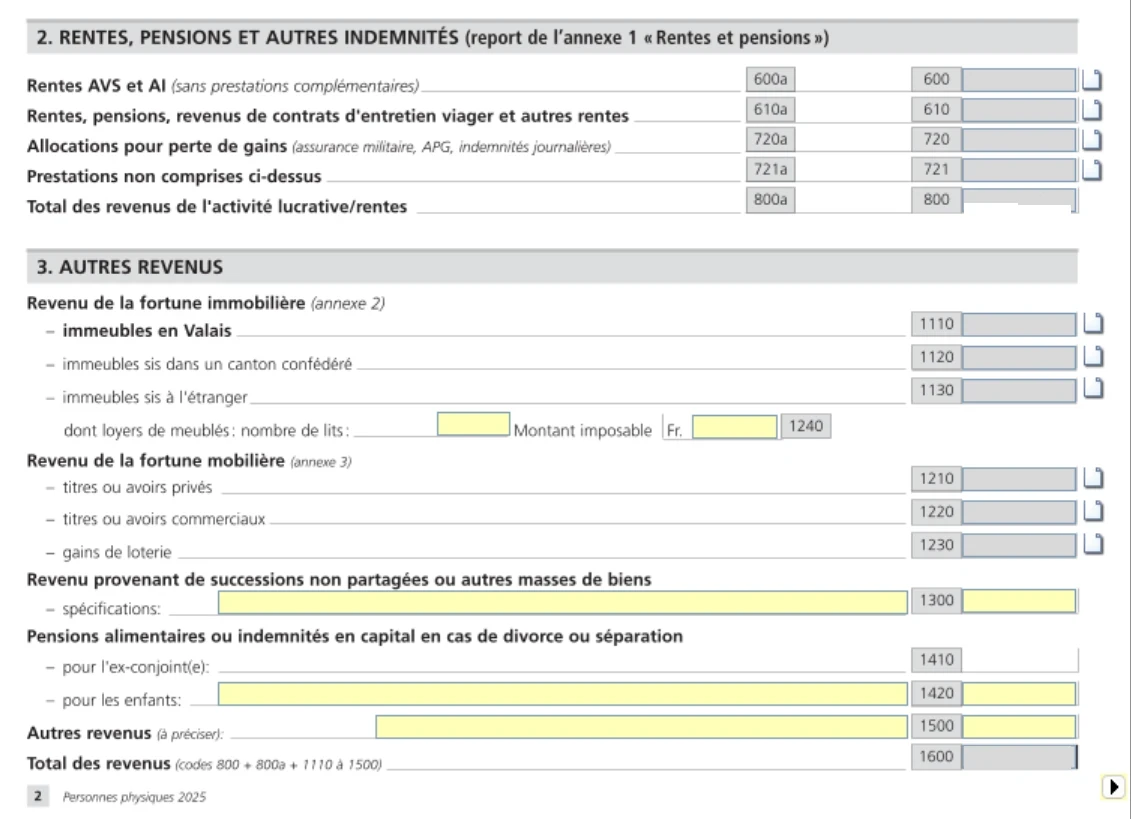
- Maintenance received from a former spouse: code 1410. Contributions received for minor children: code 1420. Maintenance for an adult child is neither taxable nor deductible.
- Maintenance paid as a lump sum is not taxable for the recipient (nor deductible for the payer).
- Income from an undivided estate: code 1300, with a detailed statement, based on the split provided by the estate administrator.
- Any other income not covered elsewhere (taxable study grant, occasional rental of equipment): code 1500.
Frequently asked questions
Do I enter gross or net salary in VSTax?
Net salary, i.e. box 11 of the salary certificate: gross salary minus AHV/IV/EO/ALV/NBU contributions and ordinary pension fund contributions. It is entered in schedule 5 and appears under code 310.
Where do I declare unemployment benefits in Valais?
Under code 320, employment income without a salary certificate, unless the unemployment fund gave you a salary-certificate-style statement, which you then enter like an employer in schedule 5.
What flat-rate deduction applies to side income in Valais?
20% of net side income, at least CHF 800 and at most CHF 2,400 a year. If the income is below CHF 800, the deduction is limited to that amount. Directors' attendance fees do not qualify.
Are AHV supplementary benefits taxable?
No. AHV/disability supplementary benefits, helplessness allowances and social assistance are not taxable and are not declared.
Rather hand it over?
NeoFidu prepares and files your Valais tax return for you, including holiday homes and source tax cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from official publications of the Valais cantonal tax service (SCC) and the Swiss Federal Tax Administration. VSTax is only available in French and German: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show VSTax 2025 with fictitious data. If in doubt, the official SCC guide prevails.