VSTax · Chapter 5/11
Pillar 3a, pension fund buy-ins and lump sums in VSTax: 2026 deductions
Key points
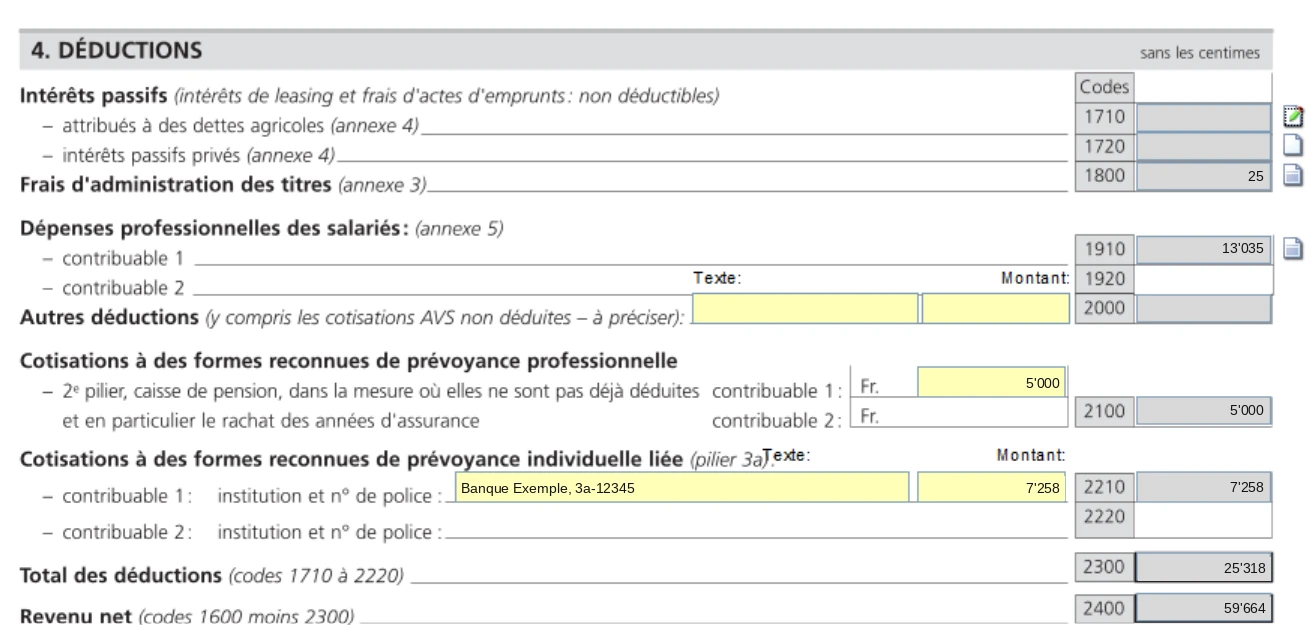
- Pillar 3a: code 2210 for taxpayer 1, 2220 for taxpayer 2, on page 3. Up to CHF 7,258 with a pension fund, or 20% of earned income up to CHF 36,288 without one. Amounts unchanged in 2026.
- New in 2026: 3a contributions not paid in 2025 can be made up in 2026 and are deductible for the first time in the 2026 return.
- Pension fund buy-ins: code 2100, with the fund's certificate. A lump-sum withdrawal within the next three years cancels the deduction.
- A pension lump sum received in 2026 (2nd or 3rd pillar) goes in section 7 on page 3; it is taxed separately at a reduced rate.
Pillar 3a (codes 2210 and 2220)
| Situation | Maximum deduction 2025 and 2026 |
|---|---|
| Member of a pension fund (2nd pillar) | CHF 7,258 |
| No 2nd pillar (self-employed, for example) | 20% of net earned income, max. CHF 36,288 |
For each taxpayer, enter the payments made by 31 December 2026, with the institution's name and policy number, and attach the bank's or insurer's certificate. The deduction requires earned income; a temporary break (unemployment, illness, military service) does not cancel it. In the year you retire, the payment must be made before your retirement date. The cap depends on your answer to the pension fund question in the personal data.
New in 2026: pillar 3a catch-up payments
From 2026, you can fill a 3a contribution gap from earlier years, starting with 2025 at the earliest. The catch-up payment is deductible for the first time in the 2026 return, filed in 2027. The conditions are set at federal level and apply in every canton:
- AHV-liable income in Switzerland in the missing year and in the year of the catch-up;
- the full ordinary contribution for the catch-up year must be paid first;
- catch-up limited, for each missing year, to the « small contribution » (CHF 7,258 in 2026), over ten years at most.
| Example (AHV income in 2025 and 2026) | Paid for 2025 | Catch-up in 2026 | 2026 deduction |
|---|---|---|---|
| A: full contributions, no catch-up | CHF 7,258 | 0 | CHF 7,258 |
| B: nothing paid in 2025 | 0 | CHF 7,258 | CHF 14,516 |
| C: partial payment in 2025 | CHF 4,500 | CHF 2,758 | CHF 10,016 |
Pension fund buy-ins (code 2100)
Ordinary pension fund contributions are already deducted from net salary. Code 2100 takes what is not yet deducted: mainly buy-ins of insurance years, often shown in box 10.2 of the salary certificate, or paid directly to the fund. Enter each taxpayer's amount and attach the pension fund's certificate.
Lump sums received (section 7, codes 1010 and 1020)
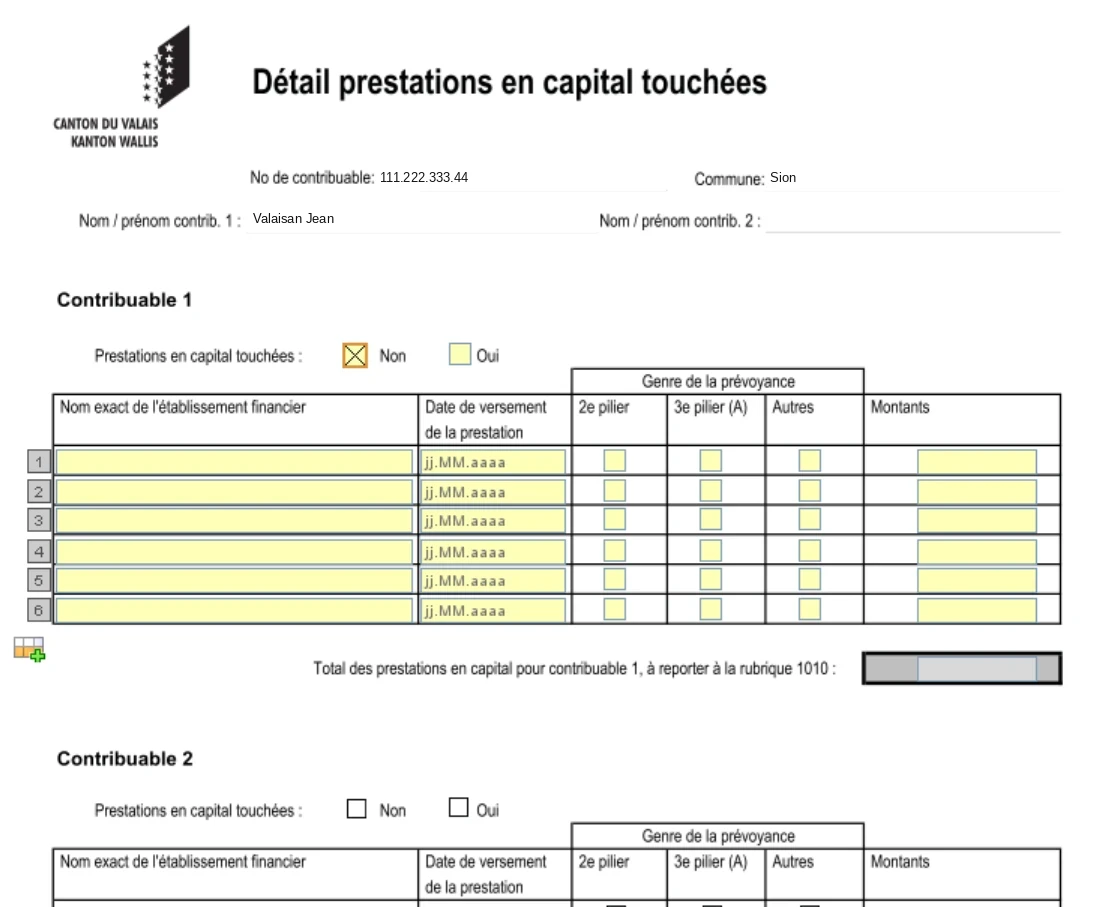
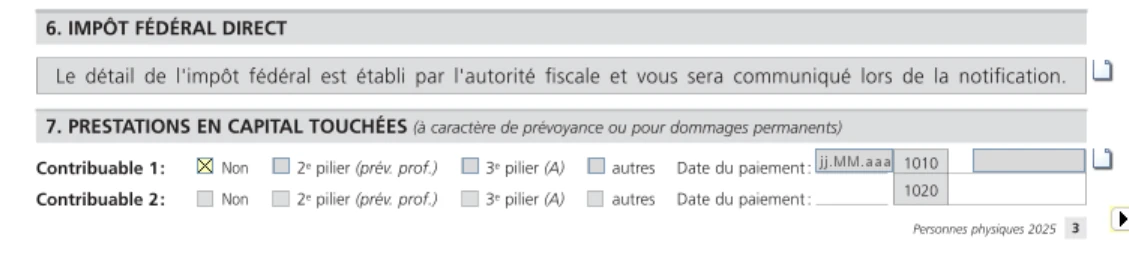
A lump sum received in 2026 from a pension fund, from pillar 3a, or paid after a death or lasting health damage goes in section 7 on page 3: tick the type (« 2e pilier », « 3e pilier A », « autres »), give the payment date and detail the amount in the form. The SCC reminds taxpayers not to forget this section at the very start of its guide.
| Rule | Cantonal and municipal tax | Direct federal tax |
|---|---|---|
| Taxation | Separate from income, full annual tax | Separate from income |
| Rate | Rate for an equivalent pension, at most 4% | One fifth of the ordinary scale |
| Couples and families | Tax reduced by 2%, max. CHF 2,450 | Couples' scale |
| Personal allowances | Not granted | Not granted |
The lump sum is not part of the year's income, but whatever remains on 31 December is part of your wealth (bank account, securities). Money still in the 2nd pillar, pillar 3a or a vested benefits account is not declared as wealth.
Life insurance (pillar 3b)
Life insurance premiums are not deducted here but together with health insurance premiums and savings interest under code 2560, within a shared cap of CHF 7,600 for a couple and CHF 3,800 for a single person in 2026 (see Deductions). The policy's surrender value on 31 December is declared as wealth under code 3400 (see Wealth and debts).
Frequently asked questions
How much can I deduct for pillar 3a in Valais in 2026?
CHF 7,258 if you belong to a pension fund, otherwise 20% of net earned income up to CHF 36,288. Amounts are unchanged from 2025.
Where do I enter pillar 3a in VSTax?
On page 3 of the return, under codes 2210 (taxpayer 1) and 2220 (taxpayer 2), with the institution's name and policy number. Attach the certificate.
Is a 3a catch-up payment deductible in the 2026 Valais return?
Yes. A catch-up made in 2026 for a 2025 gap is deductible for the first time in the 2026 return, on top of the ordinary 2026 contribution, under the federal conditions.
How is a pension or 3a lump sum taxed in Valais?
Separately from income, at the rate for an equivalent pension but at most 4% for cantonal tax, with a 2% reduction (max. CHF 2,450) for couples and families. For federal tax, at one fifth of the ordinary scale.
Rather hand it over?
NeoFidu prepares and files your Valais tax return for you, including holiday homes and source tax cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from official publications of the Valais cantonal tax service (SCC) and the Swiss Federal Tax Administration. VSTax is only available in French and German: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show VSTax 2025 with fictitious data. If in doubt, the official SCC guide prevails.