FriTax · Chapter 9/11
Deductions in FriTax: insurance premiums, childcare, medical costs, donations and social deductions
Key points
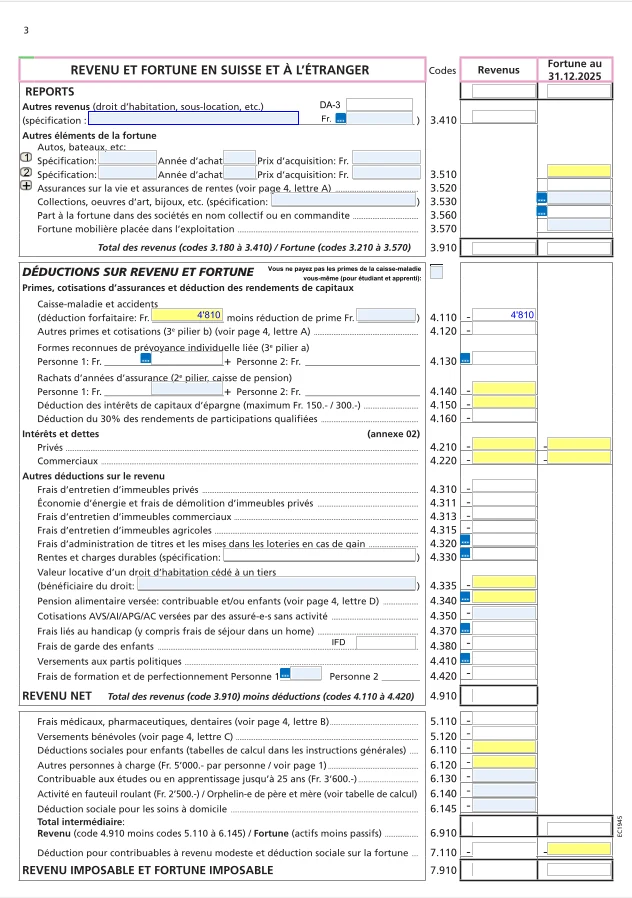
- Health and accident insurance (4.110): a flat rate is granted automatically, CHF 4,810 per adult, CHF 4,210 per young adult in education and CHF 1,140 per child, less any premium reductions received.
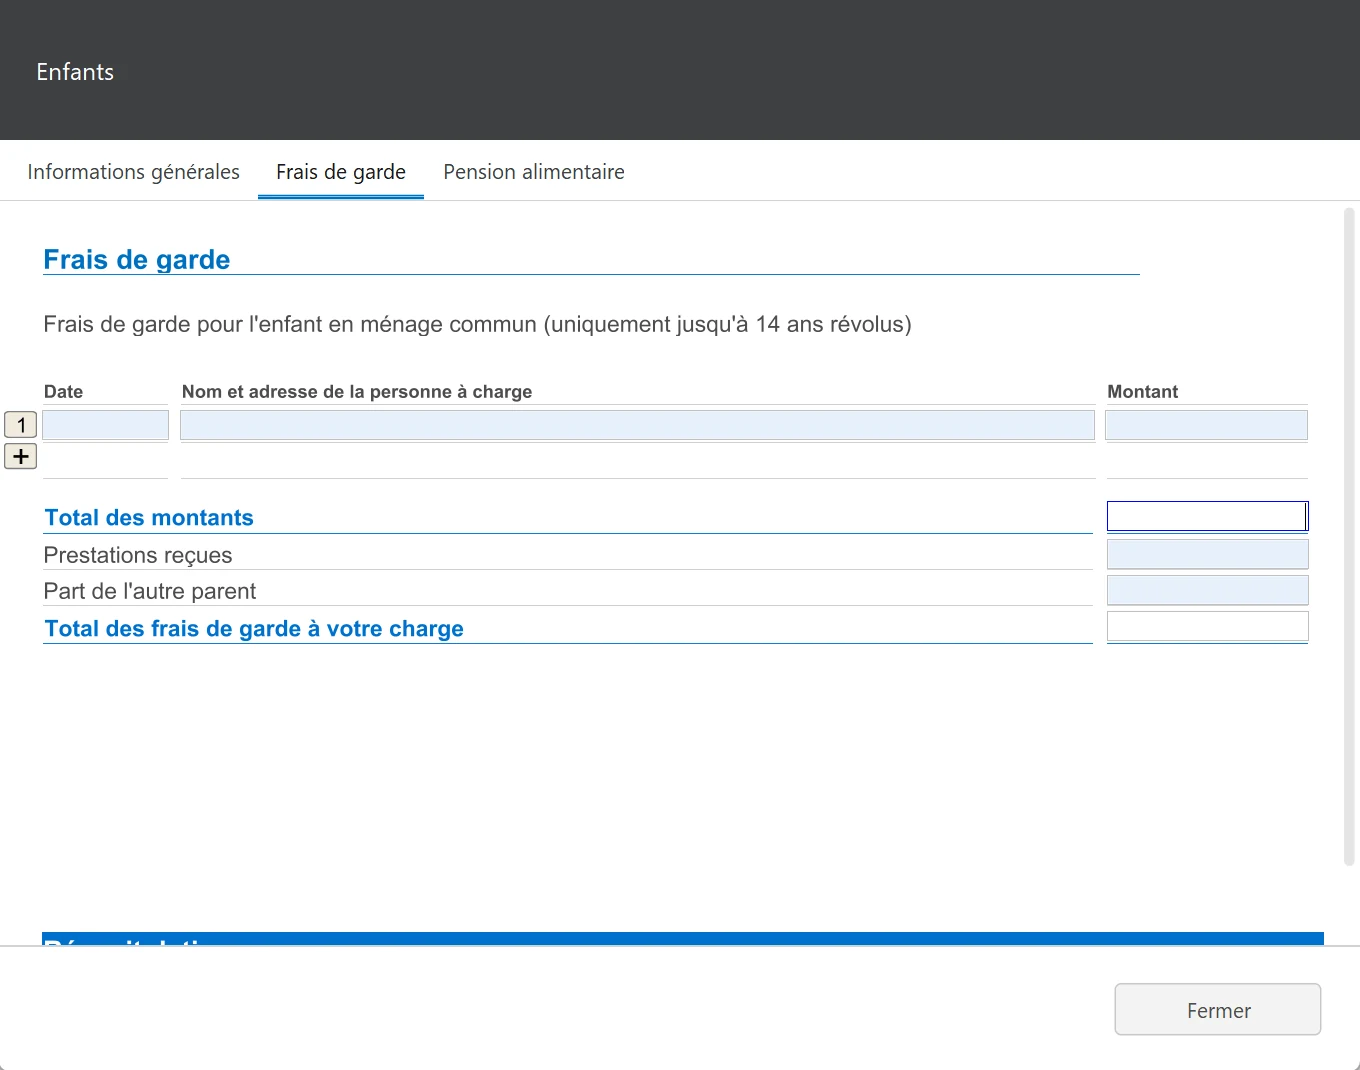
- Childcare (4.380): up to CHF 12,000 per child under 14, if both parents (or the single parent) work or are in education.
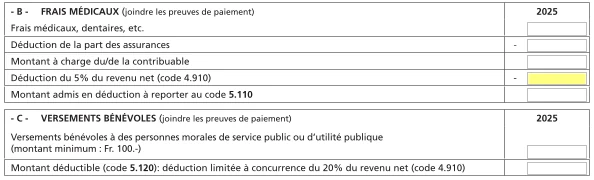
- Medical costs (5.110): the share above 5% of net income; donations (5.120): from CHF 100, up to 20% of net income.
- Child deduction (6.110): CHF 8,600 (CHF 9,600 from the third child), reduced by CHF 100 per CHF 1,000 of net income above CHF 62,700, minimum CHF 7,100.
Insurance premiums and savings interest (codes 4.110 to 4.150)
| Code | Deduction | 2026 amount |
|---|---|---|
| 4.110 | Health and accident insurance (flat rate) | CHF 4,810 per adult (CHF 9,620 for a couple), CHF 4,210 per young adult aged 18 to 25 in education, CHF 1,140 per child |
| 4.120 | Other premiums: life, pure risk, daily allowance, life annuity insurance (pillar 3b) | max. CHF 1,500 couple, CHF 750 other taxpayers |
| 4.130 | Pillar 3a | CHF 7,258 or 20% of income, max. CHF 36,288 (see Pension savings) |
| 4.140 | Pension fund buy-ins | Amount paid, with certificate |
| 4.150 | Interest on savings | max. CHF 300 couple, CHF 150 other taxpayers |
The health insurance flat rate does not depend on the premiums you actually paid: FriTax works it out from your household, based on each person's age on 31 December. If you receive a premium reduction from the ECAS (cantonal social insurance office), only the difference between the flat rate and the subsidy is deductible; if you do not know the subsidy amount, the SCC takes it into account itself. For code 4.120, fill in section A « Assurances »: without it, no deduction. These deductions cannot be offset against each other.
Other income deductions (codes 4.330 to 4.420)
| Code | Deduction | 2026 limit |
|---|---|---|
| 4.330, 4.335 | Annuities and permanent charges, right of residence | Amount paid; income portion for life annuities |
| 4.340 | Maintenance paid to a divorced or separated spouse, and for minor children | Proven amount; not for an adult child |
| 4.350 | AHV/IV/EO/ALV contributions of people without gainful activity | Amount paid |
| 4.370 | Disability costs, including care home stays | Actual costs you bear, or a flat CHF 2,500, 5,000 or 7,500 depending on the helplessness allowance |
| 4.380 | Childcare by third parties | max. CHF 12,000 per child under 14 |
| 4.410 | Membership fees and donations to political parties | max. CHF 5,000 |
| 4.420 | Training and further education for work purposes | max. CHF 12,000 |
- Childcare: for each child under 14 (up to and including the month they turn 14), with proof, if both spouses work, or if the single parent living with the child works. Education or a disability pension counts as work. Food and clothing are not childcare costs.
- Maintenance paid: fill in section « D, Pension alimentaire », separating the spouse's share from the children's. Contributions for a minor child are deductible if the receiving parent has parental authority.
- Training: a link with your current job is no longer required, but initial training (first upper-secondary qualification) and hobbies are not deductible. Only amounts you paid yourself count.
- Disability: deaf people and dialysis patients are entitled to a flat CHF 2,500, with a medical certificate.
Medical costs and donations (codes 5.110 and 5.120)
Unreimbursed medical, pharmaceutical and dental costs paid in 2026 for you and your dependants are deductible for the share above 5% of net income (code 4.910). Fill in section B « Frais médicaux » (medical costs): attach a detailed list with invoices and insurance statements, or use the SCC's listing form, which means you need not attach receipts (the SCC may ask for them later). Cures and diets only count if prescribed by a doctor; a vital special diet (coeliac disease, for example) gives a flat CHF 2,500, except for diabetes.
Donations to public-benefit organisations based in Switzerland, and to the Confederation, cantons and municipalities, are deductible from CHF 100 a year up to 20% of net income. Fill in section C « Versements bénévoles » (donations), with a list and receipts or the SCC's listing form. The SCC publishes a list of tax-exempt Fribourg organisations. The payment date counts for the deduction.
Social deductions (codes 6.110 to 7.110)
| Code | Deduction | 2026 amount |
|---|---|---|
| 6.110 | Per minor child or child in education | CHF 8,600 (CHF 9,600 from the 3rd child), reduced with net income, minimum CHF 7,100 (CHF 8,100 from the 3rd) |
| 6.120 | Other dependant unable to support themselves | CHF 5,000 |
| 6.130 | Taxpayer in education or apprenticeship, up to age 25 | CHF 3,600, in their own return |
| 6.140 | Working wheelchair user without AHV/disability pension; full orphan | CHF 2,500; CHF 8,600 (tapering) |
| 6.145 | Flat-rate allowances received for home care of a relative | Amount received, cantonal tax only |
| 7.110 | Taxpayer on a low income | From CHF 4,100 to CHF 11,100 depending on the situation, tapering |
The child deduction is reduced by CHF 100 per CHF 1,000 of net income above a threshold of CHF 62,700 for the first child, raised by CHF 10,100 for each additional child. Example: with one child and CHF 70,000 net income, the deduction is CHF 7,800; with two children the threshold rises to CHF 72,800 and the deduction stays at CHF 17,200. FriTax applies this scale automatically.
What changes for direct federal tax
There is no separate return for direct federal tax (IFD): the SCC applies the differences itself. To get an idea of your federal tax:
| Code | Cantonal tax 2026 | Direct federal tax 2026 |
|---|---|---|
| 2.110 Commuting | max. CHF 12,000 | max. CHF 3,300 |
| 2.510 Both spouses working | CHF 500 | 50% of the lower income, min. CHF 8,600, max. CHF 14,100 |
| 4.110 to 4.150 Premiums and savings interest | Flat rates above | CHF 3,700 couple, CHF 1,800 others (CHF 5,500 and 2,700 without 2nd pillar or 3a), + CHF 700 per child |
| 4.380 Childcare | max. CHF 12,000 | max. CHF 25,800 |
| 4.410 Political parties | max. CHF 5,000 | max. CHF 10,600 |
| 4.420 Training | max. CHF 12,000 | max. CHF 13,000 |
| 6.110 Child | CHF 8,600, tapering | CHF 6,800, plus a CHF 263 tax reduction per child |
| Married couple | Full splitting | CHF 2,800 deduction and married scale |
Frequently asked questions
How much can I deduct for health insurance in Fribourg?
A flat CHF 4,810 per adult, CHF 4,210 per young adult aged 18 to 25 in education and CHF 1,140 per child, regardless of the premiums actually paid. Premium reductions received are subtracted from the flat rate.
How much is the child deduction in Fribourg in 2026?
CHF 8,600 per child (CHF 9,600 from the third), reduced by CHF 100 per CHF 1,000 of net income above CHF 62,700 for the first child, but not below CHF 7,100. For federal tax, CHF 6,800 per child.
Are nursery costs deductible in Fribourg?
Yes, up to CHF 12,000 per child under 14 (CHF 25,800 for federal tax), with receipts, if both parents work or are in education, or if the single parent works.
When do medical costs become deductible?
For the share above 5% of net income. With net income of CHF 60,000, only unreimbursed costs above CHF 3,000 are deductible.
Rather hand it over?
NeoFidu prepares and files your Fribourg tax return for you, including property and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from official publications of the Fribourg cantonal tax service (SCC) and the Swiss Federal Tax Administration. FriTax is available in French and German only: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show FriTax 2025 with fictitious data. If in doubt, the SCC's general instructions prevail.