FriTax · Chapter 8/11
Property in FriTax: imputed rent, tax value, rental income and upkeep costs (schedule 04)
Key points
- Every owner fills in the property list (schedule 04, « Etat des immeubles »). For a home you live in, declare the imputed rent (income) and tax value (wealth) from your last assessment notice, under code 3.310.
- New owners since 1 January 2026 or extension works: fill in the SCC's property questionnaire.
- Upkeep costs (4.310): each year and for each property, choose the flat rate (10% of gross income for a building built after 2015, 20% otherwise) or actual costs.
- Energy-saving investments (4.311): 100% deductible, with actual costs only, and can be carried over to the next two years.
The property list (schedule 04)
One line per property: municipality, land register number, ownership share, use (your home, rented out, second home), imputed rent or rents, tax value and upkeep costs. FriTax carries the totals over to codes 3.310 to 3.350 (income and wealth) and 4.310 to 4.315 (costs). A property is either private or business, depending on its main use.
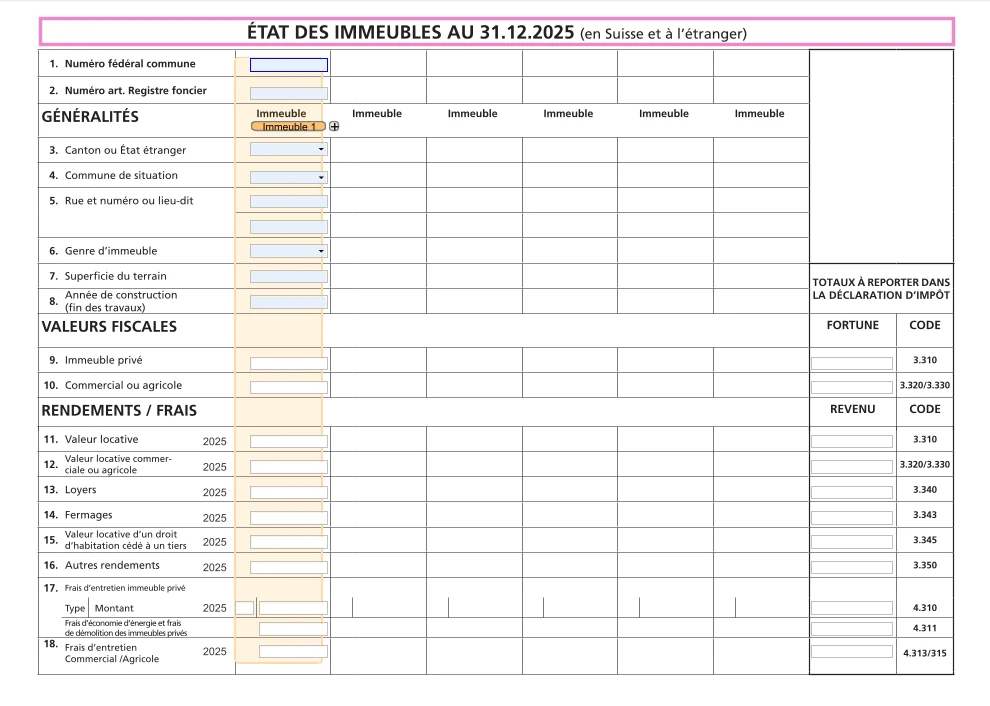
Imputed rent and tax value (code 3.310)
For the home you live in, use the imputed rent (« valeur locative ») and tax value (« valeur fiscale ») from your last assessment notice: they were raised in 2014 and in principle remain current. If you rent out or sublet part of the property, declare the rent under code 3.340 and the imputed rent is reduced proportionally.
| Situation | What to do |
|---|---|
| Purchase after 1 January 2026 | Fill in the property questionnaire with its instructions (www.fr.ch/scc/estimation_immeubles, municipality or SCC) |
| Extension, interior renovation, loft conversion, carport, in-ground pool | Report the works using the same questionnaire |
| Home permanently under-used | Reduction possible for direct federal tax only, on a reasoned request (not for a second home) |
| Property abroad | Market value in francs, used only to set the tax rate |
The abolition of imputed rent, decided at federal level, only takes effect on 1 January 2029. For the 2026 return, imputed rent is still taxable and upkeep costs and mortgage interest are still deductible.
Rents, furnished lets and rights of residence (codes 3.340 to 3.350)
- Rents received (3.340): gross amount, including any reduction granted to the caretaker and service-charge payments not settled separately. If heating and charges are included in the rent under the lease, a flat 15% can be deducted from rents.
- Furnished holiday home: declare 4/5 of the takings, or 2/3 if you also provide linen. The SCC publishes a guidance note on furnished and short-term lets.
- Farm rents (3.343) and rights of residence (3.345): the owner of a property subject to a right of residence declares its value under 3.345 and deducts it as a permanent charge under 4.335; the beneficiary declares it under 3.410.
- Other property income (3.350): solar electricity sold (net method: only if production exceeds your consumption, in francs), forestry income, building-right annuities, one-off photovoltaic subsidies not deducted from costs.
Upkeep costs: flat rate or actual costs (code 4.310)
| Private property | Flat rate (% of gross income) |
|---|---|
| Built after 31 December 2015 | 10% |
| Built earlier | 20% |
The flat rate is calculated on the property's total gross income (imputed rent, rents, right of residence). You can choose each year and for each property between the flat rate and actual costs. The flat rate is not available for business and farm property, property let mainly for business purposes, undeveloped land (parking spaces, storage) and land subject to a paid building right.
For actual costs, open « Frais effectifs des immeubles », « Immeuble 1 » in FriTax (« Ajouter un formulaire » for a second property): this is the SCC's allocation form (« formule de répartition »), explained in the special guidance note. The ECAB building insurance premium and municipal property contributions are already listed; each invoice is numbered, described and classified (deductible upkeep or non-deductible improvement), with copies of the invoices. Count the net amount, after discounts, insurance payouts and subsidies. For private property, the payment date counts. Your own labour is not deductible.
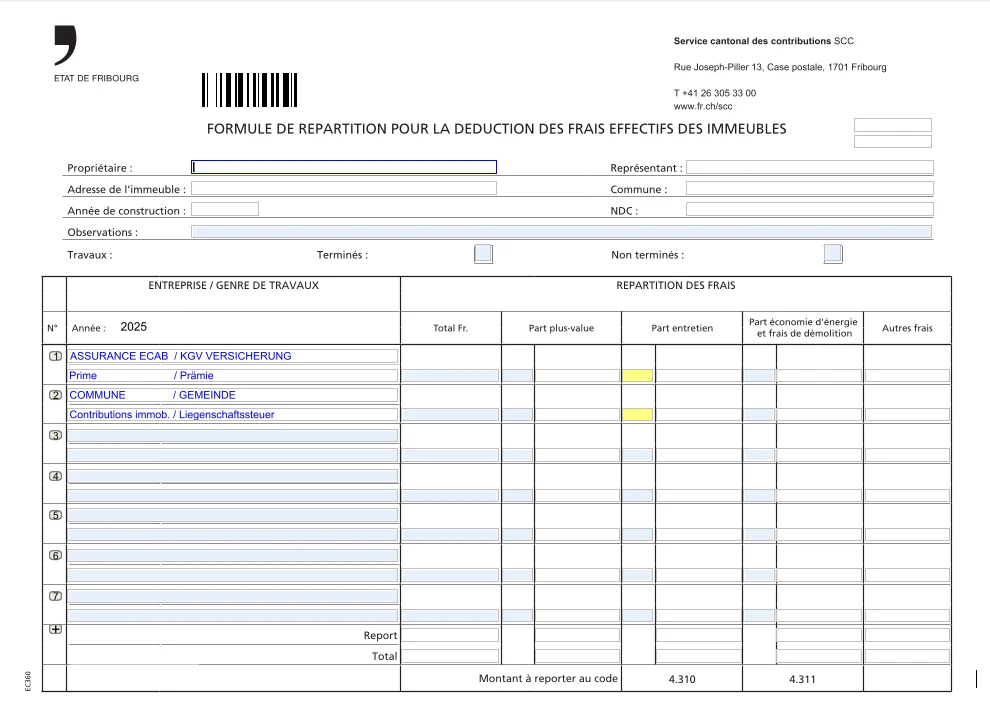
Property in another canton, or a sale
Property located in another canton is taxed there; it appears in the property list for the tax split and the rate calculation, and debts and interest are split proportionally. When you sell a private property, you automatically receive a form for real estate capital gains tax, separate from the return. An economic transfer (assignment of a purchase right, transfer to business assets) must be reported to the SCC within 30 days.
Frequently asked questions
Where do I find my imputed rent in Fribourg?
On your last assessment notice, which shows your property's imputed rent (income) and tax value (wealth). New owners first fill in the SCC's property questionnaire.
What is the flat-rate upkeep deduction in Fribourg?
10% of gross income for a building built after 31 December 2015, 20% for older buildings. You can choose each year between this flat rate and actual costs.
Are solar panels deductible in Fribourg?
Yes, in full, under code 4.311, if you choose actual costs, except in the first five years after construction. Electricity sold is taxable under code 3.350 if production exceeds your consumption.
Is imputed rent still taxed in 2026?
Yes. Its abolition at federal level takes effect on 1 January 2029. Until then, imputed rent remains taxable and upkeep costs and mortgage interest remain deductible.
Rather hand it over?
NeoFidu prepares and files your Fribourg tax return for you, including property and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from official publications of the Fribourg cantonal tax service (SCC) and the Swiss Federal Tax Administration. FriTax is available in French and German only: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show FriTax 2025 with fictitious data. If in doubt, the SCC's general instructions prevail.