FriTax · Chapter 5/11
Pension savings in FriTax: pillar 3a (4.130), 3a catch-up, pension fund buy-ins (4.140) and lump sums
Key points
- Pillar 3a: code 4.130, up to CHF 7,258 with a pension fund, or 20% of earned income up to CHF 36,288 without a 2nd pillar. Only contributions paid in 2026 count, with a certificate.
- New in 2026: 3a contributions missed in 2025 can be made up and deducted for the first time.
- Pension fund buy-ins: code 4.140, with the fund's certificate, unless they already appear in box 10.2 of the salary certificate. No lump-sum withdrawal in the following three years.
- Pension lump sums (2nd pillar and pillar 3a) are taxed separately, at 1% to 5% basic cantonal tax; they are declared under letter E on the last page.
Pillar 3a (code 4.130)
| Situation | Maximum deduction 2026 |
|---|---|
| Member of a pension fund (2nd pillar) | CHF 7,258 |
| No 2nd pillar (self-employed, for example) | 20% of earned income, max. CHF 36,288 |
The deduction requires gainful activity liable to AHV contributions. It is kept during a temporary interruption (unemployment, illness, military service). Each working spouse can deduct contributions to a contract in their own name. Only contributions actually paid in 2026 count, and the bank or insurer's certificate must be attached. There is no deduction if your gainful activity made a loss.
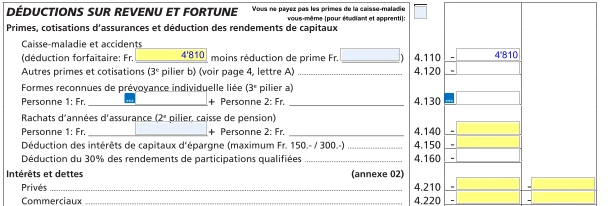
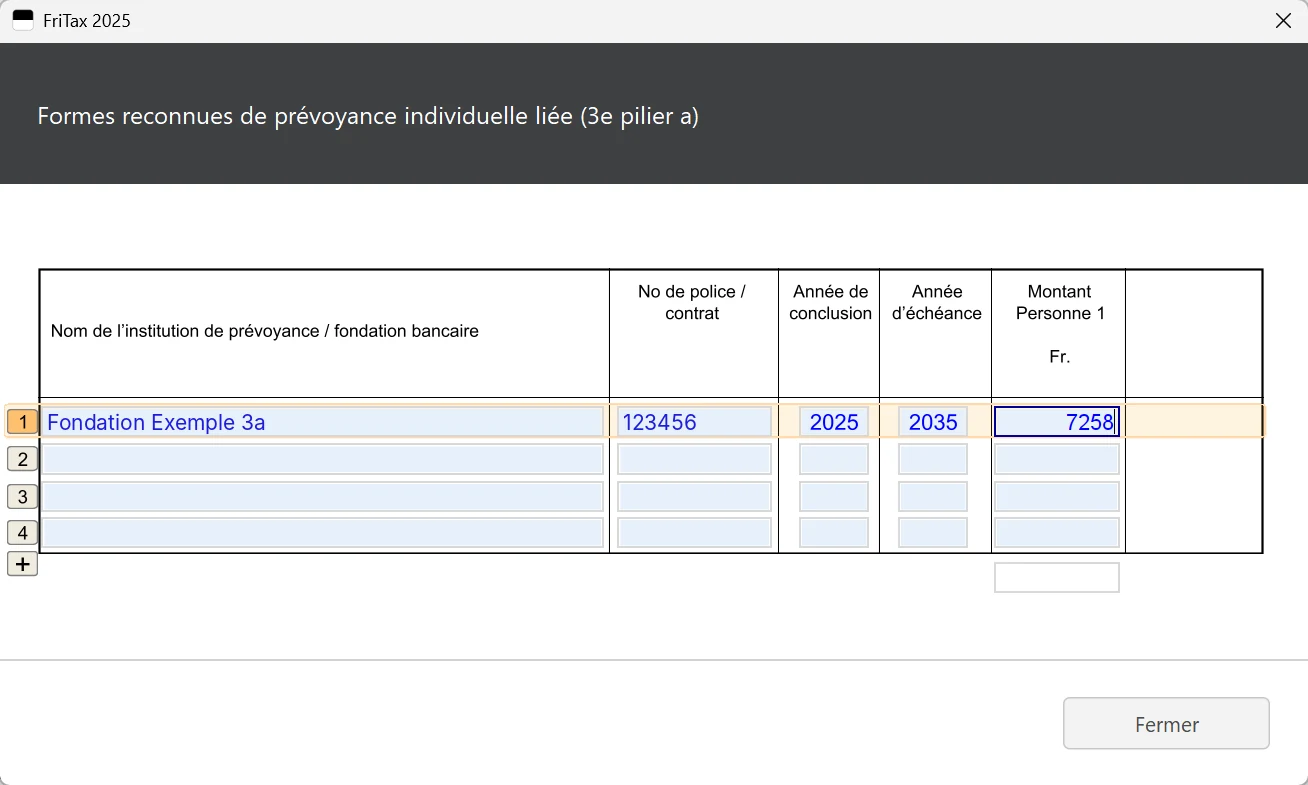
New in 2026: pillar 3a catch-up payments
From 2026, you can fill a 3a contribution gap from earlier years, starting with 2025 at the earliest. The catch-up payment is deductible for the first time in the 2026 return, filed in 2027. The conditions are set at federal level and apply in every canton:
- AHV-liable income in Switzerland in the missing year and in the year of the catch-up;
- the full ordinary contribution for the catch-up year must be paid first;
- catch-up limited, for each missing year, to the « small contribution » (CHF 7,258 in 2026), over ten years at most.
| Example (AHV income in 2025 and 2026) | Paid for 2025 | Catch-up in 2026 | 2026 deduction |
|---|---|---|---|
| A: full contributions, no catch-up | CHF 7,258 | 0 | CHF 7,258 |
| B: nothing paid in 2025 | 0 | CHF 7,258 | CHF 14,516 |
| C: partial payment in 2025 | CHF 4,500 | CHF 2,758 | CHF 10,016 |
Pension fund buy-ins (code 4.140)
Ordinary pension fund contributions are already deducted from net salary. Code 4.140 only takes buy-ins of insurance years paid directly to the fund, with its certificate stating the maximum buy-in allowed. A buy-in shown in box 10.2 of the salary certificate is already deducted from salary: do not enter it again (it does count towards the 3% flat-rate base).
People without gainful activity (early retirement, students, disability) who pay their own AHV/IV/EO contributions deduct them under code 4.350, with proof. For these contributions, the AHV office values property at 155% of its tax value.
Lump-sum benefits (letter E on the last page)
A lump sum from a pension fund, pillar 3a or AHV/disability insurance, or a lump sum paid after a death or permanent damage to health, is not added to income: it is taxed separately. Declare it in section « E, Prestations en capital » (lump-sum benefits) on the last page. Lump sums received in the same year are added together, including both spouses'.
| Band of the lump sum | Basic cantonal tax rate |
|---|---|
| First CHF 50,000 | 1% |
| Next CHF 50,000 | 2% |
| Next CHF 50,000 | 3% |
| Next CHF 50,000 | 4% |
| Above CHF 200,000 | 5% |
- Married couples living together and single-parent families get a CHF 10,000 deduction on the total.
- If the year's total is below CHF 10,000, no tax is levied.
- The tax is reduced by 50% for a lump sum paid because of disability.
- A vested benefit paid into a new employer's fund within the year is not taxable.
- If you repay a home-ownership advance withdrawal, you can reclaim the tax paid at the time: written request with the fund's form, within three years of repayment.
Before they are paid out, 2nd pillar and pillar 3a assets are not part of your wealth: do not declare them as insurance or accounts. The SCC provides an Excel calculator at fr.ch/scc/pp.
Frequently asked questions
How much pillar 3a can I deduct in Fribourg in 2026?
CHF 7,258 if you belong to a pension fund, otherwise 20% of earned income up to CHF 36,288, under code 4.130. The amounts are unchanged from 2025.
Is a 3a catch-up payment deductible in the 2026 Fribourg return?
Yes. From 2026, 3a contributions missed in 2025 can be made up, if you had AHV-liable income in both years and paid the full 2026 contribution. Attach the catch-up certificate from your bank or insurer.
Do I declare the pension buy-in shown in box 10.2 of my salary certificate?
No. It is already deducted from net salary (box 11). Code 4.140 only takes buy-ins paid directly to the pension fund.
How is a 2nd pillar withdrawal taxed in Fribourg?
Separately from income, at 1% to 5% basic cantonal tax depending on the amount, plus municipal, parish and federal tax. Below CHF 10,000 a year there is no tax; couples get a CHF 10,000 deduction.
Rather hand it over?
NeoFidu prepares and files your Fribourg tax return for you, including property and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from official publications of the Fribourg cantonal tax service (SCC) and the Swiss Federal Tax Administration. FriTax is available in French and German only: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show FriTax 2025 with fictitious data. If in doubt, the SCC's general instructions prevail.