FriTax · Chapter 3/11
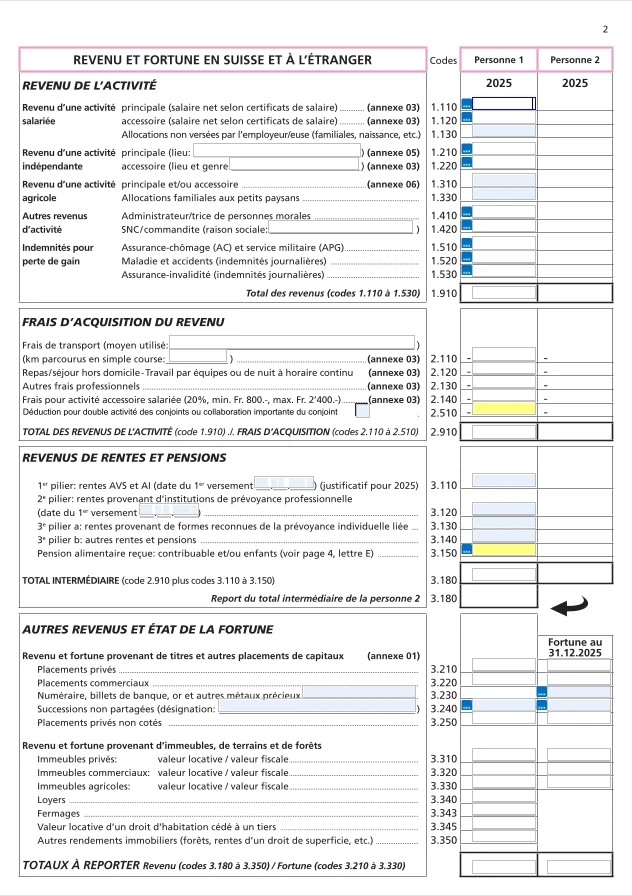
Salary, benefits and pensions in FriTax: codes 1.110 to 1.530 and 3.110 to 3.150
Key points
- You declare your net salary, i.e. box 11 of the salary certificate, under code 1.110. Work interruptions (illness, unpaid leave) must be reported.
- Employed side income: code 1.120, with a 20% flat-rate expense deduction (min. CHF 800, max. CHF 2,400) under code 2.140.
- Unemployment, loss-of-earnings and daily allowances not on a salary certificate: codes 1.510 to 1.530.
- AHV and disability pensions under code 3.110, pension fund under 3.120, pillar 3a under 3.130, other pensions under 3.140; maintenance received under 3.150.
Main employment (code 1.110)
Enter the net salary from box 11 of each employer's salary certificate, and attach the certificates. For couples, person 2 has their own column. If you had a work interruption in 2026 (illness, accident, unpaid leave, unemployment), say so and declare the benefits received under codes 1.510 to 1.530. Where needed, FriTax opens the employment section of schedule 03 « Revenu d'activité-Frais d'acquisition » (employment income and expenses).
| Salary certificate | Where it goes in FriTax |
|---|---|
| Box 11, net salary | Code 1.110 (1.120 for side income) |
| Box 10.2, pension fund buy-in deducted from pay | Already deducted from net salary: do not enter it again under 4.140 |
| Boxes 13.1 and 13.2, expense allowances | Not added, but the SCC may check they covered real costs |
| Box F ticked (free transport) | No commuting deduction for that journey (see Work expenses) |
| Box G ticked (canteen, subsidised meals) | Half meal deduction, CHF 7.50 per day |
Side income and allowances (codes 1.120 and 1.130)
- Code 1.120: all income from employed side work (teaching, refereeing, weekend jobs). FriTax works out the 20% flat-rate expense deduction, at least CHF 800 (but not more than the income) and at most CHF 2,400, under code 2.140.
- Code 1.130: family, birth or maternity allowances paid directly by a fund rather than by the employer, family allowances for the self-employed, tips not on the certificate.
- Code 1.410: board attendance and directors' fees, net of AHV/IV/EO/ALV contributions. No other deduction is allowed.
- Code 1.420: share of income from a general or limited partnership, per the partnership's questionnaire.
Self-employed people (code 1.210) and farmers (1.310) must attach a balance sheet, income statement and schedule 05 or 06: these cases are beyond the scope of this guide.
Unemployment, loss of earnings and daily allowances (codes 1.510 to 1.530)
Unemployment benefits go here, with the fund's statement, unless they already appear on a salary certificate entered under 1.110. The same applies to loss-of-earnings allowances (military service, civil protection, civilian service, J+S courses) paid directly by the compensation fund, and to sickness, accident or disability daily allowances.
Pensions and annuities (codes 3.110 to 3.140)
| Income | Code | Note |
|---|---|---|
| AHV and disability pensions (old age, widow(er), orphan, extraordinary pensions) | 3.110 | Attach the 2026 statement |
| Pension fund (2nd pillar) pensions, military insurance from 1994 | 3.120 | 100%; transitional rules at federal level for older pensions |
| Pillar 3a annuities | 3.130 | Attach the certificate |
| SUVA or accident insurance pensions, liability pensions, life annuities | 3.140 | Life annuities: income portion only |
Not taxable and not declared: AHV/disability supplementary benefits, helplessness allowances, social assistance, inheritances, legacies and gifts, most study grants, military pay and volunteer firefighter pay (up to CHF 9,000 for cantonal tax) and bridging benefits for older unemployed people.
Maintenance received (code 3.150)
Maintenance received from a former spouse and contributions for minor children are taxable, including for children born outside marriage. Complete section « D, Pension alimentaire » on the last page, separating the spouse's share from the children's, and attach the supporting documents. Maintenance for an adult child is not taxable for you (nor deductible for the payer).
Other income without its own code (for example a right of residence you benefit from) goes under code 3.410, stating what it is. Subletting a flat you rent is only taxable if it brings in more than the rent you pay.
Frequently asked questions
Do I enter gross or net salary in FriTax?
Net salary, i.e. box 11 of the salary certificate, under code 1.110. Social security and ordinary pension fund contributions have already been deducted from it.
Where do I declare unemployment benefits in Fribourg?
Under codes 1.510 to 1.530, with the unemployment fund's statement, unless they already appear on a salary certificate declared under 1.110.
What flat-rate deduction applies to side income in Fribourg?
20% of the income declared under code 1.120, at least CHF 800 (but not more than the income) and at most CHF 2,400 a year, under code 2.140. Higher costs can be claimed with receipts.
Are AHV supplementary benefits taxable?
No. AHV/disability supplementary benefits, helplessness allowances and social assistance are not taxable and are not declared.
Rather hand it over?
NeoFidu prepares and files your Fribourg tax return for you, including property and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from official publications of the Fribourg cantonal tax service (SCC) and the Swiss Federal Tax Administration. FriTax is available in French and German only: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show FriTax 2025 with fictitious data. If in doubt, the SCC's general instructions prevail.