FriTax · Chapter 7/11
Wealth and debts in FriTax: vehicles, life insurance, the debts list (schedule 02) and interest
Key points
- Car, boat (code 3.510): market value; as a rule 30% depreciation in the first year, then 20% of the remaining value per year.
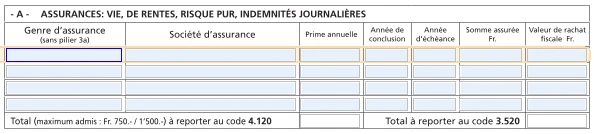
- Life insurance with a surrender value (code 3.520): value certified at 31 December, after filling in section A « Assurances » (insurance). Household furniture is not taxable.
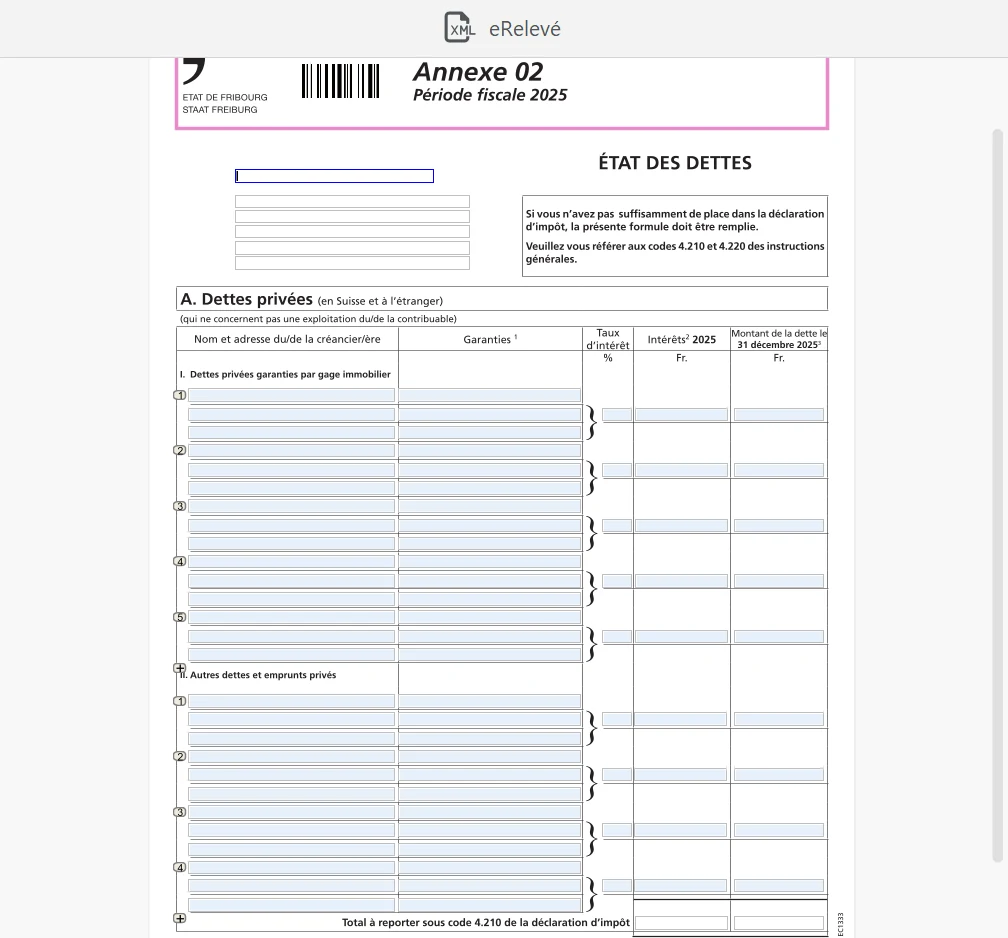
- Debts: in the debts list (schedule 02, « Etat des dettes »), with the creditor's name and address. Private interest paid (4.210) is deductible up to gross investment income plus CHF 50,000.
- The social deduction on wealth is CHF 55,000 for a single person and CHF 105,000 for a couple or family, tapering off.
Other assets (codes 3.510 to 3.570)
| Asset | Code | Value to declare |
|---|---|---|
| Cars, motorbikes, boats | 3.510 | Market value; as a rule purchase price less 30% in year 1, then 20% of the remaining value each year |
| Life and annuity insurance with a surrender value | 3.520 | Surrender value (including profit shares) certified at 31 December 2026 |
| Collections, works of art, jewellery, riding horses | 3.530 | Market value |
| Movable assets invested in a business | 3.570 | Per schedule 05 (self-employed) or 06 (farmers) |
| Household furniture | None | Not taxable |
The debts list (schedule 02)
Enter each private debt with the creditor's name and exact address (in Switzerland or abroad), the balance at 31 December 2026 and the interest due in 2026, and attach statements or certificates. A debt that is not proven or has no identified creditor is not accepted. Keep private debts clearly separate from business debts (code 4.220), which count for the self-employed's AHV contributions.
Private interest paid (code 4.210)
- Deductible: mortgage and other interest due in 2026, related fees and commissions, late-payment interest, current account bank charges.
- Cap: gross income from private movable and immovable assets (codes 3.210, 3.240, 3.250, 3.310, 3.340 and 3.350) plus CHF 50,000. Income from qualifying holdings only counts at 70%.
- Not deductible: interest and commissions on a construction loan, debt repayments, private leasing, securities administration and salary account fees (which go under 4.320).
- If you have taxable assets in another canton or abroad, debts and interest are split proportionally.
Net wealth, social deduction and tax scale
Net wealth is gross wealth less debts. Fribourg then subtracts a social deduction on wealth (code 7.110), worked out automatically by FriTax:
| Situation | Deduction | Tapering |
|---|---|---|
| Single person without dependent children | CHF 55,000 if net wealth does not exceed CHF 75,000 | CHF 10,000 less per additional CHF 25,000; nil from CHF 200,001 |
| Married couple or single person with dependent child | CHF 105,000 if net wealth does not exceed CHF 125,000 | CHF 20,000 less per additional CHF 35,000; nil from CHF 300,001 |
Basic cantonal wealth tax is progressive, from 0.5‰ on the first CHF 50,000 to 3.7‰ on the band from CHF 1 to 1.2 million. Above CHF 1.2 million of taxable wealth, the whole amount is taxed at 2.9‰. It is multiplied by the cantonal multiplier of 96%, then municipal and parish tax are added. Direct federal tax does not tax wealth.
Frequently asked questions
Do I need to declare my car in Fribourg?
Yes, under code 3.510, at market value. As a rule, 30% depreciation on the purchase price is accepted in the first year, then 20% of the remaining value each following year.
Is mortgage interest fully deductible?
Yes, up to the gross income from your private assets (including imputed rent) plus CHF 50,000. Interest on a construction loan is not deductible.
Is pillar 3a part of taxable wealth?
No. Before they are paid out, 2nd pillar and pillar 3a assets are not subject to wealth tax. Only pillar 3b life insurance with a surrender value is declared under code 3.520.
From what level of wealth do you pay wealth tax in Fribourg?
Thanks to the social deduction, a single person pays nothing up to about CHF 55,000 of net wealth, and a couple up to about CHF 105,000. The deduction then decreases and disappears from CHF 200,001 (single) or CHF 300,001 (couple).
Rather hand it over?
NeoFidu prepares and files your Fribourg tax return for you, including property and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from official publications of the Fribourg cantonal tax service (SCC) and the Swiss Federal Tax Administration. FriTax is available in French and German only: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show FriTax 2025 with fictitious data. If in doubt, the SCC's general instructions prevail.