JuraTax · Chapter 6/11
Accounts, securities and crypto in JuraTax: the securities list (form 5A), eRelevé and withholding tax
Key points
- All accounts, securities and investments at 31 December 2026 go on form 5A « État des titres » (securities list). Total wealth goes to code 740, income to code 340.
- With JuraTax Online, import your bank's electronic tax statement (« eRelevé fiscal ») as a PDF: accounts, securities and debts fill in automatically, and the PDF is attached to your supporting documents.
- Declare Swiss income subject to withholding tax in category A: this is the condition for refunding the 35% Swiss withholding tax.
- Private capital gains are not taxable; pillar 2, pillar 3a and vested benefits balances are not declared.
What the securities list must contain
Form 5A lists all wealth held in securities and other investments that you, your spouse and your minor children owned or held in usufruct on 31 December 2026, in Switzerland and abroad, in this order:
- a. Savings and deposit books, current accounts, salary accounts, postal accounts, in Switzerland and abroad.
- b. Bonds, shares, shares in limited companies and cooperatives, participation and dividend-right certificates, cryptocurrencies.
- c. Investment fund units, including the renovation fund of a condominium (PPE).
- d. Mortgage claims and other claims, private loans, foreign securities, even if blocked.
- e. Lottery, Sport-Toto, Swiss Lotto and PMU winnings and prizes in kind.
| Column | Content |
|---|---|
| 4 and 5 | Market value and taxable value at 31 December 2026: nominal value for accounts and claims, closing price on the last trading day of December for listed securities |
| 6, category A | Gross Swiss income that suffered the 35% withholding tax (dividends, bond interest, interest on accounts above CHF 200 a year) |
| 7, category B | Income not subject to withholding tax: foreign securities and assets, interest on accounts up to CHF 200 a year, private loans, mortgage claims, lottery winnings not subject to withholding tax |
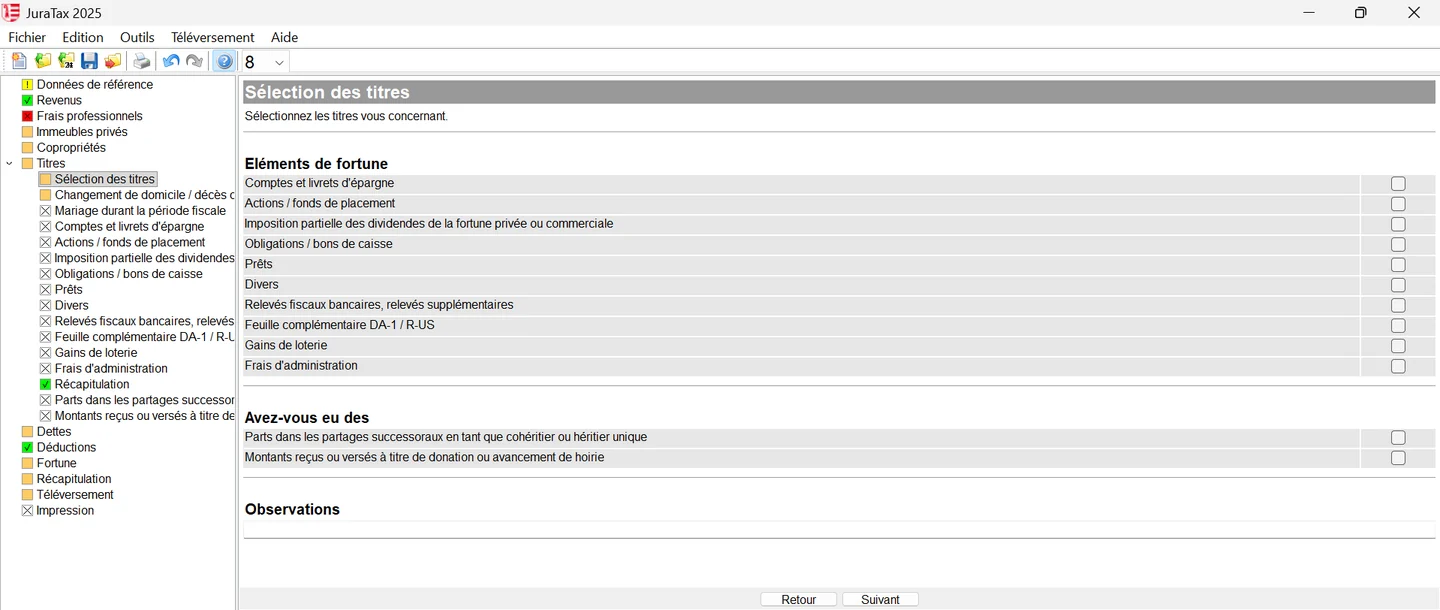
In JuraTax, the « Titres » (securities) section starts with a selection (« Sélection des titres »): accounts and savings books, shares and investment funds, partial taxation of dividends, bonds, loans, miscellaneous, bank tax statements, DA-1 / R-US sheet, lottery winnings, administration fees, as well as shares in estates and gifts received or made. JuraTax builds the securities list (form 5A) from them.
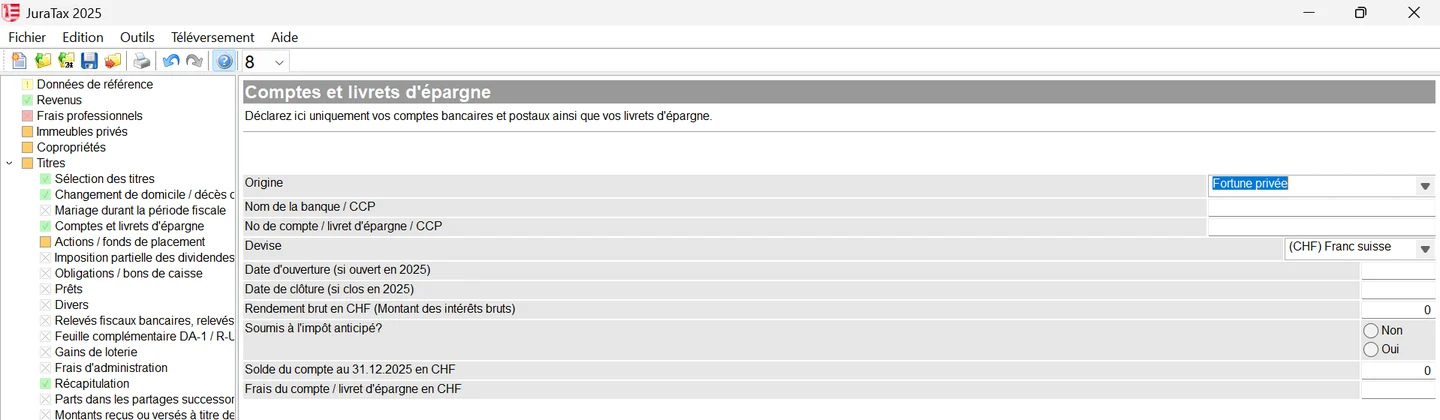
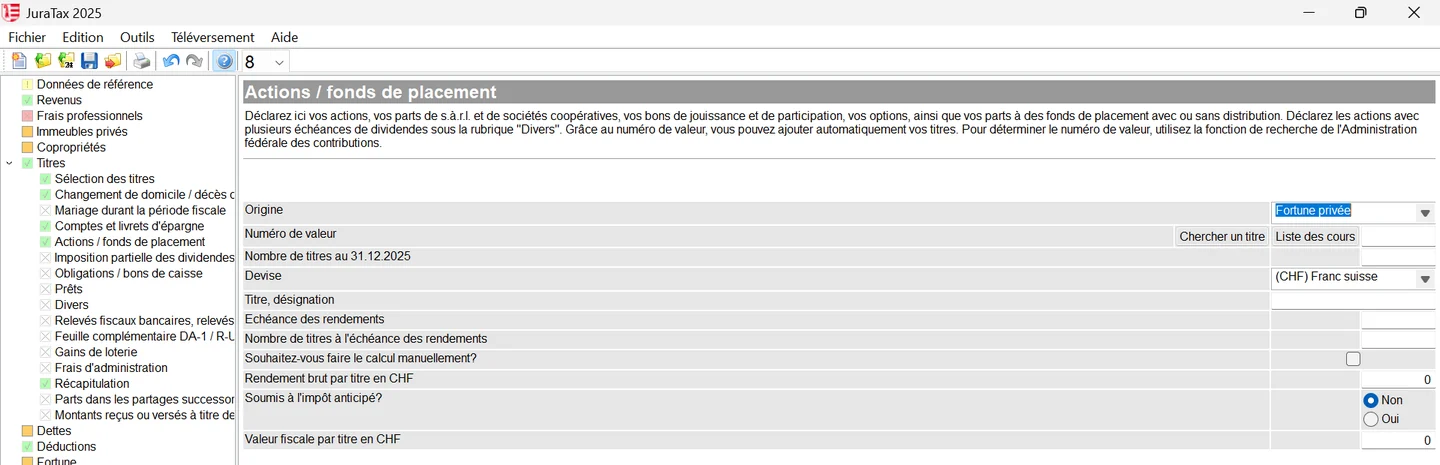
Each account is entered with the bank, number, currency, opening or closing dates in 2026, gross interest, the subject to withholding tax box (« Soumis à l'impôt anticipé ») and the balance on 31 December. For a share or fund, enter the security number (ISIN or valor): the « Chercher un titre » (find a security) and « Liste des cours » (price list) buttons automatically fill in the name, the 31 December price and dividends from the Federal Tax Administration's official list. You then only enter the number of securities.
Import your bank's electronic tax statement
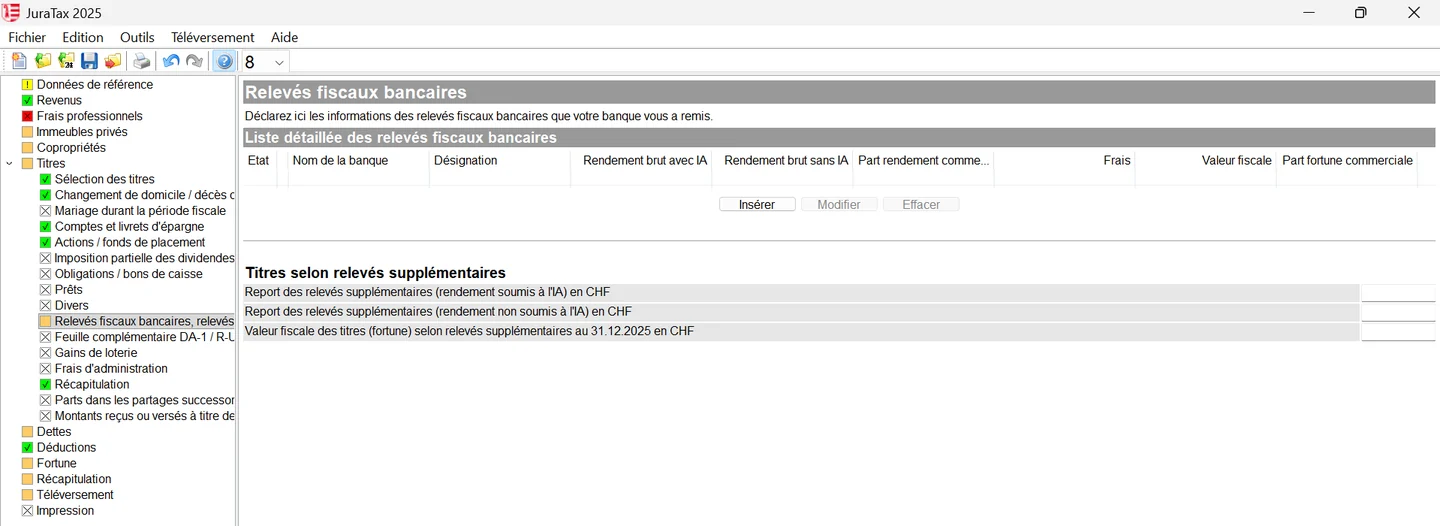
Since 2022, JuraTax Online imports electronic tax statements (« eRelevés fiscaux ») in the PDF format produced by your bank. The details load automatically into the securities sections (accounts, savings books, shares) and debts, and the PDF is added to the supporting documents sent electronically. Then check each line: an account closed last year may remain after carrying over last year's data and must be deleted. The self-employed and farmers must keep private and business items separate. The desktop program has no import: tick « Relevés fiscaux bancaires, relevés supplémentaires » (bank tax statements) in the securities selection and copy, for each statement, the bank, income with and without withholding tax, fees and tax value. The tax statement must always be enclosed with the return.
Cryptocurrencies, unlisted securities and foreign currencies
- Cryptocurrencies: one line per currency, at the rate published by the Federal Tax Administration (ICTax) on 31 December, otherwise the platform's rate. Gains from selling are not taxable for a private investor.
- Foreign currencies: enter the market price and the conversion rate from the official 2026 price list.
- Unlisted securities: market value under circular no. 28 of the Swiss Tax Conference. If the 2026 value is not yet known, provisionally enter the value at 31 December 2025.
- Unlisted Swiss holdings: they are taxed at a reduced value, the tax value minus 30% of the difference between tax value and nominal value. For Jura companies, this value appears on the notice sent to the board of directors.
- Non-taxable assets: do not declare your pillar 2, pillar 3a or vested benefits accounts.
US securities and foreign taxes: DA-1 and R-US
US securities with additional US withholding are not listed on form 5A but on the supplementary sheet DA-1/R-US. It is also used to claim credit for foreign taxes withheld on 2026 dividends and interest (forms DA-2 and DA-3 for other cases). German dividends also go on the DA-1/R-US. Without the DA-1/R-US enclosed, no refund is made. The forms can be downloaded from jura.ch, under « Formulaires impôts spéciaux » (special tax forms).
Swiss withholding tax refund
The 35% withholding tax deducted from Swiss income is refunded if you declare all securities and their income on form 5A and live in the canton of Jura on 31 December. It is refunded separately once your securities list has been processed if it exceeds CHF 500; a smaller amount is credited as a tax payment for the following year. An undeclared security forfeits the refund and exposes you to back taxes and a fine.
Lottery winnings and management fees
- Lotteries and gambling: for cantonal tax, a single win is exempt up to CHF 1,000,000; above that, it is taxed separately at a unit rate of 2%. Stakes are deducted at 5%, up to CHF 5,000. Enclose the original proof and report to the withholding tax unit in Delémont.
- Securities management fees: only actual fees for management entrusted to third parties in an open custody account are deductible, for the portion subject to VAT. Purchase and sale commissions and advisory fees are not. They must be documented.
Frequently asked questions
How do I import an eRelevé fiscal into JuraTax?
In JuraTax Online, import the PDF electronic tax statement provided by your bank: accounts, securities and debts fill in automatically and the PDF is attached to your supporting documents. The desktop program cannot send supporting documents electronically.
How do I declare cryptocurrencies in Jura?
On the securities list (form 5A), together with shares and bonds, one line per currency, at the Federal Tax Administration's ICTax rate on 31 December. Private capital gains are not taxable.
When is Swiss withholding tax refunded in Jura?
Separately, once the securities list has been processed, if it exceeds CHF 500. Below that, it is credited as a payment on the following year's tax. You must live in the canton of Jura on 31 December.
Do I declare my pillar 3a on the securities list?
No. Pillar 3a, pillar 2 and vested benefits balances are not taxable until paid out and are not declared. Only the year's 3a contributions are deducted, under code 520.
Rather hand it over?
NeoFidu prepares and files your Jura tax return for you, including property, undivided estates and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from the 2025 general guide (« Guide général ») of the Jura cantonal tax service (Service des contributions), its official forms and the Swiss Federal Tax Administration's Jura cantonal sheet (February 2026), which states that indexed amounts remain unchanged for the 2026 tax period. JuraTax is not available in English: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show JuraTax 2025 with fictitious data. If in doubt, the tax service's general guide prevails.