JuraTax · Chapter 4/11
Work expenses in JuraTax: form 7, actual costs or the 20% flat rate
Key points
- For cantonal tax, you choose between actual costs (general expenses, commuting, meals) and a 20% flat rate of income, up to CHF 4,100. In a couple, each spouse can choose.
- Actual costs: CHF 2,000 of general expenses for a full-time job all year, public transport at cost, car at CHF 0.70 per km (if no public transport), meals at CHF 15 per day, up to CHF 3,200.
- On remote work days, no commuting or meal costs are deductible. An annual GA travelcard remains deductible for the whole year.
- For federal tax, only actual costs count: so always complete the « actual costs » part of form 7.
Actual costs or flat rate: the Jura choice
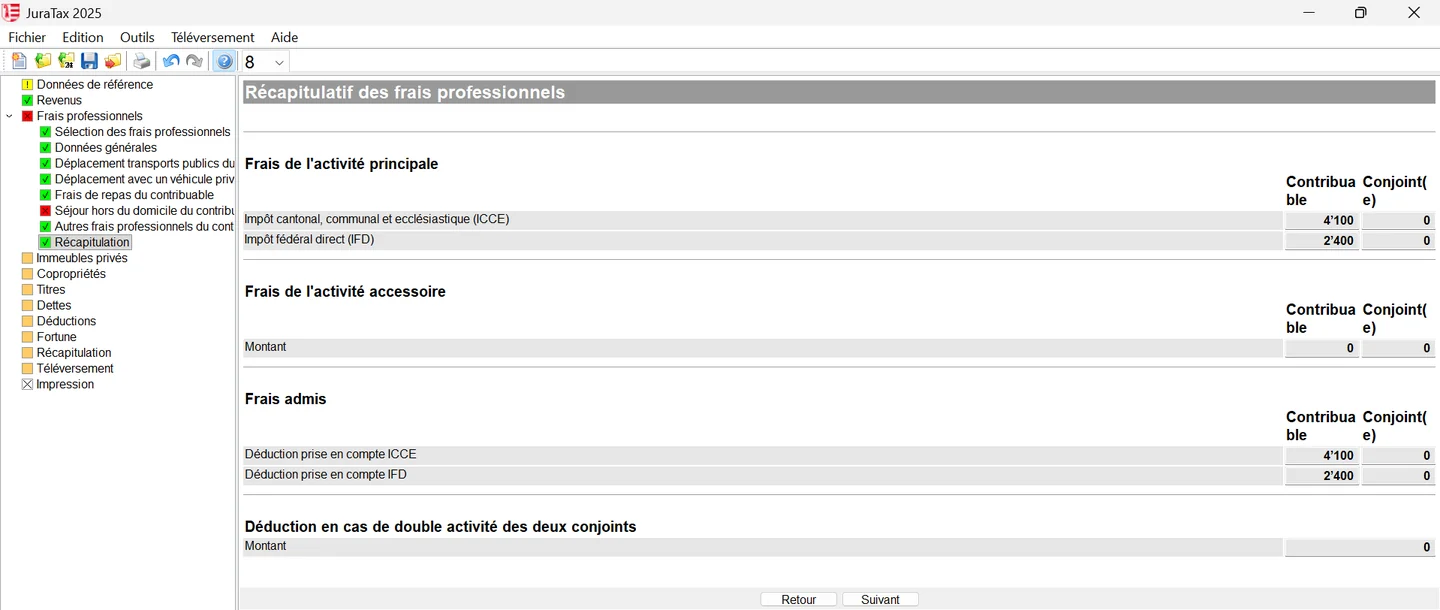
Form 7 « Frais professionnels liés à une activité dépendante » (employee work expenses) is always completed. Its first part lists actual costs (codes 7000 to 7750). Its second part calculates the flat-rate deduction (codes 7800 to 7850): 20% of income, up to CHF 4,100 for a main occupation, CHF 2,000 for a self-employed person who also has a salaried job. For cantonal tax, the higher of the two totals is carried to code 500 (500C for your spouse). JuraTax compares them itself in the work expenses « Récapitulation » (summary): you only enter your actual costs. The flat rate replaces all actual costs, commuting and meals included: it suits low incomes and short commutes.
| Example (net salary CHF 60,000, 225 days) | Actual costs | Flat rate |
|---|---|---|
| General expenses (7000) | CHF 2,000 | Included |
| Annual bus pass (7100) | CHF 800 | Included |
| Meals away from home, 225 days at CHF 15 (7300), capped | CHF 3,200 | Included |
| Total | CHF 6,000 | CHF 4,100 (20%, capped) |
Actual costs in detail (form 7)
| Code | Cost | Amount allowed |
|---|---|---|
| 7000 | General work expenses (clothing, tools, books) | CHF 2,000 for a full-time job all year, reduced by rate and duration (CHF 1,000 half-time, CHF 500 for 3 months full-time) |
| 7100, 7110 | Train, bus, tram | Actual cost of the pass |
| 7150 | Bicycle, moped | max. CHF 700 per year |
| 7200, 7210 | Motorbike, scooter | CHF 0.40 per km |
| 7250 to 7280 | Car, if public transport is missing or unusable | CHF 0.70 per km up to 7,999 km a year, CHF 0.65 from 8,000 to 14,999 km, CHF 0.60 from 15,000 km |
| 7300, 7310 | Meals away from home | CHF 15 per day, max. CHF 3,200 |
| 7350, 7360 | Canteen meals or employer contribution (box G of the certificate) | CHF 7.50 per day, max. CHF 1,600 |
| 7400, 7410 | Shift work | CHF 15 per day, max. CHF 3,200 |
| 7450, 7460 | Room and board away from home (home only at weekends) | CHF 30 per day or CHF 6,400 per year (CHF 22.50 or CHF 4,800 with a canteen), plus the rent of a room or studio |
| 7500 | Costs of secondary employment | 20% of net income, min. CHF 800, max. CHF 2,400 |
| 7700 | Union dues and professional books above CHF 1,000 | Actual amount |
- Generally count 225 working days a year, minus extended holidays, remote work and absences.
- The distance must be reasonably long, as a rule more than 1.5 km each way.
- Flexible hours alone do not justify the car: you need missing public transport, unfavourable hours, a disability or another serious reason.
- Going home at lunchtime is capped at CHF 15 per day. Car-sharing payments received are subtracted from your costs.
- If box F of the salary certificate is ticked (free transport by the employer), no commuting costs are allowed. With a company car, answer yes to the question in the salary entry screen.
- No meal deduction is allowed if your main meal costs you less than CHF 10.
In JuraTax, screen by screen
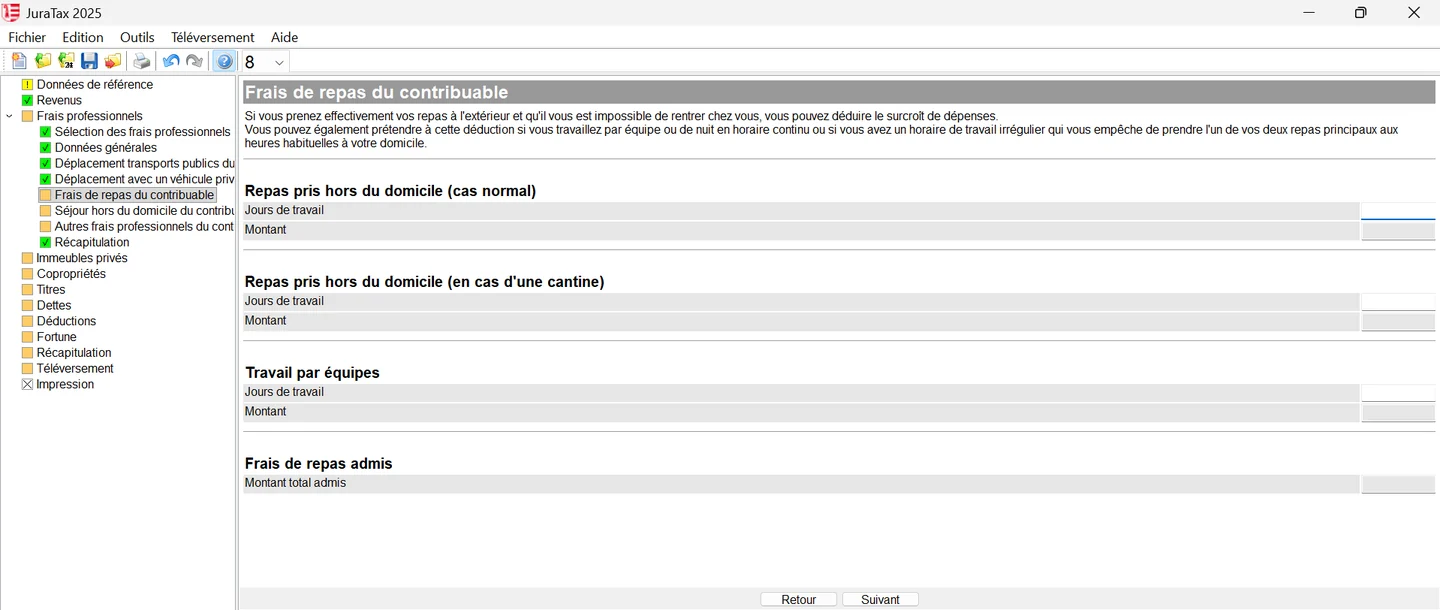
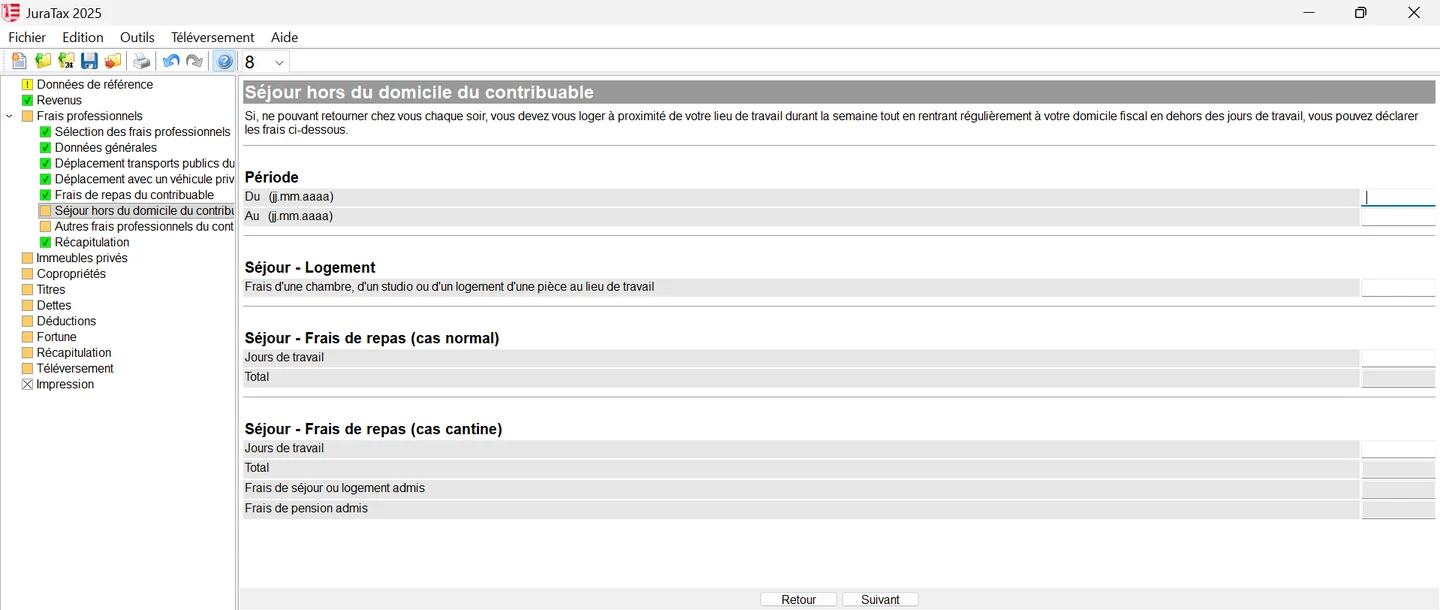
In the tree, « Frais professionnels » (work expenses) starts with a selection: tick, for the taxpayer and the spouse, commuting costs (« frais de déplacements », public or private transport), meals away from home (« frais de repas pris hors du domicile ») and staying away from home during the week (« séjour hors du domicile durant la semaine »). JuraTax then only shows the screens you need.
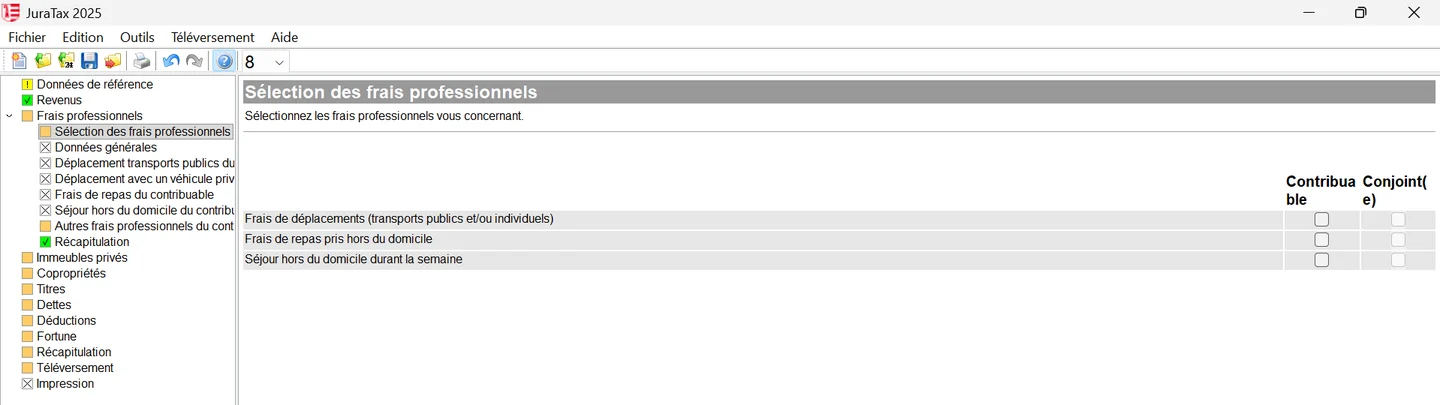
| JuraTax screen | What to enter |
|---|---|
| « Données générales » (general data) | Residence, employer, place of work, period and activity rate |
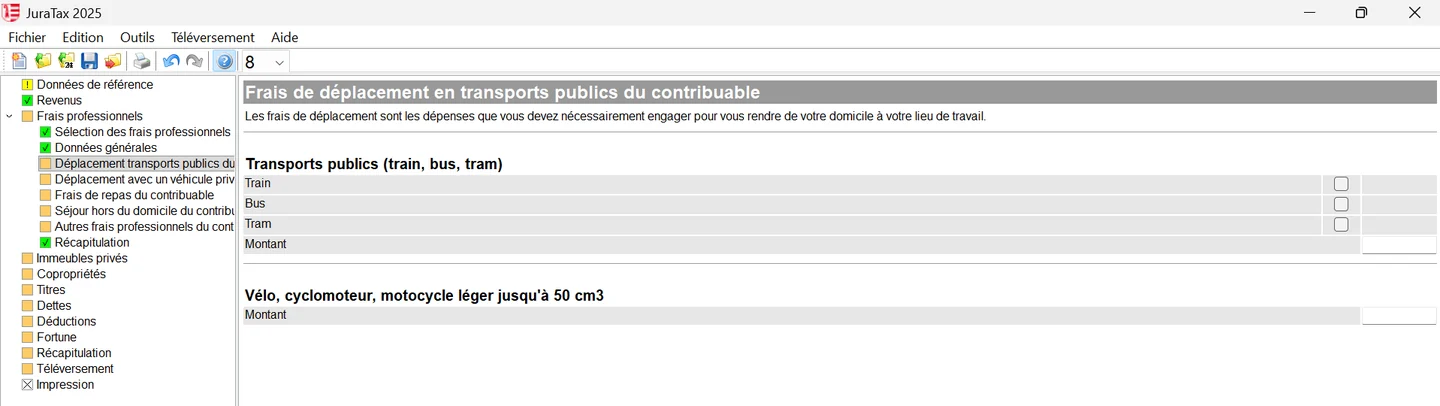
| « Déplacement transports publics » (public transport) | Tick train, bus or tram and enter the pass price; bicycle or moped: separate amount |
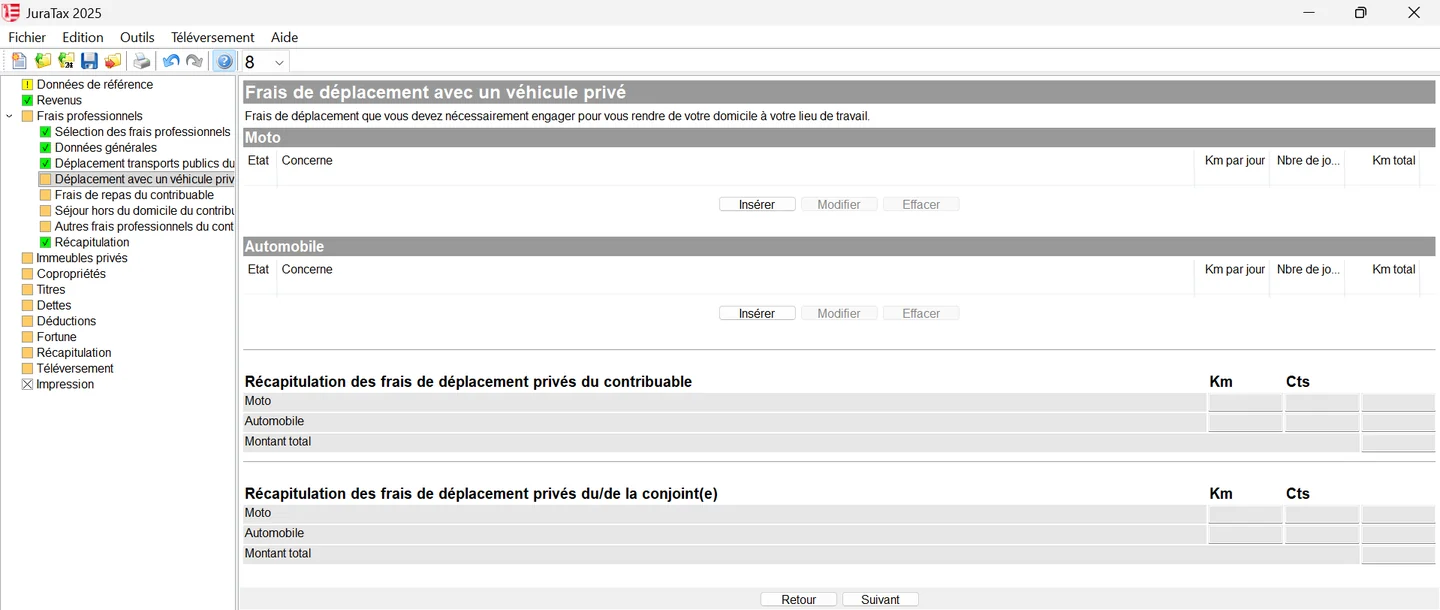
| « Déplacement avec un véhicule privé » (private vehicle) | « Insérer » a motorbike or car line, then km per day and working days: JuraTax calculates total km and the amount |
| « Frais de repas » (meals) | Number of working days in the normal case, with a canteen or for shift work; JuraTax shows the total allowed |
| « Séjour hors du domicile » (staying away) | Period from / to, cost of the room or studio, working days for meals |
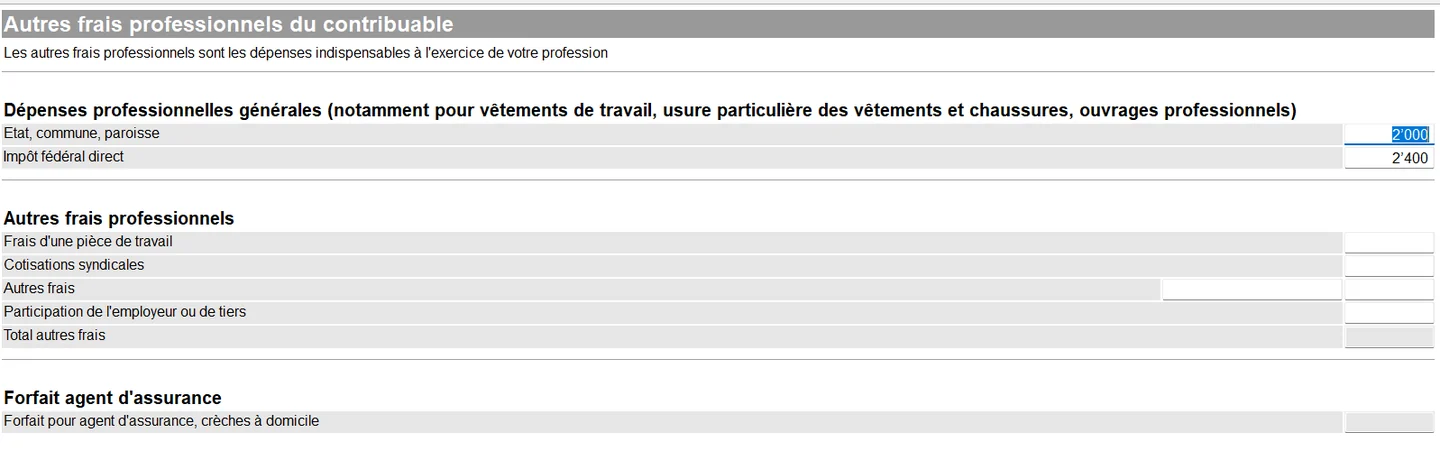
| « Autres frais professionnels » (other work expenses) | Union dues, professional books above CHF 1,000 |
| « Récapitulation » (summary) | Comparison of actual costs and the 20% flat rate |
Remote work
On remote work days or short-time work (RHT) days you can deduct neither commuting nor meal costs. A home office is only allowed if the work cannot, or cannot reasonably, be done at the workplace; personal convenience is not enough. Useful exception: an annual GA travelcard bought for the year remains deductible for the whole year, even with remote work. Your employer shows remote work days on the salary certificate.
Both spouses working (code 505)
Married couples where both spouses work, as a main or secondary occupation, deduct up to CHF 2,700 under code 505, but no more than the lower of the two incomes. The deduction is also allowed when one spouse substantially helps in the other's profession or business. No deduction if the activity makes a loss. JuraTax calculates it from the income entered.
What differs for direct federal tax
| Cost | Cantonal tax | Direct federal tax (2025 amounts) |
|---|---|---|
| Flat rate or actual costs | Yes: 20%, max. CHF 4,100 | No: actual costs only |
| Other work expenses | CHF 2,000 general expenses | Flat 3% of net salary, min. CHF 2,000, max. CHF 4,000 |
| Commuting | No cap | max. CHF 3,300 |
| Two-earner couple | max. CHF 2,700 | 50% of the lower income, min. CHF 8,600, max. CHF 14,100 |
Frequently asked questions
How much can I deduct for my car in Jura?
CHF 0.70 per km up to 7,999 km a year, CHF 0.65 from 8,000 to 14,999 km and CHF 0.60 beyond, provided public transport is missing or unusable. There is no cantonal cap; federal tax caps commuting at CHF 3,300 (2025).
Is the 20% flat rate worth it?
It replaces all actual costs, commuting and meals included, and is capped at CHF 4,100. It suits short commutes and low incomes. As soon as you deduct meals or car journeys, actual costs are often higher.
Can I deduct meals when working from home?
No. For remote work or short-time work days, no meal or commuting costs are deductible in the canton of Jura.
Where do I deduct union dues in JuraTax?
Under code 7700 of form 7, together with professional books above CHF 1,000. Enclose proof if the dues exceed CHF 500.
Rather hand it over?
NeoFidu prepares and files your Jura tax return for you, including property, undivided estates and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from the 2025 general guide (« Guide général ») of the Jura cantonal tax service (Service des contributions), its official forms and the Swiss Federal Tax Administration's Jura cantonal sheet (February 2026), which states that indexed amounts remain unchanged for the 2026 tax period. JuraTax is not available in English: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show JuraTax 2025 with fictitious data. If in doubt, the tax service's general guide prevails.