JuraTax · Chapter 3/11
Salary, pensions and other income in JuraTax: codes 100 to 260 and 400
Key points
- Code 100: the net salary from box 11 of the salary certificate, family allowances included. A pension fund buy-in is not subtracted from the salary: it is deducted under code 515.
- Secondary employment income (code 110) must be backed by a salary certificate, whatever the amount.
- AHV and disability pensions (200, 210) are 100% taxable, as are unemployment benefits (230). Supplementary benefits and helplessness allowances are not taxable.
- Maintenance payments received for yourself and your minor children are taxable (250, 260); those paid for an adult child are not.
Employment income (codes 100 to 130)
| Code | What | Where to find it |
|---|---|---|
| 100 / 100C | Net salary, including family allowances, bonuses, commissions, private use of a company car | Box 11 of the salary certificate |
| 105 / 105C | Benefits in kind (free board and lodging) and private share of expenses | Scale in the general guide, page 18 |
| 110 / 110C | Net secondary employment income | Salary certificate from the secondary employer |
| 120 / 120C | Disability insurance (AI) daily allowances | AI statement |
| 130 / 130C | Attendance fees, directors' fees, net of contributions | Statement or salary certificate |
Net salary is what remains after AHV/IV/EO, unemployment insurance, non-occupational accident insurance and pension fund contributions. It includes bonuses, gratuities, travel allowances, family allowances and private use of a company car. If your certificate shows a pension fund buy-in (box 10.2), add it back to box 11: the buy-in is deducted separately under code 515 (see Retirement savings). Declare all of your spouse's income, whatever your matrimonial regime, unless you are divorced or separated.
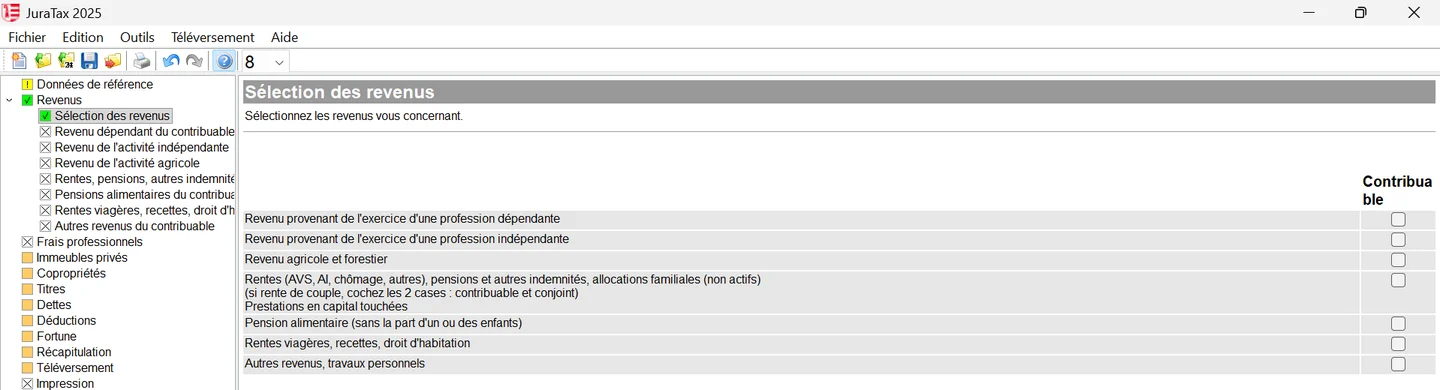
In JuraTax, the « Revenus » (income) section starts with a selection (« Sélection des revenus »): tick the income that applies to you (employment, self-employment, farming, pensions and lump sums, maintenance, life annuities, other income). Only the ticked screens open afterwards.
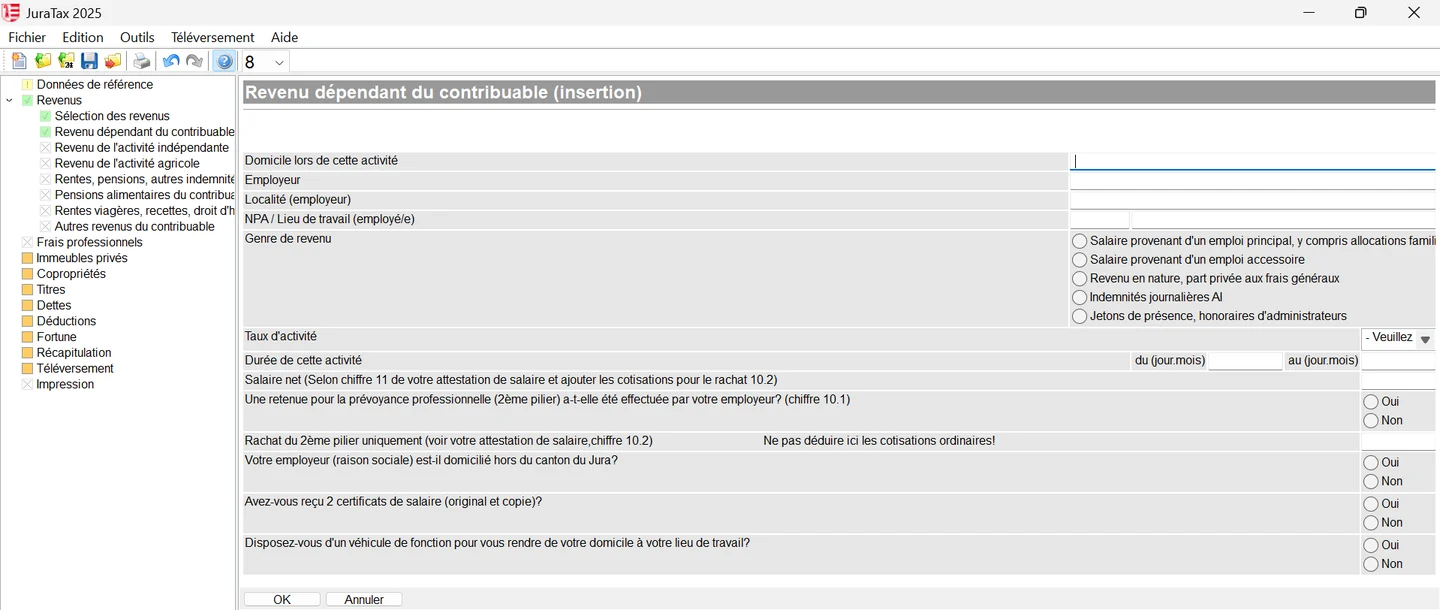
Enter one salary per employer with « Insérer » (insert): residence, employer, place of work, type of income (« Genre de revenu »: main job, secondary job, benefits in kind, disability allowances, directors' fees), activity rate and period, then the net salary from box 11. JuraTax then asks: pillar 2 deduction (box 10.1), pillar 2 buy-in (box 10.2, excluding ordinary contributions), employer outside the canton of Jura, two certificates received and company car. The first two feed the buy-in deduction, the others the list of supporting documents and commuting costs.
For self-employed, farming or partnership income (codes 140 to 190), fill in form 2 or 3 and follow the tax service's supplementary guide for the self-employed and farmers. Enclose the official salary certificates if your employer is outside the canton of Jura.
Pensions, annuities and other benefits (codes 200 to 260)
| Code | Income | Taxable share |
|---|---|---|
| 200 | AHV pension, including children's pensions | 100% |
| 210 | Disability (AI) pension, including supplements; state the disability rate | 100% |
| 220 | Occupational pension fund (pillar 2) pensions | Generally 100%; 60% or 80% for old contracts funded by your own contributions, concluded before 1987 and paid out before 2002 |
| 230 | Unemployment benefits (enclose the statement) | 100% |
| 240 | Other pensions and benefits: SUVA pensions, loss-of-earnings (APG), maternity allowance, military insurance, daily allowances (except AI), family allowances for people not working | 100% |
| 250 | Maintenance received for yourself | 100% |
| 260 | Maintenance received for your minor children | 100% |
- Declare the amounts received in 2026. A pension paid retroactively is taxed separately, at the rate of the year of the decision.
- Orphans' pensions are declared by the surviving parent; adult orphans declare them themselves.
- AHV/AI supplementary benefits and helplessness allowances are not taxable: do not declare them.
- Maintenance paid to or for an adult child is taxable neither for the child nor for the parent receiving it.
- Pensions taxed abroad count 100% towards the tax rate.
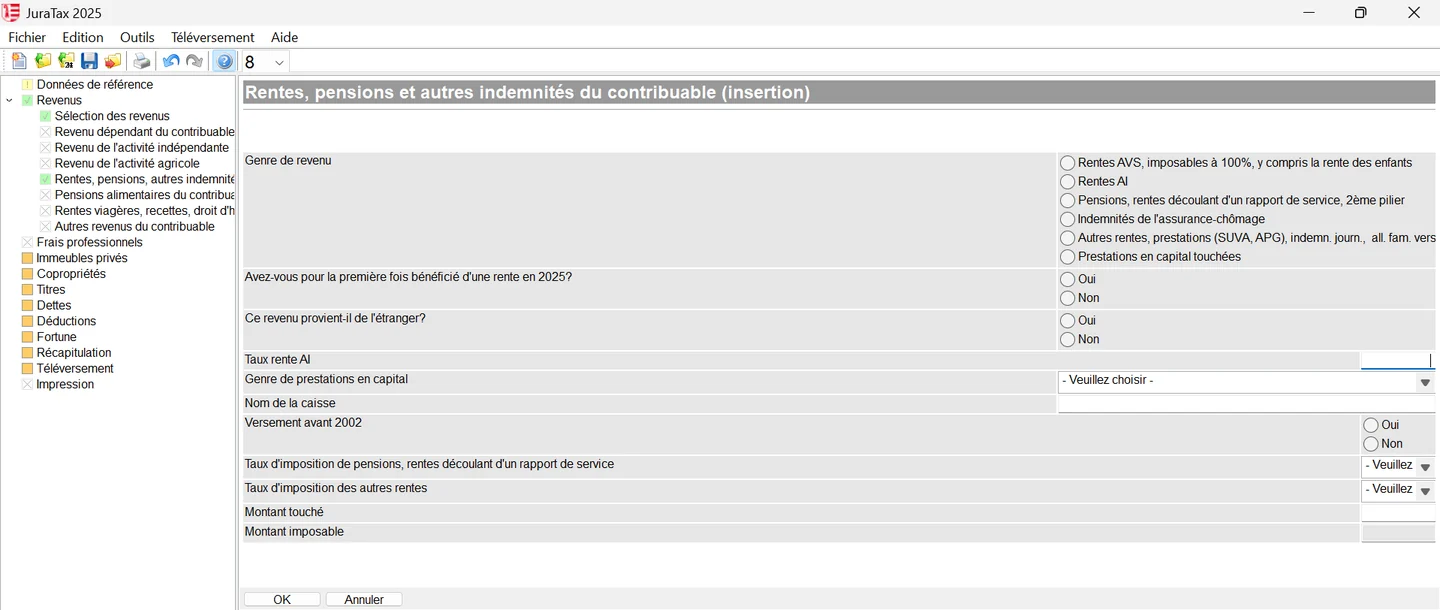
In JuraTax, each pension is entered with « Insérer » under « Rentes, pensions, autres indemnités »: type of income (AHV, disability, pillar 2, unemployment, other benefits or lump sums received, « prestations en capital touchées »), first pension in 2026, foreign source, disability rate, then the amount received (« Montant touché »). For a pillar 2 pension, JuraTax asks whether payments started before 2002 and the taxable rate (60%, 80% or 100%) and calculates the taxable amount.
Other income (code 400)
Code 400 covers any income not listed under codes 100 to 390, stating its type and with supporting documents: for example income from online sales or personal work. Not taxable: military and civil protection pay, compensation for moral damage, supplementary benefits, social assistance, inheritances, bequests and gifts, and payouts from surrenderable life insurance. Lottery winnings are declared in the securities list (see Accounts and securities).
Frequently asked questions
Which amount from the salary certificate goes into JuraTax?
The net salary in box 11, under code 100 (100C for your spouse). If a pension fund buy-in appears in box 10.2, add it to box 11 and deduct it under code 515.
Are family allowances taxable in Jura?
Yes. Paid by the employer, they are included in the net salary under code 100. Paid to someone not working, they are declared under code 240.
Where do I declare daily allowances in JuraTax?
Disability (AI) daily allowances under code 120. Others (sickness, accident, loss of earnings) under code 240. Unemployment benefits under code 230, with the fund's statement.
Is maintenance for a 19-year-old child taxable?
No. Maintenance paid to or for an adult child is taxable neither for the child nor for the receiving parent, and it is not deductible for the payer.
Rather hand it over?
NeoFidu prepares and files your Jura tax return for you, including property, undivided estates and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from the 2025 general guide (« Guide général ») of the Jura cantonal tax service (Service des contributions), its official forms and the Swiss Federal Tax Administration's Jura cantonal sheet (February 2026), which states that indexed amounts remain unchanged for the 2026 tax period. JuraTax is not available in English: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show JuraTax 2025 with fictitious data. If in doubt, the tax service's general guide prevails.