JuraTax · Chapter 8/11
Property in JuraTax: form 4, imputed rent, 10% or 20% flat rate and upkeep costs
Key points
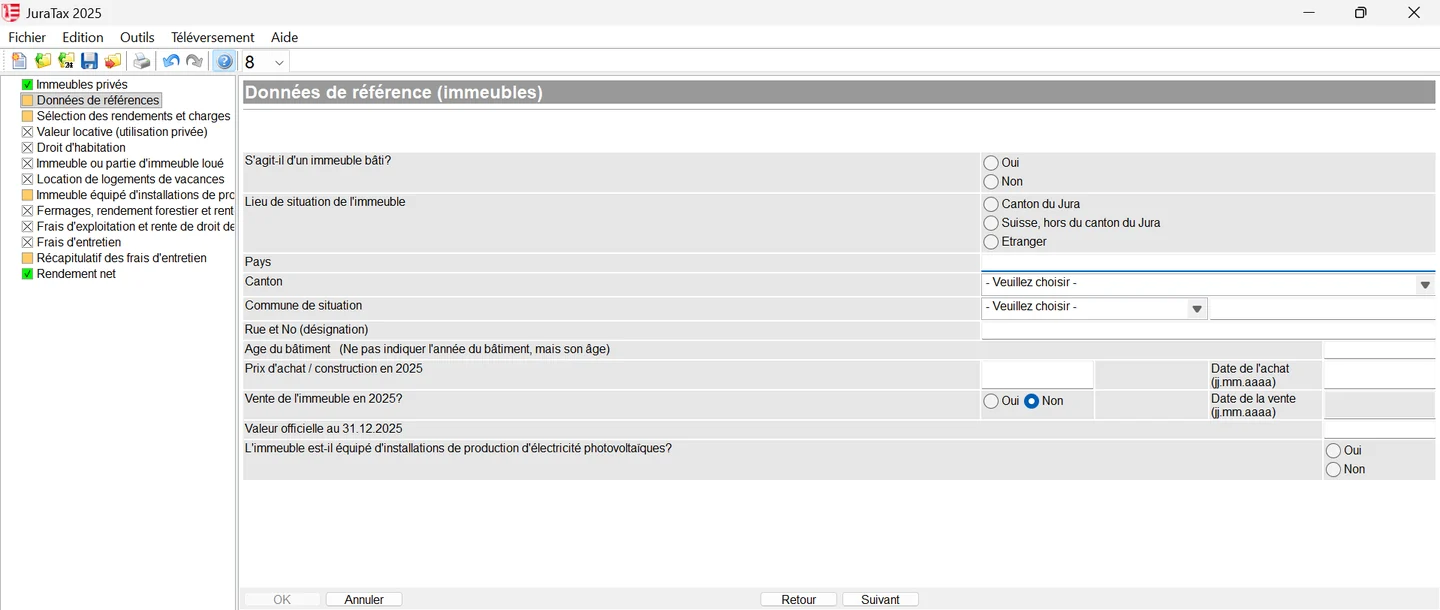
- Fill in one form 4 « Rendement immobilier » (property income) for each property. Net income goes to code 300, an excess of expenses to code 310.
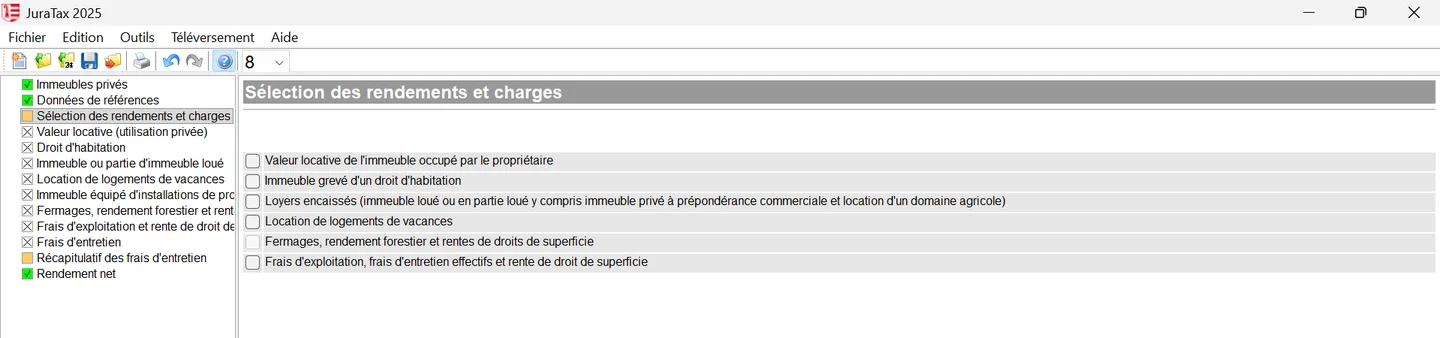
- Every year and for each property, choose between the flat rate (10% of gross income if the building is 10 years old or less, 20% otherwise) and actual costs by invoice date.
- With the flat rate, property tax (« taxe immobilière ») is no longer deductible; with actual costs, it is deductible on top.
- Jura property is declared at its official value (codes 700 and 702); property in another canton or abroad (892, 894) counts towards the rate.
Income: rent and imputed rent (form 4)
Property income includes rent actually received, excluding heating and hot water charges, farm leases and any other right of use. For a home you live in yourself, the imputed rent (« valeur locative ») is taxed. Property let at a favourable rent, for example to a relative, is taxed at least on the imputed rent. A reduction for under-use is only possible if part of the property is no longer used at all; a guest room, rooms left by children who moved out or a second home do not qualify.
| Code | What goes there |
|---|---|
| 300 | Net income from private property |
| 310 | Excess of expenses on private property (enclose all invoices) |
| 320, 330 | Net income or excess of expenses on business property |
| 700 | Official value of property in your municipality of residence |
| 702 | Official value of property in other Jura municipalities |
| 708, 710 | Business property, farm property of farmers |
| 892 | Property in other cantons, at the tax value set by that canton |
| 894 | Property abroad |
Flat rate or actual upkeep costs
| Option | Rule |
|---|---|
| Flat rate (code 4300) | 10% of gross rental income or imputed rent if the building is 10 years old or less at the end of the tax year, 20% otherwise. It covers all costs and insurance |
| Actual costs (code 4320) | Upkeep costs invoiced in 2026: the invoice date counts; advance payments are not deductible |
| Switching | You can choose freely every year and for each property |
| Exception | Private property let to third parties mainly for business use: actual costs only |
- Deductible: repairs, periodic refurbishment (painting, wallpaper, façades), renovations without added value, contributions to a condominium's renovation fund, upkeep of fixed outdoor fittings (fences).
- Not deductible: lawn mowing, pruning trees and hedges, snow clearing, vegetable gardens, work that adds value (removing a wall, adding windows, converting the attic, enlarging the heated volume), purchase or sale costs (transfer duties, brokerage).
- Property tax: no longer deductible on top of the flat rate. With actual costs, it remains deductible on top.
- Supporting documents: enclose copies of final invoices above CHF 1,000 if you deduct actual costs, and all invoices if you have an excess of expenses (code 310). Till receipts only count if they identify the purchase and the work.
Energy savings, solar panels and batteries
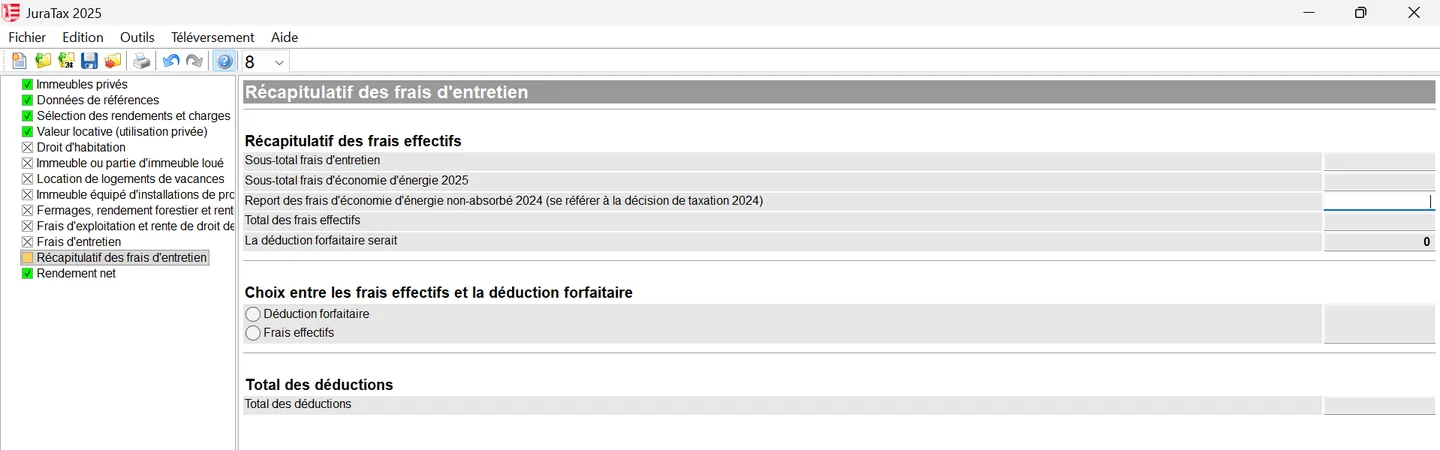
Investments that save energy or use renewable energy are in principle fully deductible, after subtracting subsidies: insulating the roof, façades or cellar ceiling, replacing fossil heating with a heat pump or wood heating, connecting to district heating, solar photovoltaic systems and, since 2024, the stationary batteries that complement them. They are not deductible when incurred during construction or within 2 years of construction, extension or a fundamental conversion. EV charging stations are not deductible. If these costs exceed your taxable income for the year, the unabsorbed part is carried forward to the following year: JuraTax has a line for it (« Report des frais d'économie d'énergie non absorbés »), taken from your last assessment.
Demolition costs for a replacement building are declared in the year they are invoiced, in the « économie d'énergie » (energy saving) column of form 4. If the new building is not completed within two years, the deduction is cancelled retroactively.
Holiday lets, usufruct, other cantons
- Letting a holiday home or rooms: income is taxable. A flat rate of 20% of receipts, up to CHF 3,000, covers overheads and wear. For the rest of the year, add the imputed rent pro rata.
- Usufruct: income and wealth from the property are declared by the usufructuary.
- Right of residence (« droit d'habitation »): the beneficiary declares its value under code 360. The owner reduces the official value by a multiple of the annual rent depending on the youngest beneficiary's age (20 up to age 30, 9 from 61 to 70, 4 above 80) and encloses a sheet with the beneficiaries' names and addresses.
- Sale or gift in 2026: declare income up to the transfer of ownership. The property gain is taxed separately.
- Property in another Jura municipality: nothing to do; your municipality of residence passes a flat share on to the municipality where it is located.
- Property in another canton or abroad: declare income and value; they are not taxed in Jura but count towards the rate. Enclose the deed for a purchase or sale in 2026.
Frequently asked questions
10% or 20% flat rate in Jura?
10% of gross income or imputed rent if the building is 10 years old or less at the end of the tax year, 20% if older. You can choose each year, for each property, between the flat rate and actual costs.
Is property tax (taxe immobilière) deductible in Jura?
Only if you deduct actual upkeep costs. With the flat rate, it is no longer deductible on top.
Are solar panels tax-deductible in Jura?
Yes, fully, on an existing private building and after subsidies, as are stationary batteries since 2024. They are not deductible if installed during construction or within the following two years. Electricity sales are taxable (code 4180).
Do I declare a flat in France or in another canton?
Yes. Its income and value are not taxed in Jura, but they are used to set your tax rate. Use codes 892 (other canton) or 894 (abroad).
Rather hand it over?
NeoFidu prepares and files your Jura tax return for you, including property, undivided estates and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from the 2025 general guide (« Guide général ») of the Jura cantonal tax service (Service des contributions), its official forms and the Swiss Federal Tax Administration's Jura cantonal sheet (February 2026), which states that indexed amounts remain unchanged for the 2026 tax period. JuraTax is not available in English: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show JuraTax 2025 with fictitious data. If in doubt, the tax service's general guide prevails.