JuraTax · Chapter 9/11
Deductions in JuraTax: insurance premiums (525), childcare, medical costs, donations and personal deductions
Key points
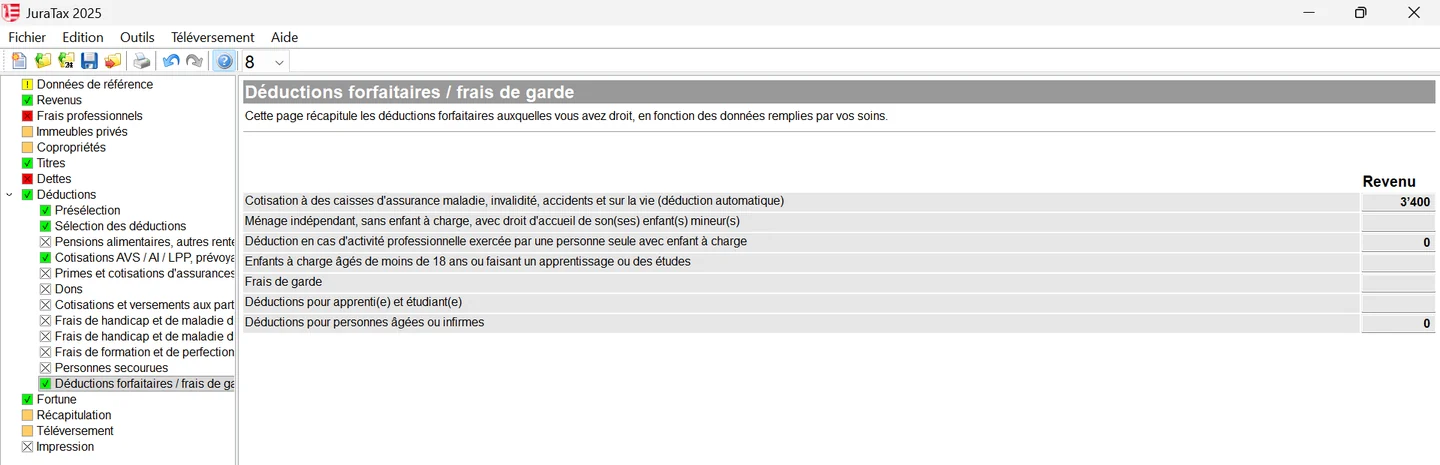
- Insurance premiums (code 525): up to CHF 6,800 for a married couple and CHF 3,400 for others, plus CHF 1,020 per child and CHF 790 per person with neither pillar 2 nor pillar 3a. The ECAS premium reduction is subtracted.
- Childcare (code 555): up to CHF 10,600 per child under 14, if both parents or the single parent work.
- Medical costs (570 to 580): the portion above 5% of net income I. Donations (585): up to 10% of net income I, including local sports and cultural clubs.
- Child deduction (620): CHF 5,700, or CHF 6,400 for each child from three children. Married couple (680): CHF 3,700.
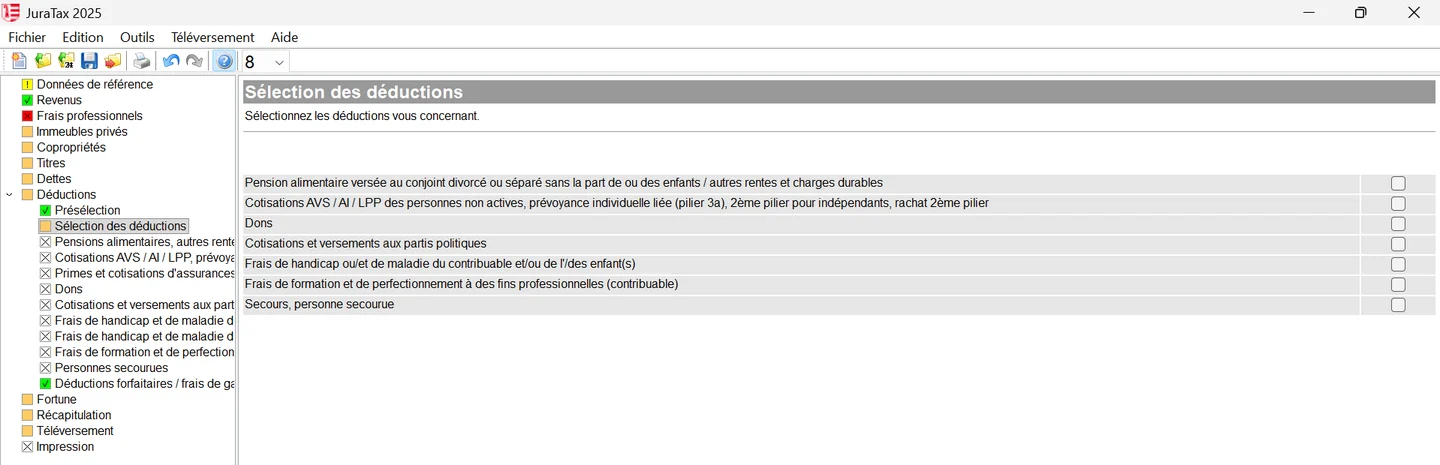
In JuraTax, the « Déductions » section starts with a selection (« Sélection des déductions »): maintenance paid, pension contributions (pillar 3a, pension fund buy-in), donations, political parties, disability or medical costs, training, supported persons. Insurance premiums and flat-rate deductions have their own screens in the same section.
Insurance premiums and savings interest (codes 5250 to 525)
| Code | Amount to enter |
|---|---|
| 5250 | Gross health and accident insurance premiums billed for 2026 (enclose the 2026 policy) |
| 5252 | Minus the premium reduction granted by the cantonal social insurance office (ECAS) for 2026 |
| 5254 | Life and annuity insurance premiums (enclose the policy or statements) |
| 5256 | Interest on savings: bank, bond and loan interest (not dividends or funds) |
| 5259 then 525 | Total, capped at the maximum below |
| Situation | Maximum 2026 |
|---|---|
| Married couple, both spouses pay into pillar 2 or pillar 3a | CHF 6,800 |
| Married couple, only one spouse pays in | CHF 7,590 |
| Married couple, neither pays in (for example two retirees) | CHF 8,380 |
| Single person paying into pillar 2 or pillar 3a | CHF 3,400 |
| Single person not paying in | CHF 4,190 |
| Plus, per dependent child up to 18 | CHF 1,020 |
| Plus, per dependent young adult aged 18 to 25 in training | CHF 3,400 (not combined with the CHF 1,020) |
Maintenance, political parties, training, disability
| Code | Deduction | 2026 rule |
|---|---|---|
| 540, 545 | Maintenance paid to a former spouse and for minor children, annuities and permanent charges | Amount paid, with judgment or agreement and receipts; not for an adult child or a one-off payment |
| 548 | Membership fees and donations to a political party | max. CHF 10,600, if the party is on the federal register, represented in the Jura Parliament or won at least 3% of the vote |
| 549 | Vocational training, further training and retraining (form 11) | max. CHF 12,000, after a first upper-secondary diploma or from age 20 |
| 550 | Disability-related costs (form 9) | In principle in full; proof from CHF 1,000 |
Childcare costs (code 555)
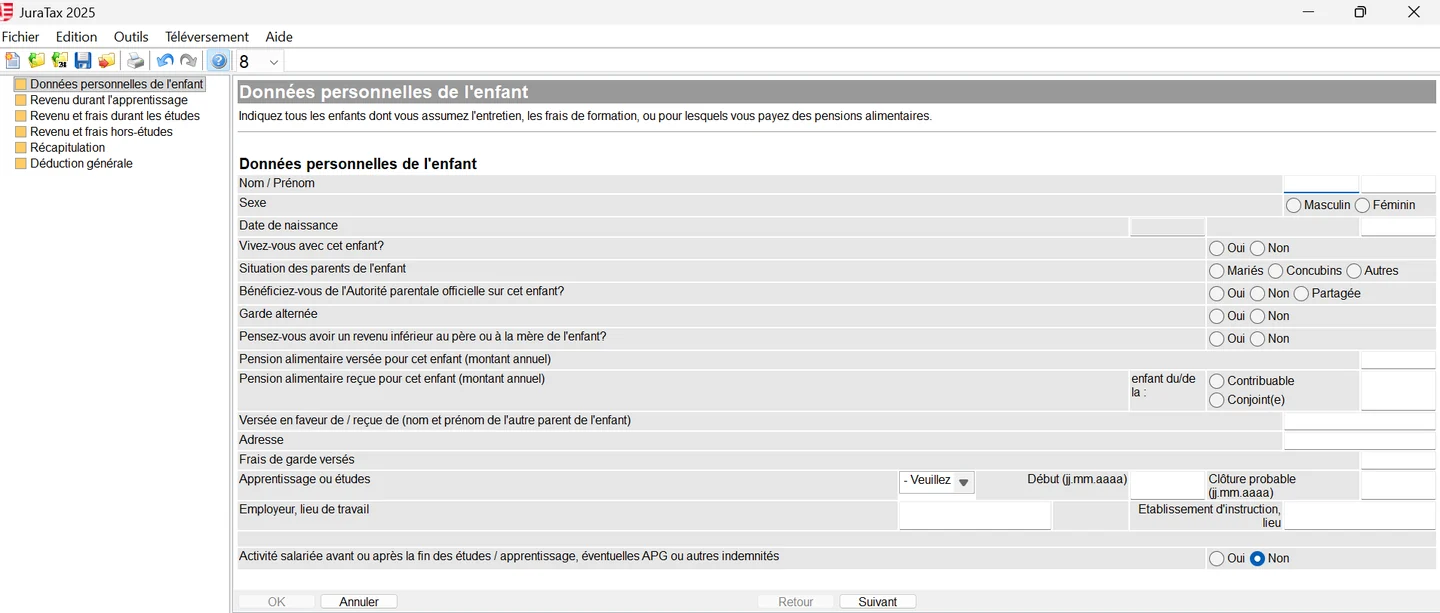
Third-party childcare (nursery, after-school care, childminder) is deductible up to CHF 10,600 per child, until the child's 14th birthday, if both married parents work, if the single parent works (and, if the household has two adults, both work), or if care is needed because of serious illness or disability. Enclose the cost certificate with the provider's name. Travel and meal costs are not deductible. In JuraTax, the costs are entered in each child's record, field « Frais de garde versés » (childcare costs paid). For federal tax, the cap is CHF 25,800 per child (2025).
Medical costs and donations (codes 570 to 585)
Medical and accident costs you paid yourself, for yourself or a dependant, are itemised on form 9 (code 570). Only the portion above 5% of net income I (code 560) is deductible. Example: net income I of CHF 32,400 and costs of CHF 4,800; 5% is CHF 1,620, so the deduction is CHF 3,180. Enclose invoices and health insurer statements if costs exceed CHF 1,000.
Donations (code 585) are deductible up to 10% of net income I if they go to Swiss legal entities exempt for public-interest purposes, and to local or regional sports or cultural clubs. If the total exceeds CHF 1,500, enclose proof for donations above CHF 500. For federal tax, donations count from CHF 100 and up to 20% of net income, but only to legal entities exempt for public-interest purposes.
Personal deductions (codes 600 to 680)
| Code | Deduction | 2026 amount |
|---|---|---|
| 600 | Divorced or separated person living alone, no dependent child, with visiting rights for minor children | CHF 1,800 |
| 610 | Working single parent with a dependent child | max. CHF 2,700 |
| 620 | Dependent child under 18, or in an apprenticeship or studying | CHF 5,700; from 3 children, CHF 6,400 per child (3 children: CHF 19,200) |
| 630 | Supplement for a child educated away from home, with room and board (not for public compulsory school) | max. CHF 10,600; only one meal away: CHF 3,000 plus travel up to CHF 2,700 |
| 640 | Supported person unable to support themselves | CHF 2,400, if your support reaches at least this amount |
| 660 | Apprentice or student, in their own return | CHF 4,100 |
| 670 | AHV or disability pensioner on a modest income | Per a scale: up to CHF 8,900 (one pension) or CHF 10,300 (two pensions) |
| 680 | Married couple or registered partners living together | CHF 3,700 |
- Code 620: the deduction is not granted if the child's annual income, grants included, exceeds CHF 19,800.
- Code 630: education costs must be at least CHF 1,000. The full deduction remains with a grant of up to CHF 8,000 a year; it drops to CHF 5,300 between CHF 8,001 and CHF 11,000 and disappears above that.
- Code 660: studies must take up most of the student's resources; as soon as work exceeds one-third time, the deduction is lost. It does not exist for federal tax.
- Code 670: the qualifying income starts from net income II (code 590), plus certain excess expenses and 3% of taxable wealth above CHF 114,000 (couple) or CHF 57,000 (single). JuraTax applies the guide's scale.
Frequently asked questions
How much health insurance can I deduct in Jura in 2026?
Up to CHF 6,800 for a married couple and CHF 3,400 for a single person, plus CHF 1,020 per child and CHF 790 per person paying into neither pillar 2 nor pillar 3a. The ECAS premium reduction is subtracted from gross premiums.
How much is the child deduction in the canton of Jura?
CHF 5,700 per child. From three children, the deduction rises to CHF 6,400 for each child, i.e. CHF 19,200 for three children. It goes under code 620.
Where do I enter nursery costs in JuraTax?
Under « Données de référence », « Enfants à charge » (reference data, dependent children), in each child's record. They are deductible up to CHF 10,600 per child under 14, under code 555.
Can I deduct a donation to the village football club?
Yes, for cantonal tax: donations to local or regional sports or cultural clubs are deductible, with other donations, up to 10% of net income I. For direct federal tax, only donations to legal entities exempt for public-interest purposes count.
Rather hand it over?
NeoFidu prepares and files your Jura tax return for you, including property, undivided estates and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from the 2025 general guide (« Guide général ») of the Jura cantonal tax service (Service des contributions), its official forms and the Swiss Federal Tax Administration's Jura cantonal sheet (February 2026), which states that indexed amounts remain unchanged for the 2026 tax period. JuraTax is not available in English: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show JuraTax 2025 with fictitious data. If in doubt, the tax service's general guide prevails.