JuraTax · Chapter 5/11
Retirement savings in JuraTax: pillar 3a (520), 3a catch-up, pension fund buy-ins (515) and lump sums (905)
Key points
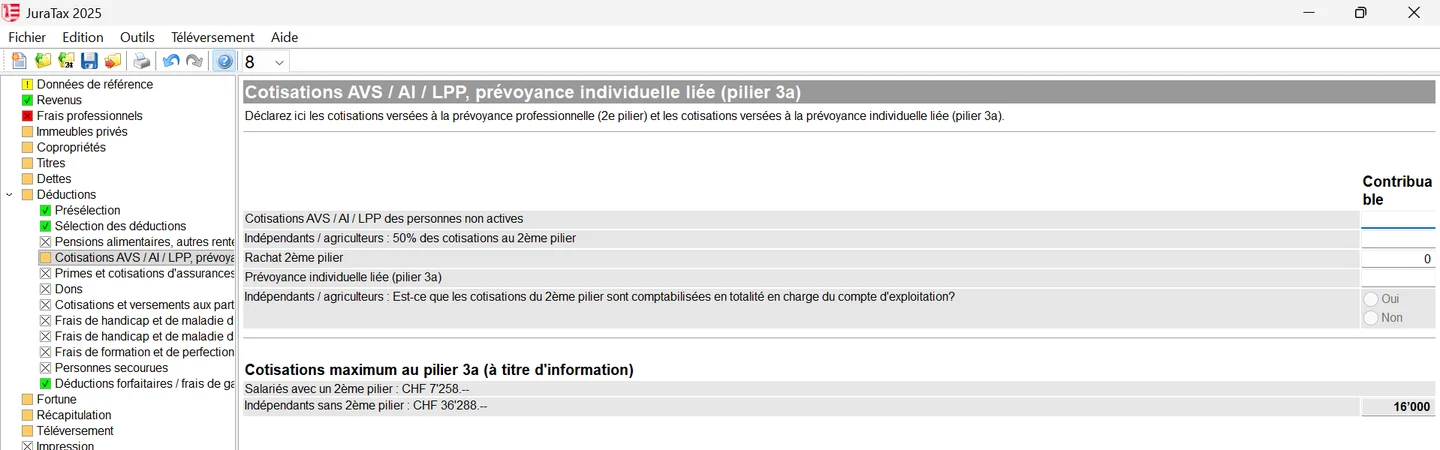
- Pillar 3a: codes 520 / 520C, up to CHF 7,258 with a pension fund, or 20% of earned income up to CHF 36,288 without pillar 2. Enclose the official certificate.
- New in 2026: 3a contributions missed in 2025 can be bought back and deducted for the first time. Gaps from before 2025 cannot be filled.
- Pension fund buy-ins: codes 515 / 515C, with the payment certificate and the maximum buy-in calculation. No lump-sum withdrawal for 3 years, otherwise the deduction is refused.
- A pension lump sum (pillar 2, pillar 3a) is declared under code 905: it is taxed separately, at a reduced rate, with no personal deductions.
Pillar 3a (codes 520 and 520C)
| Situation | Maximum deduction 2026 |
|---|---|
| Member of a pension fund (pillar 2) | CHF 7,258 |
| No pillar 2 (self-employed, for example) | 20% of earned income, max. CHF 36,288 |
In JuraTax, first tick the deduction in the list of deductions (« sélection des déductions »), then enter the contributions paid for the year. Each spouse has their own cap: the taxpayer under code 520, the spouse under 520C. Only amounts actually paid in 2026 count, up to the legal cap. Enclose the official certificate from the bank or insurer: it appears in the list of supporting documents JuraTax produces at the end.
Pension fund buy-ins (codes 515 and 515C)
Buy-ins of insurance years in pillar 2 are deductible, for employees and the self-employed alike, on presentation of the maximum buy-in calculation and the fund's payment certificate. Do not subtract the buy-in from the salary under code 100: it is deducted only under code 515. The self-employed also deduct 50% of their personal pillar 2 contributions there.
AHV contributions of people not working (codes 510 and 510C)
People not gainfully employed (early retirees, non-working spouses in some cases, students from age 21) deduct under code 510 the AHV/IV/EO contributions they pay themselves, as well as their pension fund contributions. Enclose proof if AHV contributions exceed CHF 1,000.
Lump-sum withdrawal (codes 905 and 905C)
If you received a pillar 2 or pillar 3a lump sum in 2026, declare it under code 905 (905C for your spouse). In JuraTax, it is entered under « Revenus », « Rentes, pensions, autres indemnités », type of income « Prestations en capital touchées » (lump sums received), with the type of benefit and the fund's name. The lump sum is not added to your other income: it is taxed separately, in the year you become entitled to it, with no personal deductions.
| Portion of the lump sum | Couple or single parent | Other taxpayers |
|---|---|---|
| First CHF 56,700 | 0.9% | 1.1% |
| Next CHF 56,700 | 1.1% | 1.3% |
| Above | 1.3% | 1.7% |
The tax service offers a lump-sum benefit calculator on the virtual counter to estimate the tax before a withdrawal. The lump sum itself only appears in your wealth on 31 December as the accounts or investments where it was paid.
Frequently asked questions
How much pillar 3a can I deduct in 2026 in Jura?
CHF 7,258 if you belong to a pension fund, or 20% of your earned income up to CHF 36,288 without pillar 2. The deduction goes under codes 520 and 520C of the return.
Can I buy back missed pillar 3a years?
Yes, from 2026, but only for gaps arising from 2025 onwards. It requires the year's full ordinary contribution to have been paid and is deductible. Gaps from before 2025 cannot be bought back.
Where do I declare a pillar 2 withdrawal in JuraTax?
Under code 905 (905C for your spouse), ticking the pillar 2 box. The lump sum is taxed separately, at a reduced rate, with no personal deductions; you receive a separate decision.
Is a pension fund buy-in deductible if I retire with a lump sum two years later?
No. The deduction is refused if a lump-sum benefit is paid in the three years following the buy-in, for whatever reason.
Rather hand it over?
NeoFidu prepares and files your Jura tax return for you, including property, undivided estates and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from the 2025 general guide (« Guide général ») of the Jura cantonal tax service (Service des contributions), its official forms and the Swiss Federal Tax Administration's Jura cantonal sheet (February 2026), which states that indexed amounts remain unchanged for the 2026 tax period. JuraTax is not available in English: we quote the French labels, followed by a translation, so you can find them on screen. Screenshots show JuraTax 2025 with fictitious data. If in doubt, the tax service's general guide prevails.