Clic&Tax · Chapter 6/11
Accounts and securities in Clic&Tax: annex 1, price list, withholding tax and lottery winnings (item 3.1)
Key points
- All your accounts and securities, and those of your spouse and minor children, are declared on annex 1, the securities list (« état des titres »), with their value on 31 December 2026 and their income. The total goes in item 3.1.
- Income subject to withholding tax (column 8) gives a refund of the 35% withheld; other income goes in column 9. Interest on accounts closed once a year up to CHF 200 is free of withholding tax.
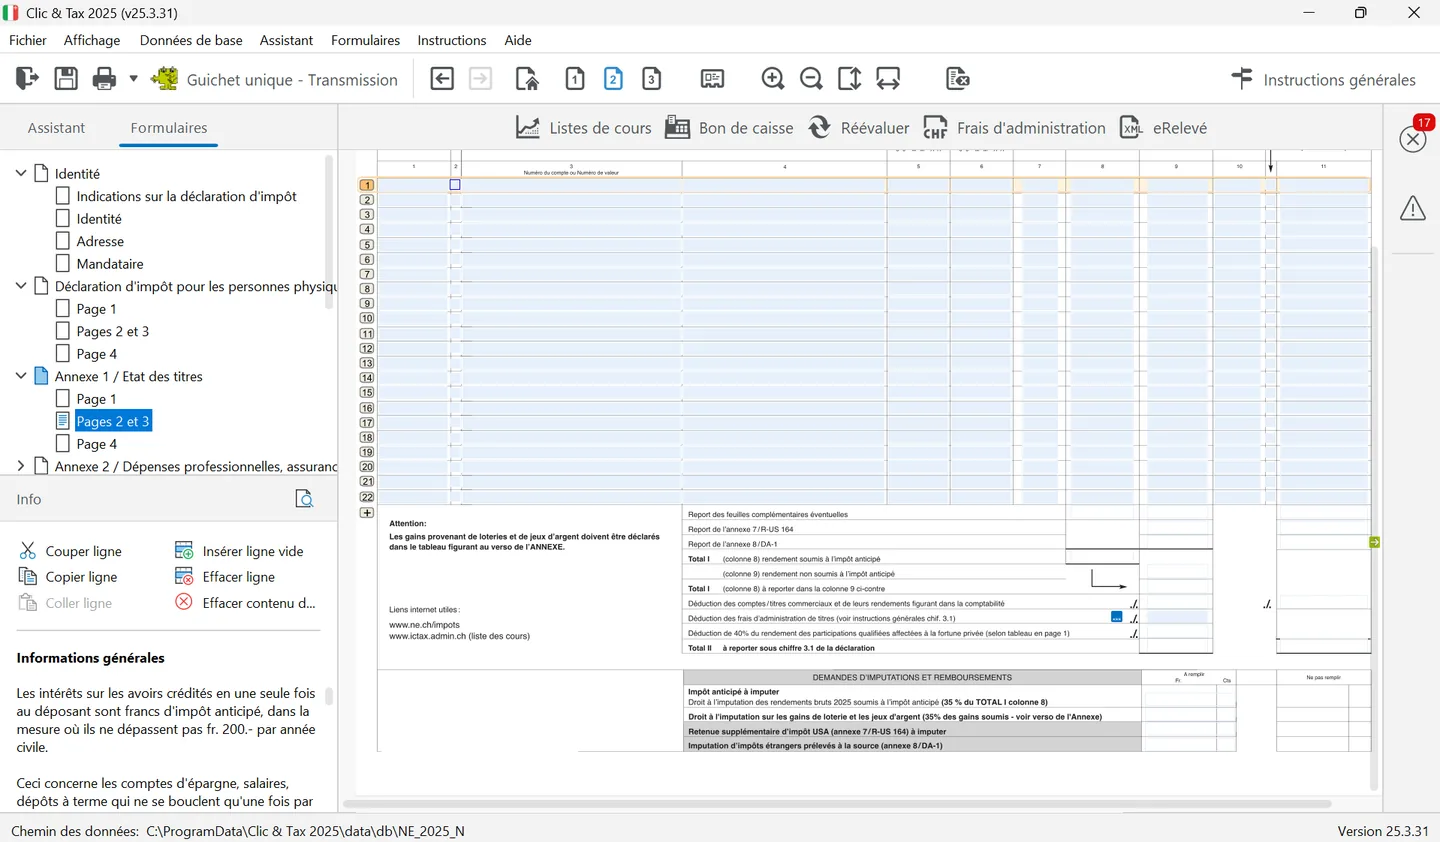
- The « Listes de cours » (price lists) and « Bon de caisse » (medium-term notes) buttons download the official tax values, « Réévaluer » (revalue) updates a list carried over from last year and « eRelevé » imports your bank's electronic tax statement.
- Management costs: flat rate of 2‰ of the value of securities managed by a bank. Dividends from holdings of at least 10%: taxed at 60% (70% for federal tax).
Annex 1: the securities list
Annex 1, « État des titres, livrets d'épargne et autres placements de capitaux et demande d'imputation » (securities, savings and other investments, and refund claim), lists all investments: salary, savings and postal accounts, fixed-term deposits, bonds, shares, shares in limited companies and cooperatives, Swiss and foreign investment funds, mortgage-backed claims, premium deposits with insurers, condominium renovation funds. It also serves as your withholding tax refund claim. The wealth and income of your minor children are added to yours. With Clic&Tax, annex 1 is the only printed annex to return with the paper return.
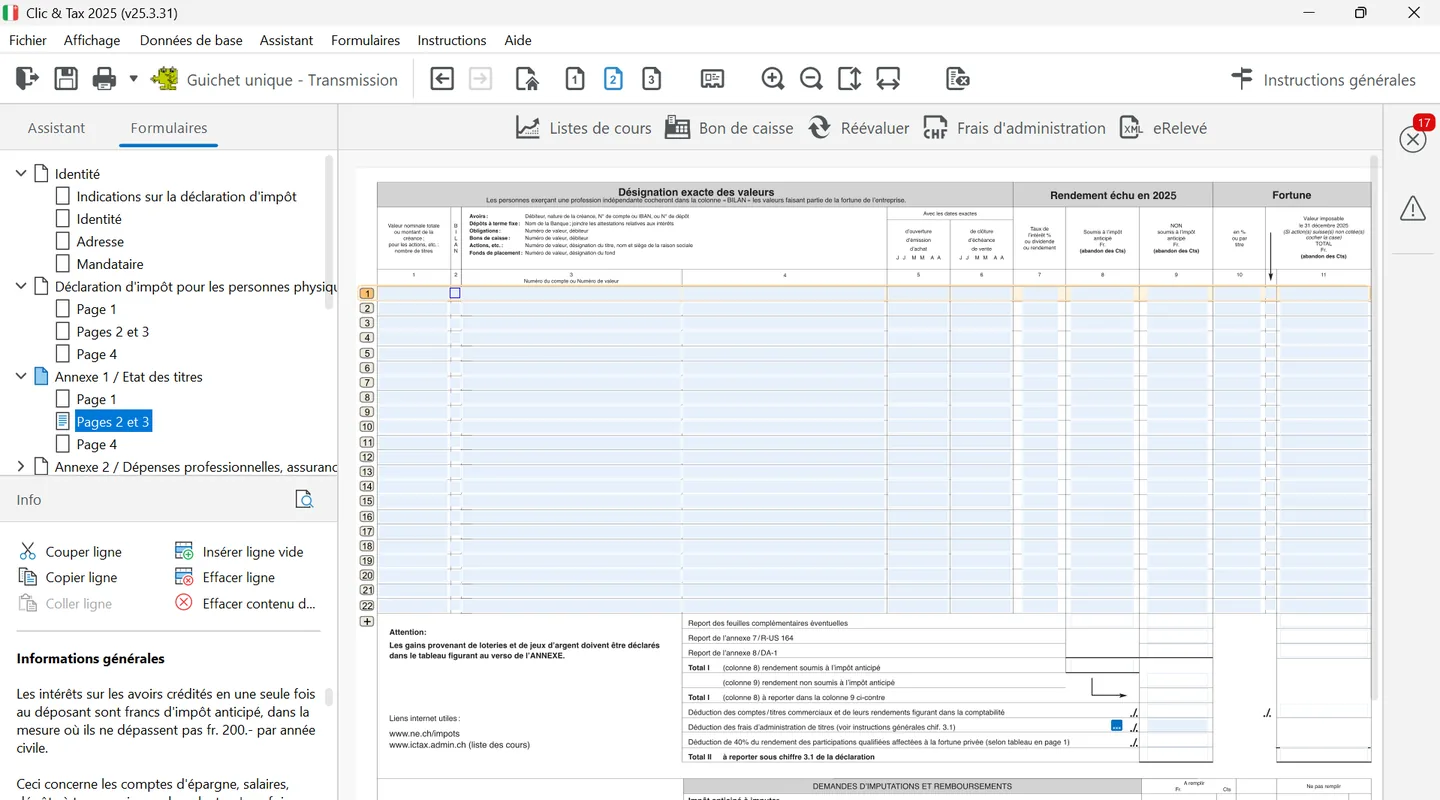
| Column | Content |
|---|---|
| 1 | Nominal value, amount of the claim or number of securities |
| 2 | « BILAN »: ticked by the self-employed for business assets |
| 3 and 4 | Account number (IBAN) or security number, description of the security or account |
| 5 and 6 | Opening, issue or purchase date and closing, maturity or sale date |
| 7 | Interest rate or dividend |
| 8 | Gross income subject to withholding tax |
| 9 | Income not subject to withholding tax (foreign securities, small interest) |
| 10 | Price in % or per security |
| 11 | Taxable value on 31 December 2026; tick the box for an unlisted Swiss share |
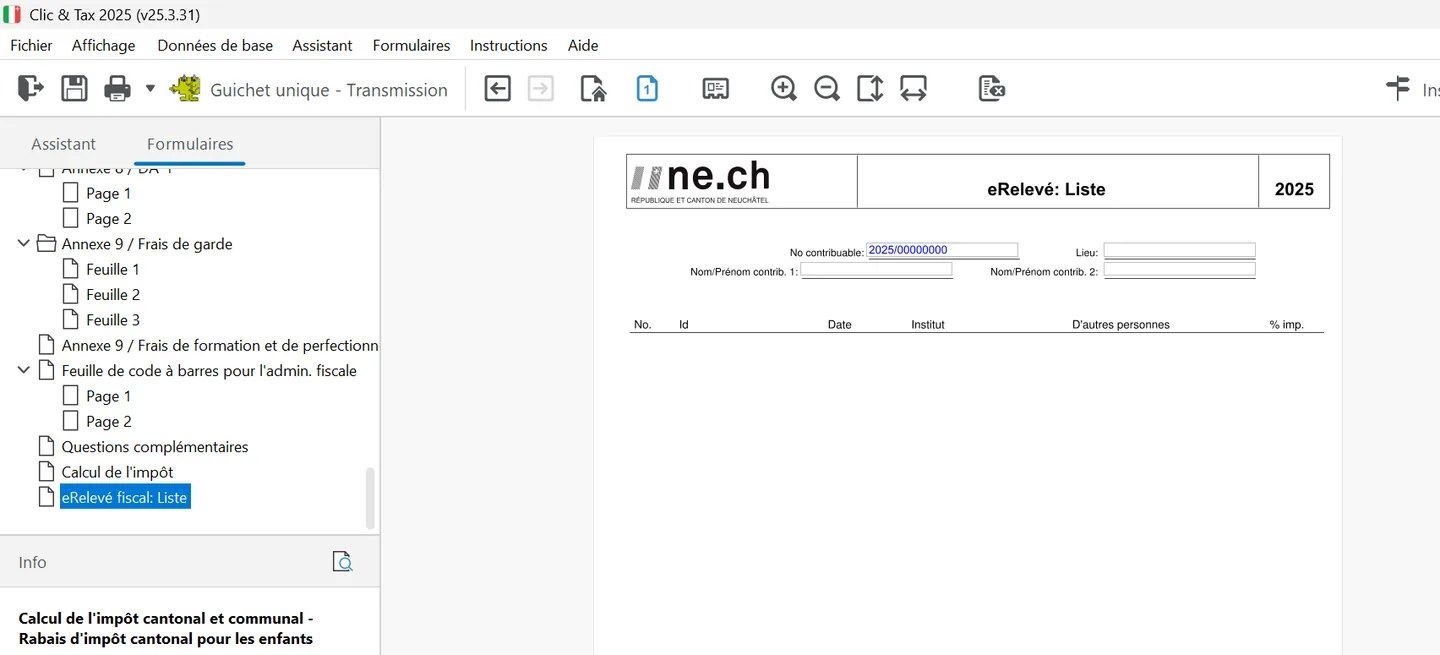
The « eRelevé fiscal: Liste » page, at the end of the tree, sums up the electronic statements imported: number, identifier, date, institution, other persons concerned and percentage.
The price list and the value of securities
Listed securities are valued at the price on 31 December 2026, published by the Federal Tax Administration in its price list (ictax.admin.ch). As the list is not ready when Clic&Tax is installed, click « Listes de cours » (or « Bon de caisse » for medium-term notes), at the top of annex 1 « Pages 2 et 3 », to download it. If you used the price list last year, the securities list is pre-filled (number, security number, name, rate, unit value): click « Réévaluer » to update the 2026 income and the value on 31 December. The « Frais d'administration » button, or the « ... » button on the « Déduction des frais d'administration de titres » line, opens a list to detail these costs.
| Item | Neuchâtel rule |
|---|---|
| Securities administration costs | Custody fees, safe rental, collection and affidavit fees, salary account fees; flat rate of 2‰ of the value of securities managed by a bank allowed |
| Not deductible | Purchase and sale commissions, stamp duty, asset management or advisory fees, tax return fees |
| Qualifying holding (at least 10% of capital) in private assets | Dividends taxed at 60% (70% for federal tax): fill in the table on page 1 of annex 1 and deduct 40% of the gross income |
| Unlisted Swiss shares | 60% reduction of the tax value for wealth tax (item 9), the full value still counting for the rate |
| Foreign tax withheld at source | Form DA-1 (annex 8); additional US withholding: form R-US 164 (annex 7) |
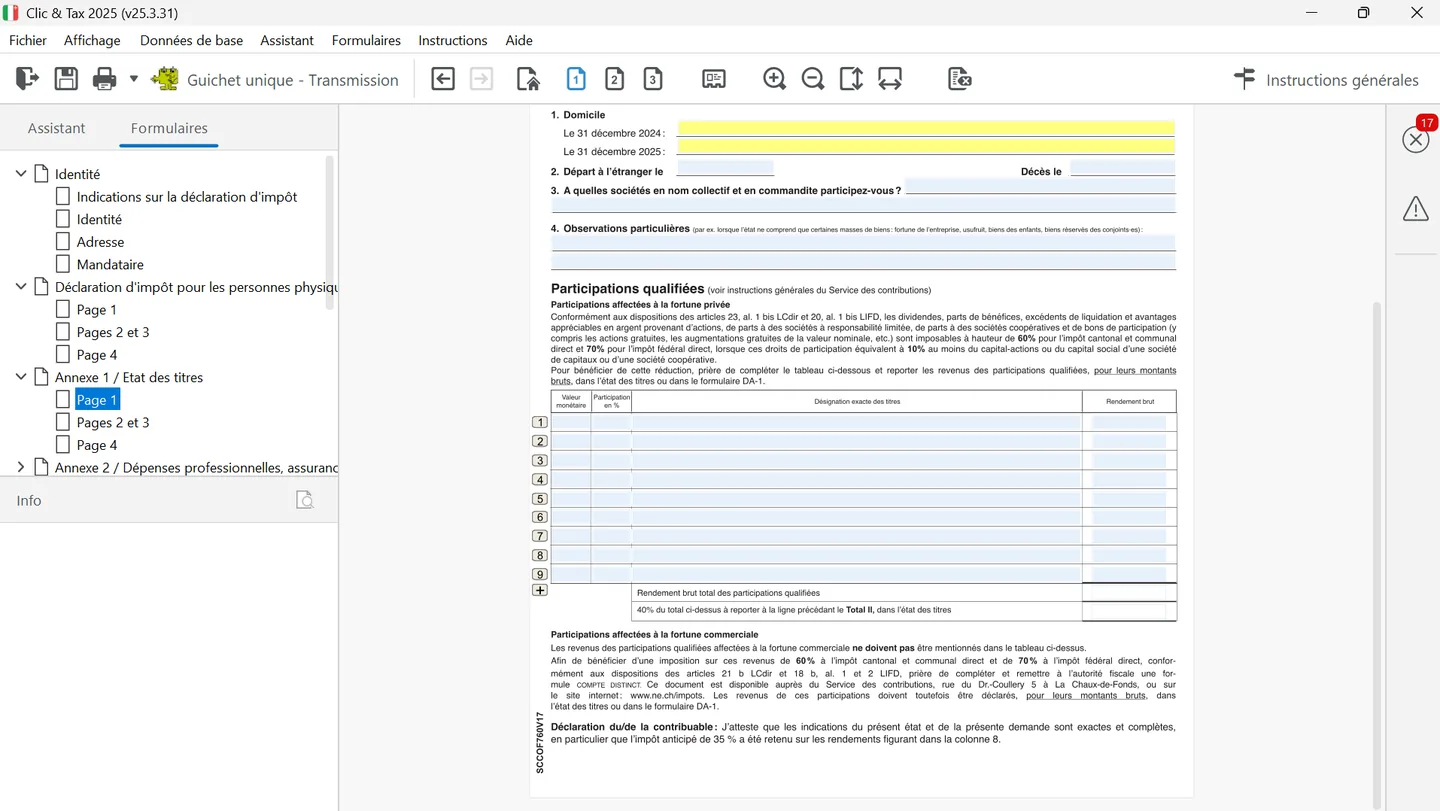
Annex 1 « Page 1 » also asks for your domicile on 31 December (filled in automatically), any date of departure abroad or death, the general or limited partnerships you belong to, and holds the qualifying holdings table for private assets: value, percentage held, description and gross income. Clic&Tax calculates the 40% to deduct and carries it to the line before Total II of the securities list.
Foreign taxes: annexes 8 (DA-1) and 7 (R-US 164)
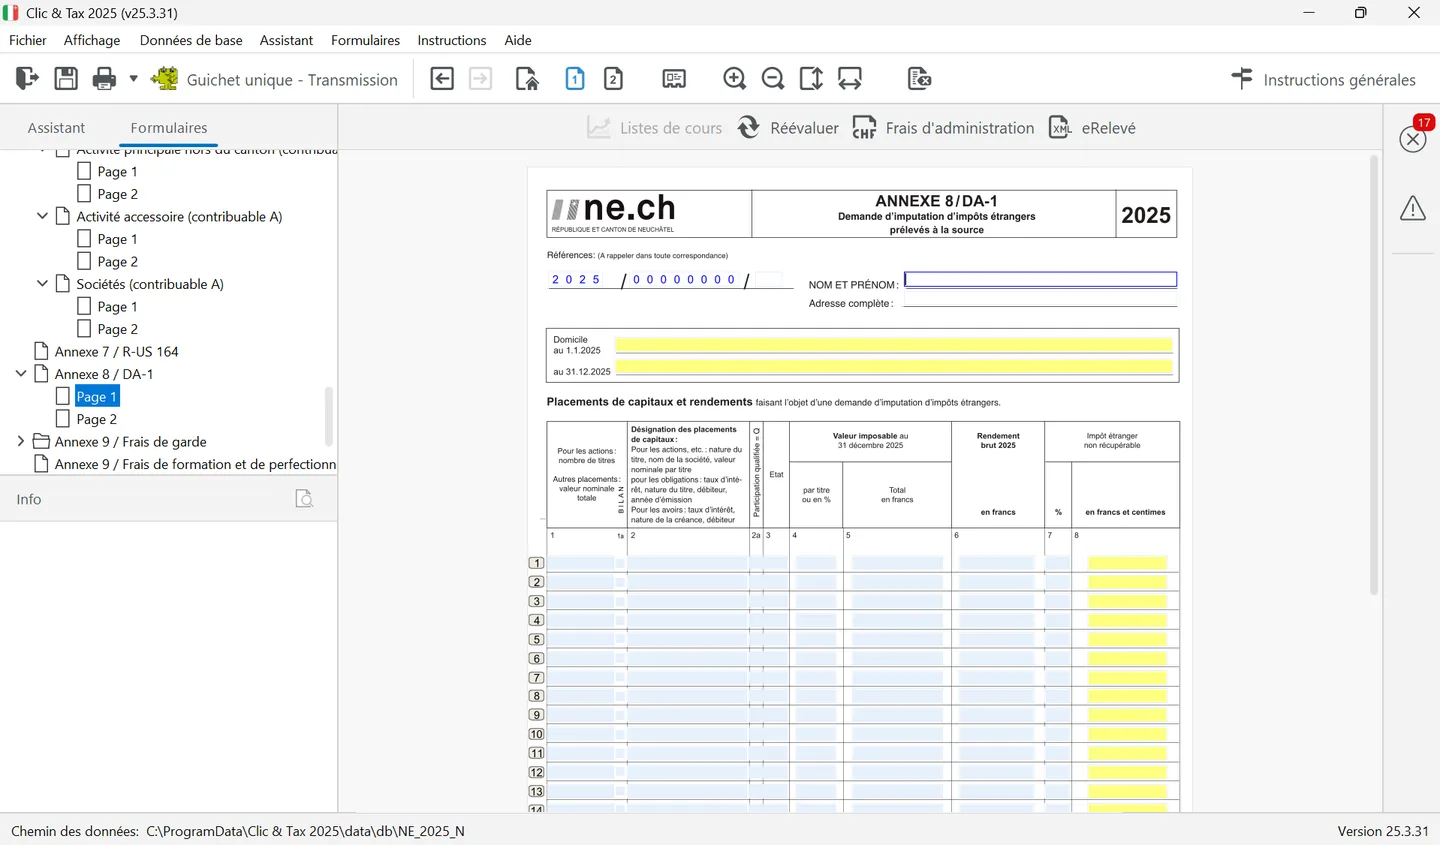
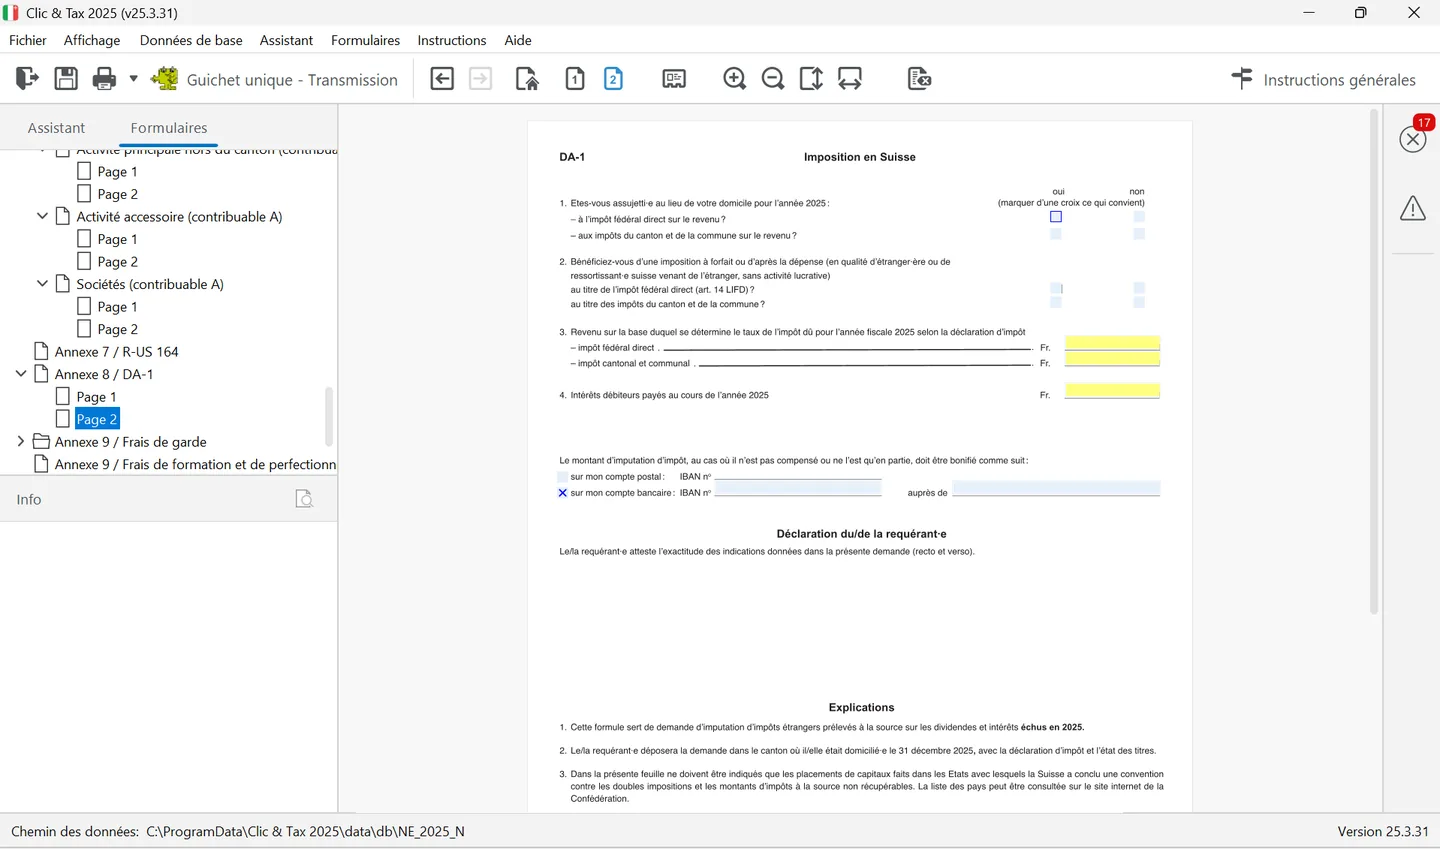
Foreign dividends and interest are often taxed at source in the country of origin. The part that cannot be recovered from that country can be credited in Switzerland with annex 8 / DA-1 (« Annexe 8 / DA-1 »), only for investments in a country that has a double taxation agreement with Switzerland. Group the securities by country (abbreviation in column 3) and give for each the taxable value on 31 December, gross income, rate and non-recoverable foreign tax. The totals go to annex 1: taxable value in column 12, gross income in column 10, non-recoverable foreign taxes under « Imputation d'impôts étrangers prélevés à la source ».
Page 2 asks whether you are liable to income tax at your place of domicile, whether you are taxed on expenditure, the income that sets your rate (federal and cantonal), debt interest paid, and the IBAN to which any credit not offset should be paid. Attach the bank statements. For licence royalties, the form is the DA-3.
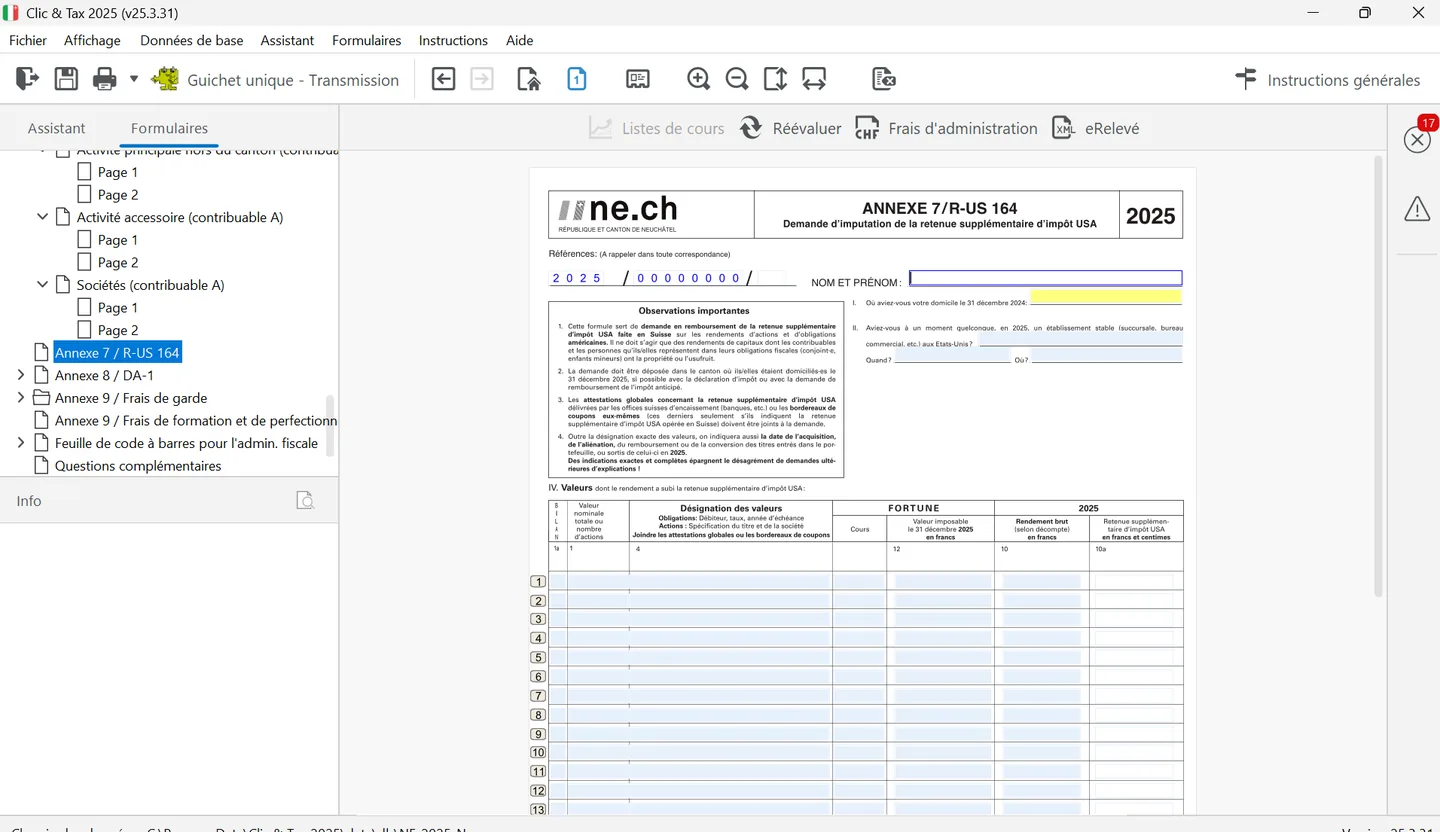
US securities held with a Swiss bank may be subject to an additional US withholding tax. It is reclaimed with annex 7 / R-US 164 (« Annexe 7 / R-US 164 »), with the bank's summary statements or coupon slips attached. Total I (additional withholding) goes to annex 1 under « Demandes d'imputations et remboursements », Total II to columns 12 (taxable value) and 10 (gross income). US dividends already declared on the R-US 164 are subtracted from the DA-1 totals.
Lottery and gambling winnings
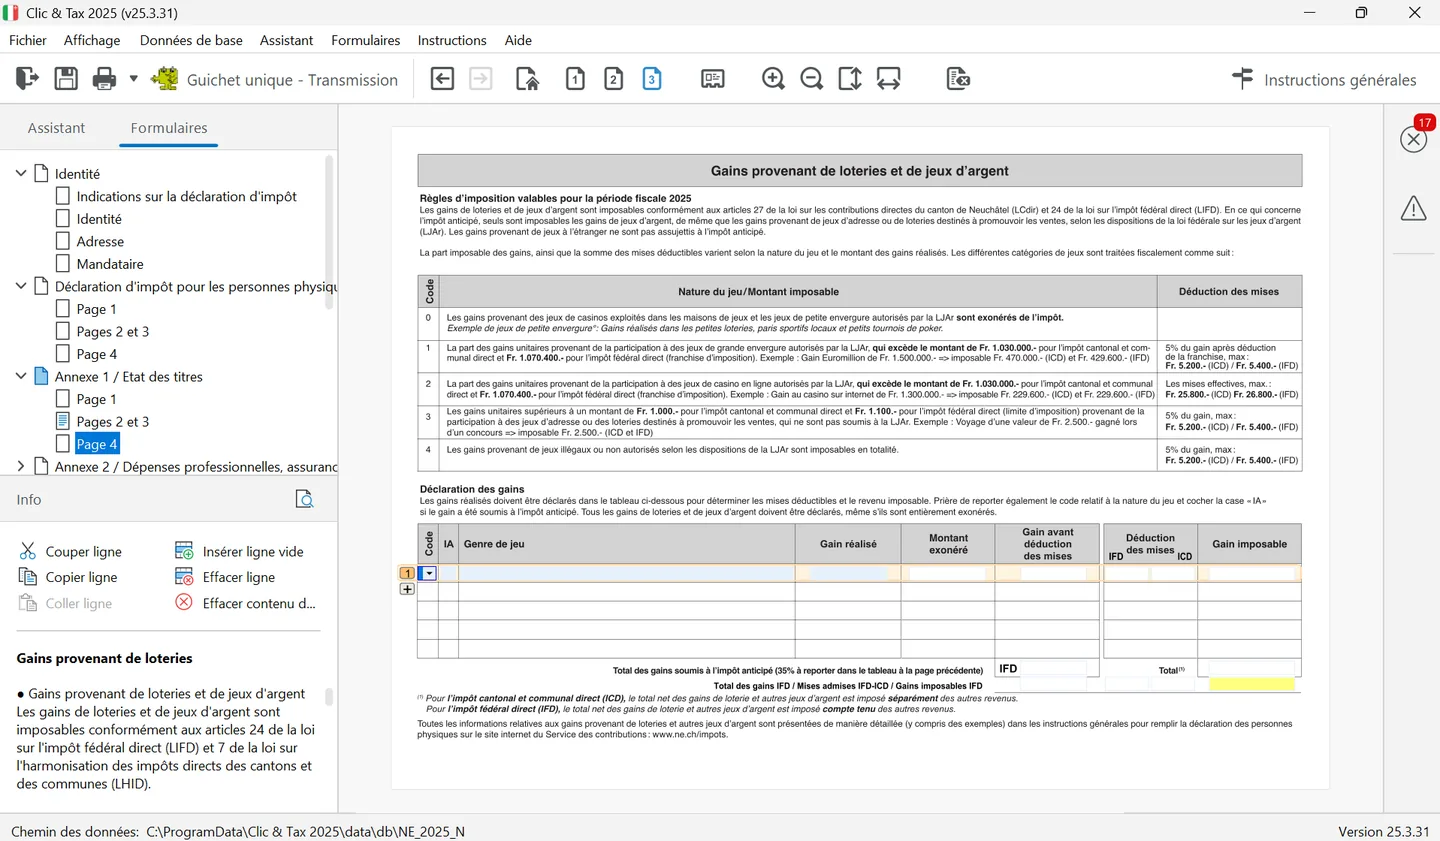
All winnings must be declared on the back of annex 1, even if exempt, with the code for the type of game and the « IA » box if withholding tax was deducted. Attach the original certificates: they are the only originals to send. For cantonal and municipal tax, taxable winnings are taxed separately from other income, at a 10% basic rate.
| Type of game | Taxation (cantonal / federal) |
|---|---|
| Swiss casinos and small-scale games (small lotteries, local poker tournaments) | Exempt |
| Large lotteries and betting (Swisslos, Loterie romande, Euro Millions) and authorised online casinos | Taxable above CHF 1,030,000 per win (CHF 1,070,400 for federal tax) |
| Competitions and promotional lotteries | Taxable above CHF 1,000 per win (CHF 1,100 for federal tax) |
| Illegal or unauthorised games | Fully taxable |
| Deductible stakes | 5% of the win, max. CHF 5,200 (CHF 5,400 federal); online casino: actual stakes, max. CHF 25,800 (CHF 26,800 federal) |
Cash, precious metals and undivided estates
Cash, banknotes, gold and precious stones are declared in item 3.2; its « ... » button opens a table (description, tax value). If you belong to an undivided estate, declare your share of its net wealth and income in item 3.3 and complete question 6 of the additional information. Cryptocurrencies are declared like other investments in the securities list; the Federal Tax Administration publishes their 31 December rate in its price list.
At the bottom of the securities list, the « Demandes d'imputations et remboursements » (credit and refund claims) box calculates the withholding tax to credit (35% of Total I in column 8 and 35% of lottery winnings subject to it), plus the amounts from forms R-US 164 and DA-1. Total II is carried to item 3.1. Next, move on to wealth and debts.
Frequently asked questions
Where do I find the tax value of my securities for Clic&Tax?
In the Federal Tax Administration's price list, which Clic&Tax downloads with the « Listes de cours » button in annex 1. It is also available on ictax.admin.ch.
Can I deduct bank fees for managing securities in Neuchâtel?
Yes, ordinary administration costs (custody fees, safe, collection), or a flat rate of 2‰ of the value of securities managed by a bank. Purchase and sale commissions and asset management fees are not deductible.
Do I have to declare an exempt lottery win?
Yes. All lottery and gambling winnings are declared on the back of annex 1, even if exempt, with the original certificates. Winnings from large lotteries are only taxable above CHF 1,030,000 per win for cantonal tax.
How do I recover withholding tax in Neuchâtel?
By declaring income subject to withholding tax in column 8 of annex 1. The annex serves as a refund claim: the 35% withheld is credited against your tax or refunded.
Rather hand it over?
NeoFidu prepares and files your Neuchâtel tax return for you, including property, securities and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from the 2025 general instructions (« Instructions générales ») of the Neuchâtel cantonal tax service (Service des contributions), the overview of deductions for 2026 published in its 2026 interim instructions, its leaflets (« notices ») and the Swiss Federal Tax Administration's Neuchâtel cantonal sheet (February 2026). Clic&Tax is not available in English: we quote the French labels, followed by a translation, so you can find them on screen. If in doubt, the tax service's general instructions prevail.