Clic&Tax · Chapter 9/11
Deductions in Clic&Tax: insurance premiums, childcare, medical costs, donations and social deductions (items 6.7 to 7.3)
Key points
- Insurance premiums (health, accident, life) and savings interest (item 6.8): at most CHF 4,900 for a married couple and CHF 2,500 for others, + CHF 800 per child or dependant; 25% more without pillar 2 or 3a.
- Childcare for children under 14 (6.13): up to CHF 20,400 per child, if both parents work. Professional training (6.14): up to CHF 12,400.
- Medical costs (6.17): only the portion above 5% of net income (item 6.16) is deductible. Donations (6.18): from CHF 100, up to 5% of net income.
- Social deductions: tapering modest-income deduction (7.1), CHF 6,200 to 8,200 per child (7.2), CHF 3,100 per dependent person in need (7.3).
Overview of 2026 deductions
| Deduction | Item | Cantonal and municipal tax | Direct federal tax |
|---|---|---|---|
| AHV/disability/APG/unemployment contributions of non-earners | 6.7 | Amount paid | Amount paid |
| Insurance premiums, married couple | 6.8 | CHF 4,900 (CHF 6,125 without pillar 2 or 3a) | CHF 3,700 (CHF 5,550) |
| Insurance premiums, others | 6.8 | CHF 2,500 (CHF 3,125) | CHF 1,800 (CHF 2,700) |
| Supplement per child or dependant | 6.8 | CHF 800 | CHF 700 |
| Both spouses working | 6.9 | 25% of the lower income, max. CHF 1,200 | 50%, min. CHF 8,600, max. CHF 14,100 |
| Disability-related costs | 6.11 | Costs paid or flat rate | Costs paid or flat rate |
| Payments to political parties | 6.12 | max. CHF 5,200 | max. CHF 10,600 |
| Childcare (under 14) | 6.13 | max. CHF 20,400 per child | max. CHF 25,800 per child |
| Training and further education | 6.14 | max. CHF 12,400 | max. CHF 13,000 |
| Medical costs | 6.17 | Portion above 5% of net income | Portion above 5% of net income |
| Donations | 6.18 | min. CHF 100, max. 5% of net income | min. CHF 100, max. 20% |
| Modest income; married couple (federal tax) | 7.1 | max. CHF 3,800 or 2,100, tapering | CHF 2,800 for married couples |
| Per child | 7.2 | CHF 6,200, 6,700 or 8,200 by age | CHF 6,800 |
| Dependent person in need | 7.3 | CHF 3,100 | CHF 6,800 |
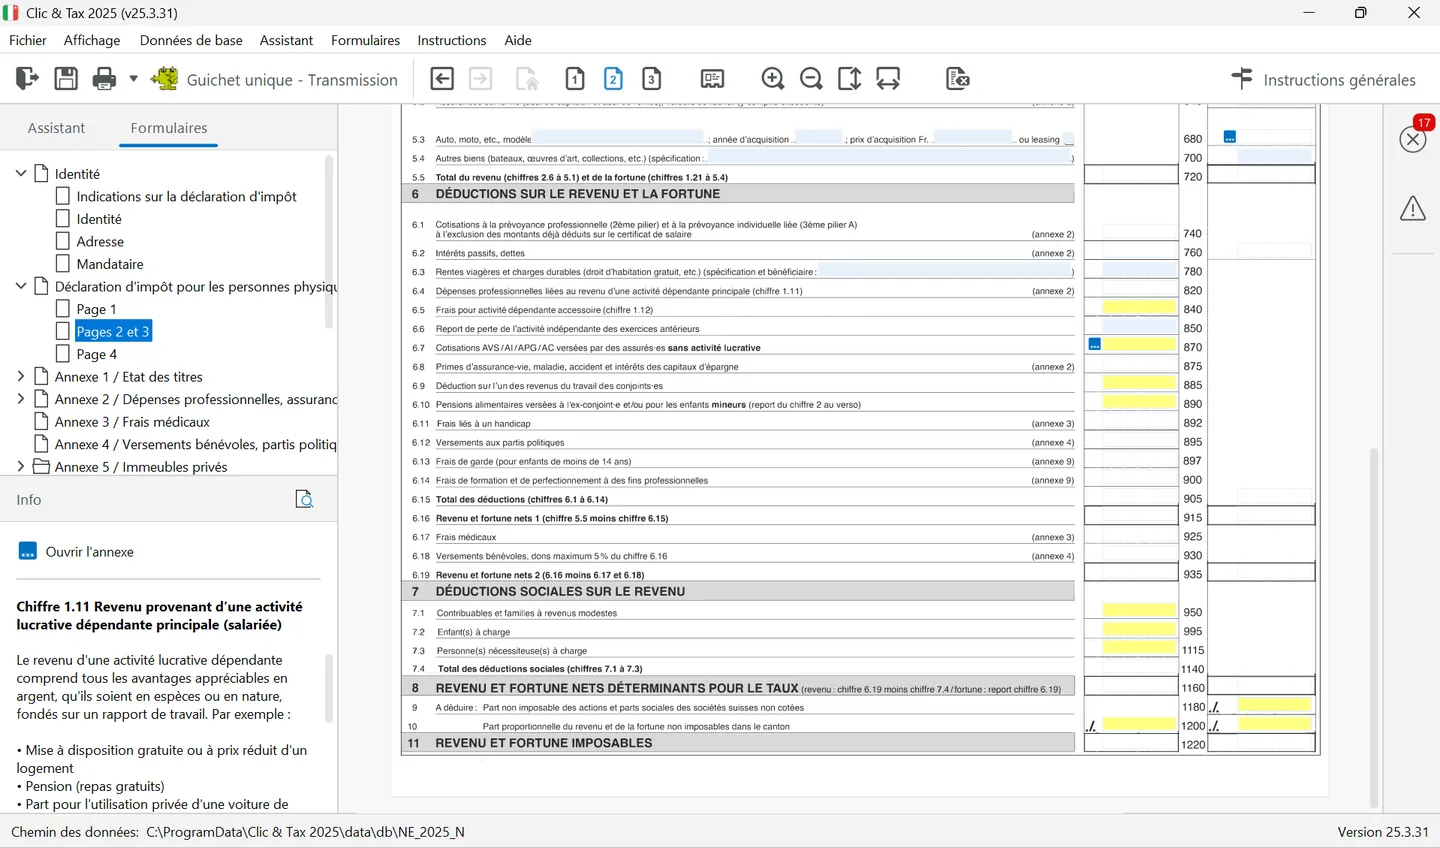
Clic&Tax calculates the caps and social deductions itself: you enter the amounts paid and it keeps the maximum allowed. Deductions are at the bottom of « Pages 2 et 3 » (items 6.1 to 11); the yellow fields, such as 6.9, 6.10 and 7.1 to 7.3, are calculated automatically and are not entered. The « ... » button of item 6.7 opens a table for the AHV contributions of non-earners, per taxpayer. For federal tax, the tax service applies the federal amounts automatically. Details go on the annexes: annex 2 (back) for premiums, annex 3 for medical and disability costs, annex 4 for donations and parties, annex 9 for childcare and training.
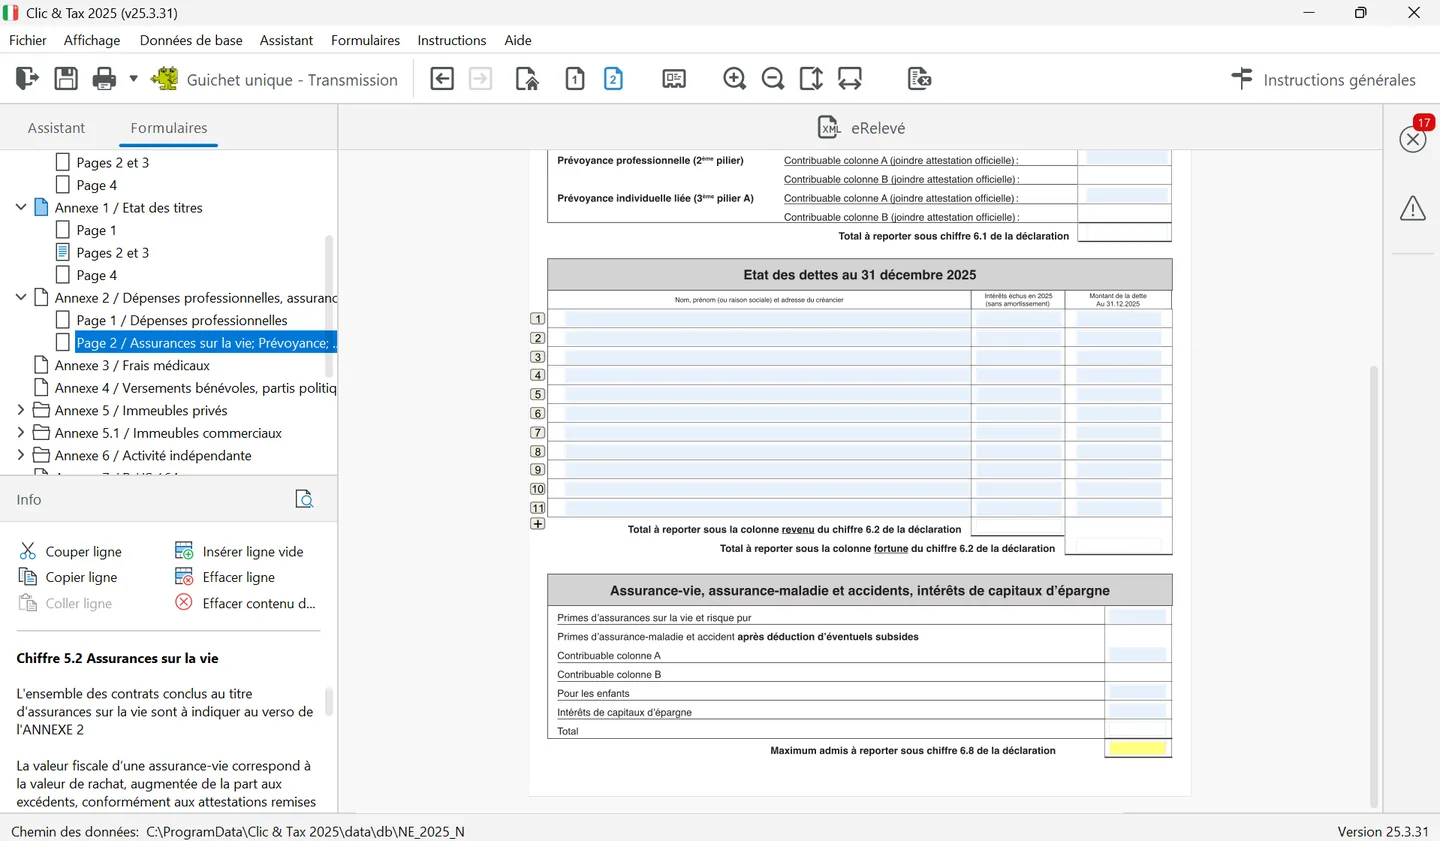
Insurance premiums and savings interest: item 6.8
On the back of annex 2, enter for each spouse the health and accident insurance premiums (basic and supplementary, loss of earnings) paid in 2026, after deducting subsidies from the cantonal health insurance office, life insurance and pure risk premiums, and interest on savings (accounts, savings books, bonds, private loans). Income from shares and funds is not included. The total is capped according to your situation, then carried to item 6.8. The cap rises by 25% if you contributed to neither pillar 2 nor pillar 3a, and by CHF 800 per child or dependant.
Couples, maintenance and disability: items 6.9 to 6.12
- 6.9 Two earners: if both spouses work, 25% of the lower income (after expenses, social security and pension contributions), at most CHF 1,200. Also allowed if one spouse substantially helps in the other's self-employed business, but not if it makes a loss.
- 6.10 Maintenance paid to an ex-spouse and for minor children: fully deductible, including family allowances and payments in kind (rent, premiums). Complete question 2 of the additional information. Maintenance for an adult child is not deductible, but gives the dependent person deduction (7.3).
- 6.11 Disability-related costs: fully deductible, either as actual costs (with a medical questionnaire) or as an annual flat rate depending on the helplessness allowance, deafness or dialysis. Fill in annex 3.
- 6.12 Political parties: up to CHF 5,200, if the party is on the federal party register, represented in a cantonal parliament or won at least 3% of the vote at the last cantonal election (annex 4).
Childcare and training: items 6.13 and 6.14
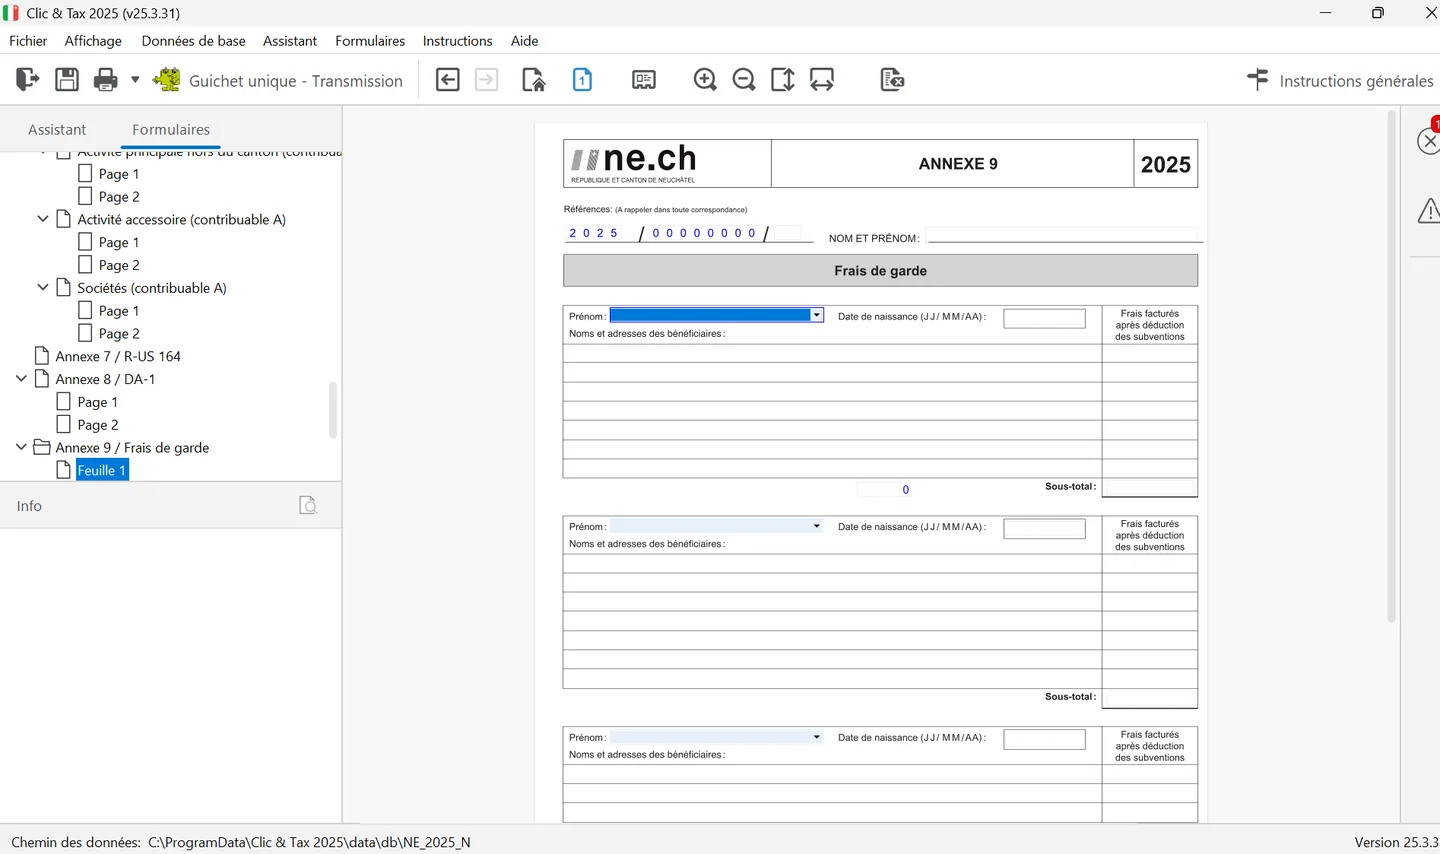
Third-party childcare for a child under 14 who lives with you and qualifies for the child deduction is deductible up to CHF 20,400 per child: nursery, after-school care, childminder, au pair, holiday camps, paid care by relatives. Enter the amounts after subsidies on annex 9. Conditions: both parents work (a disability pension or training counts as work), or the single parent works. Unmarried couples share the deduction equally, unless they agree otherwise. During unemployment, care by relatives is not deductible.
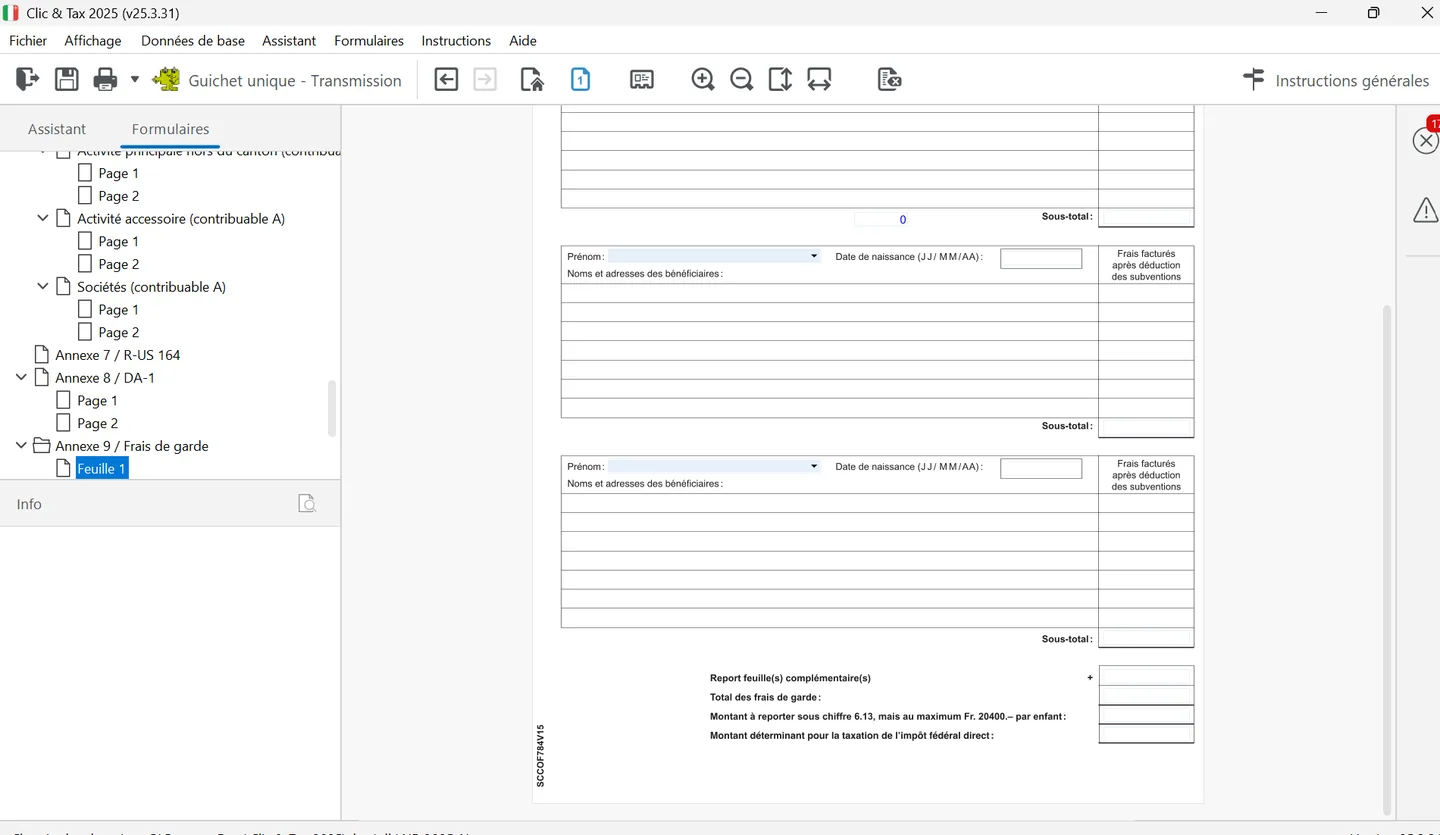
Annex 9 « Frais de garde » has sheets (« Feuille 1, 2, 3 ») with a box per child: first name picked from the list, date of birth, names and addresses of the carers and costs invoiced net of subsidies. The total goes to item 6.13, up to CHF 20,400 per child; a separate line gives the amount relevant for direct federal tax.
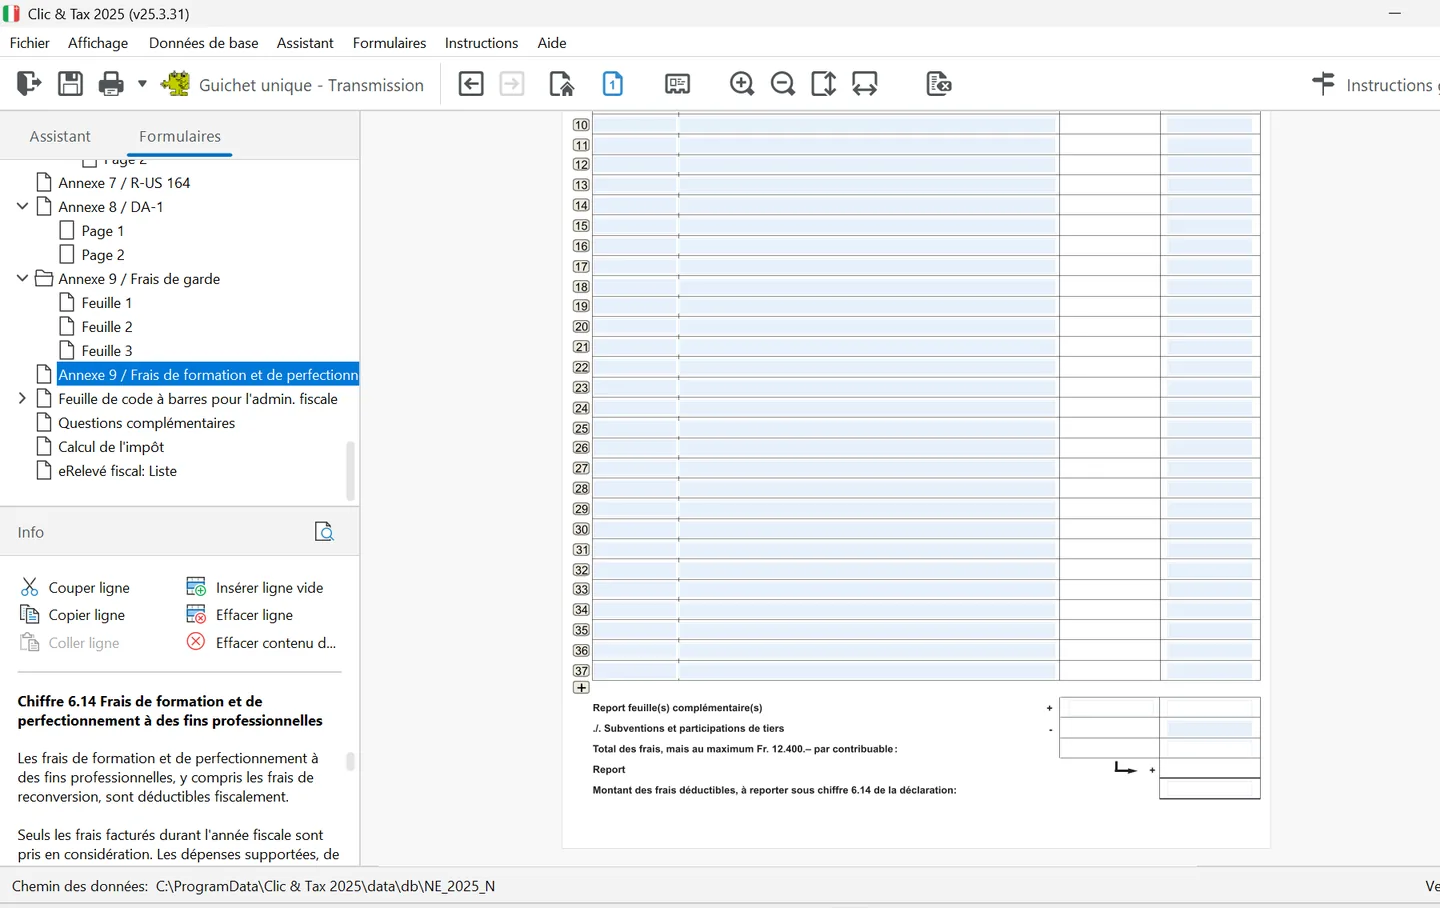
Professional training and further education costs, retraining included, are deductible up to CHF 12,400 a year, if invoiced in 2026 and if you hold an upper-secondary qualification (federal VET diploma or certificate, baccalaureate, specialised school) or are 20 or over and preparing another qualification. Amounts paid and any employer contributions or subsidies are detailed in the « Annexe 9 / Frais de formation et de perfectionnement » form; attach the receipts.
The form lists costs line by line (date, type of costs invoiced during the tax period) in the column of taxpayer A or B, subtracts subsidies and third-party contributions, caps the total at CHF 12,400 per taxpayer and carries the deductible amount to item 6.14.
Medical costs and donations: items 6.17 and 6.18
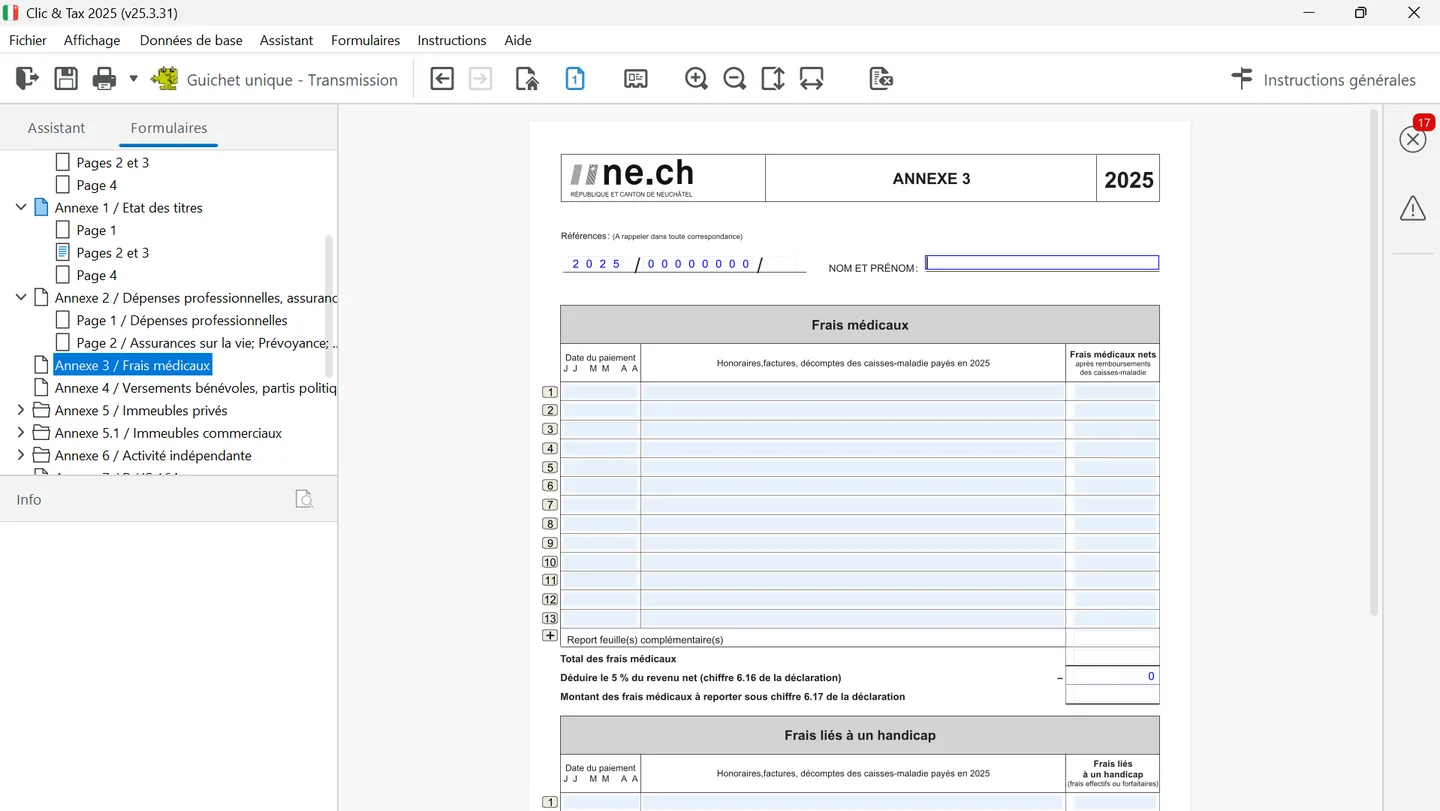
On annex 3, list illness and accident costs paid in 2026 for yourself, your spouse and your dependants, after health insurer reimbursements: doctors, dentist, glasses and lenses, prescribed medicines, hospital, ambulance, home nursing, prescribed alternative medicine, assisted reproduction, pregnancy. Only the portion above 5% of net income (item 6.16) is deductible. For a care home, one third of the costs, at least CHF 11,880 a year, is treated as non-deductible board and lodging. Not allowed: gym, yoga, non-prescribed cosmetic surgery, travel costs.
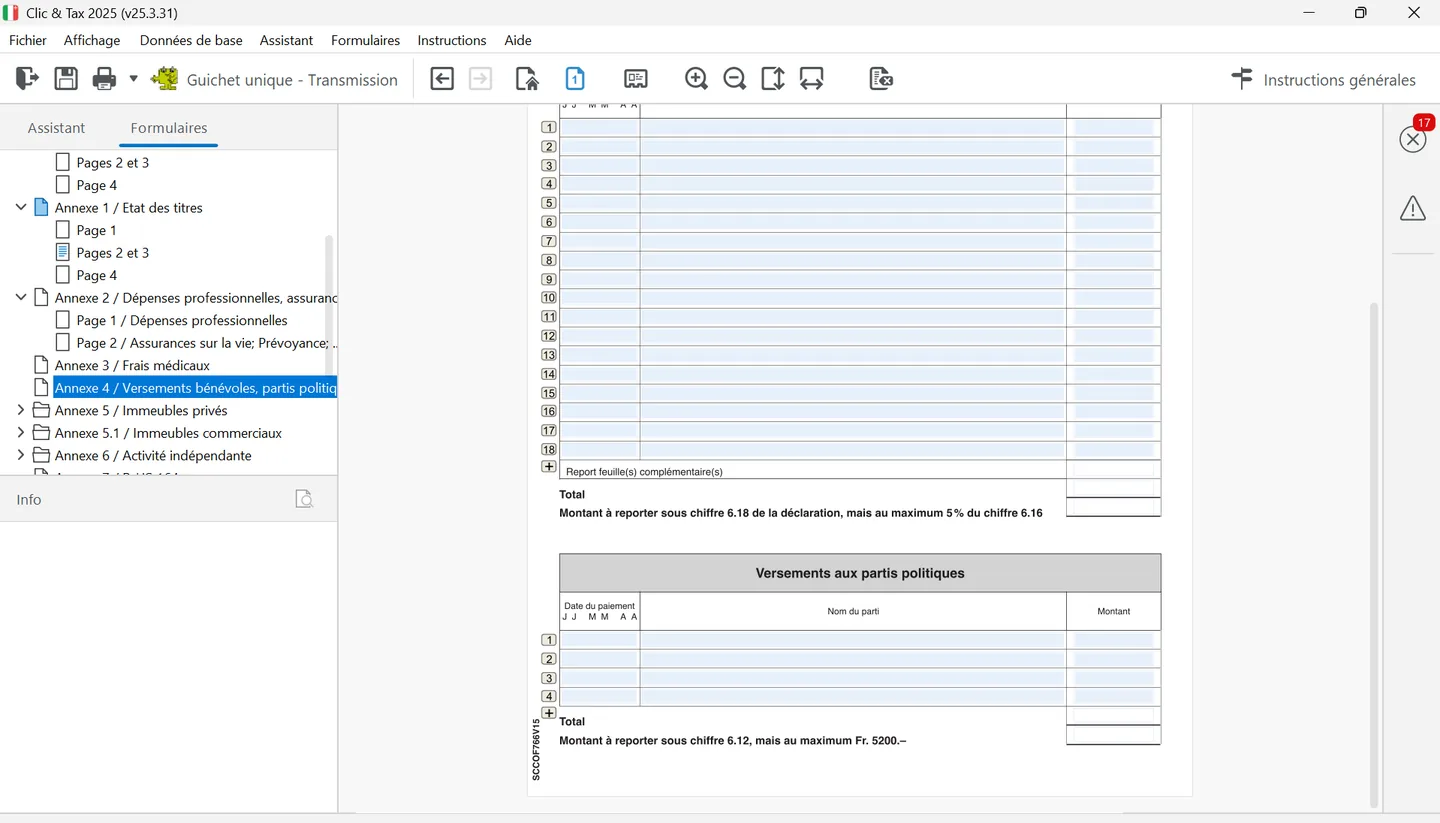
Donations to Swiss tax-exempt public-benefit bodies, the Confederation, cantons and municipalities are deductible if they total at least CHF 100 in the year, up to 5% of net income (20% for federal tax). Membership fees and the church contribution are not donations. Fill in annex 4 and keep the receipts.
Social deductions: items 7.1 to 7.3
| Situation on 31 December | Deduction 7.1 | Reduction |
|---|---|---|
| Married couple, or single person living with children or persons in need | CHF 3,800 | CHF 200 per CHF 1,000 of net income (item 6.19) above CHF 48,000; nothing left from CHF 67,000 |
| Other taxpayers | CHF 2,100 | CHF 100 per CHF 1,000 above CHF 26,000; nothing left from CHF 47,000 |
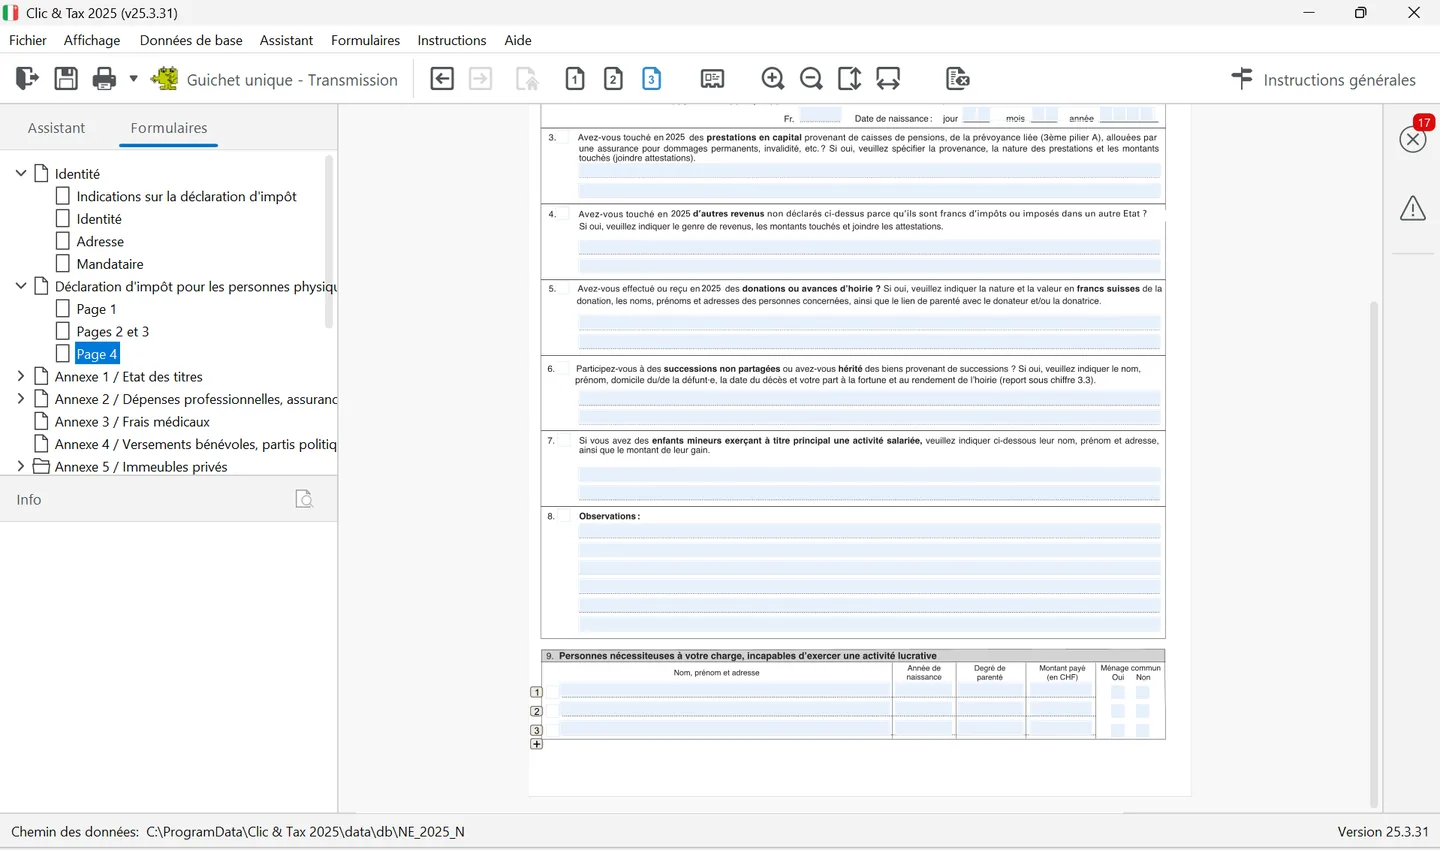
The child deduction (7.2) is CHF 6,200 from 0 to 4, CHF 6,700 from 4 to 14 and CHF 8,200 from 14 for a child in training (see Personal situation). The dependent person in need deduction (7.3), of CHF 3,100, applies to a person without assets or resources who cannot work because of illness, disability or age, if your support reaches at least that amount; it also applies to an adult child still in training on 31 December to whom you pay maintenance. In that case complete the question 9 table of the additional information (Page 4) every year: name, first name and address, year of birth, relationship, amount paid and shared household.
All deductions entered? If you are taxed at source, read the Tax at source and TOU chapter; otherwise go straight to Check and file.
Frequently asked questions
How much can I deduct for health insurance in Neuchâtel in 2026?
Together with other insurance premiums and savings interest, at most CHF 4,900 for a married couple and CHF 2,500 for a single person, plus CHF 800 per child or dependant. Without pillar 2 or 3a contributions, the cap rises to CHF 6,125 or CHF 3,125. Subsidies received are deducted from the premiums.
How much can I deduct for nursery costs in the canton of Neuchâtel?
Childcare invoiced in 2026 for a child under 14, after subsidies, up to CHF 20,400 per child for cantonal tax and CHF 25,800 for federal tax, if both parents work or the single parent works.
From what amount are medical costs deductible in Neuchâtel?
Only the portion of costs paid and not reimbursed that exceeds 5% of net income (item 6.16 of the return) is deductible. List them on annex 3.
What is the modest-income deduction in Neuchâtel?
A social deduction of CHF 3,800 for couples and single-parent families and CHF 2,100 for other taxpayers, gradually reduced from a net income of CHF 48,000 or CHF 26,000. Clic&Tax calculates it automatically.
Rather hand it over?
NeoFidu prepares and files your Neuchâtel tax return for you, including property, securities and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from the 2025 general instructions (« Instructions générales ») of the Neuchâtel cantonal tax service (Service des contributions), the overview of deductions for 2026 published in its 2026 interim instructions, its leaflets (« notices ») and the Swiss Federal Tax Administration's Neuchâtel cantonal sheet (February 2026). Clic&Tax is not available in English: we quote the French labels, followed by a translation, so you can find them on screen. If in doubt, the tax service's general instructions prevail.