Clic&Tax · Chapter 7/11
Wealth and debts in Clic&Tax: life insurance, vehicles, debts and interest paid (items 5.2 to 6.3)
Key points
- Life insurance with a surrender value is declared at its surrender value on 31 December, bonuses included (back of annex 2, item 5.2).
- A car is declared at its purchase price less 30% a year on the remaining value, rounded down to the thousand (item 5.3). A leased vehicle is not taxable.
- Debts and interest paid are detailed on the back of annex 2 (item 6.2), creditor by creditor. Private interest is deductible up to investment income plus CHF 50,000.
- Wealth tax: 0‰ up to CHF 50,000, then 3‰, 4‰ and 5‰; above CHF 500,000, 3.6‰ on all wealth. Couples and single parents: rate calculated on 52%.
Life insurance: item 5.2
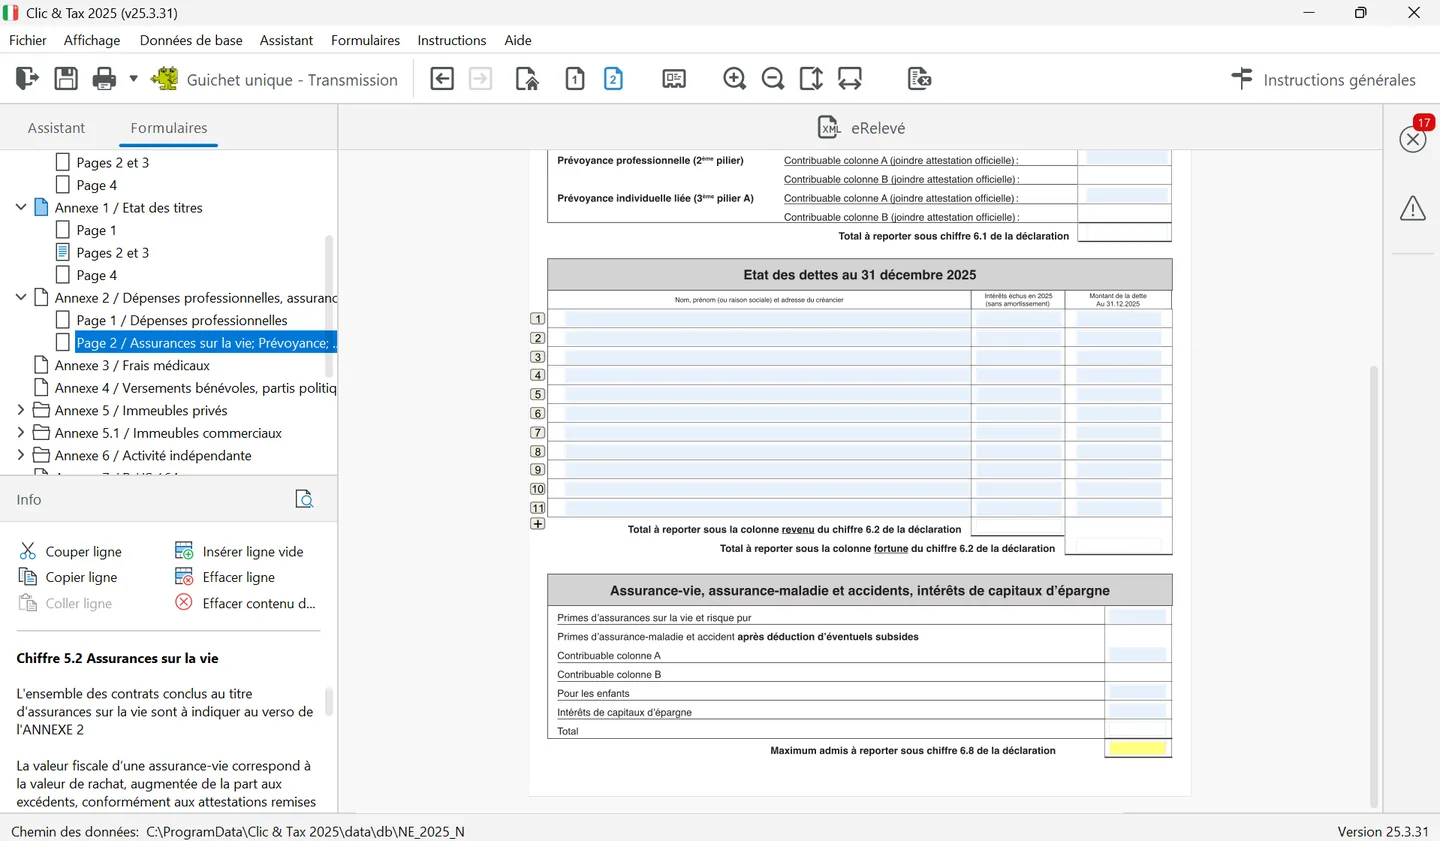
All life insurance contracts are listed on the back of annex 2, under « Valeurs fiscales des assurances sur la vie » (tax values of life insurance). The tax value is the surrender value, plus accrued bonuses, according to the insurer's certificate on 31 December 2026. Endowment and fixed-term policies and life annuities with a guarantee have a surrender value; pure risk policies for death or incapacity, and life annuities without a guarantee, do not. The table asks, for each policy, the insurer, the year it was taken out, the maturity year and the tax value on 31 December; the total is carried to item 5.2. Premiums paid are deducted in item 6.8 (see Deductions).
Vehicles and other assets: items 5.3 and 5.4
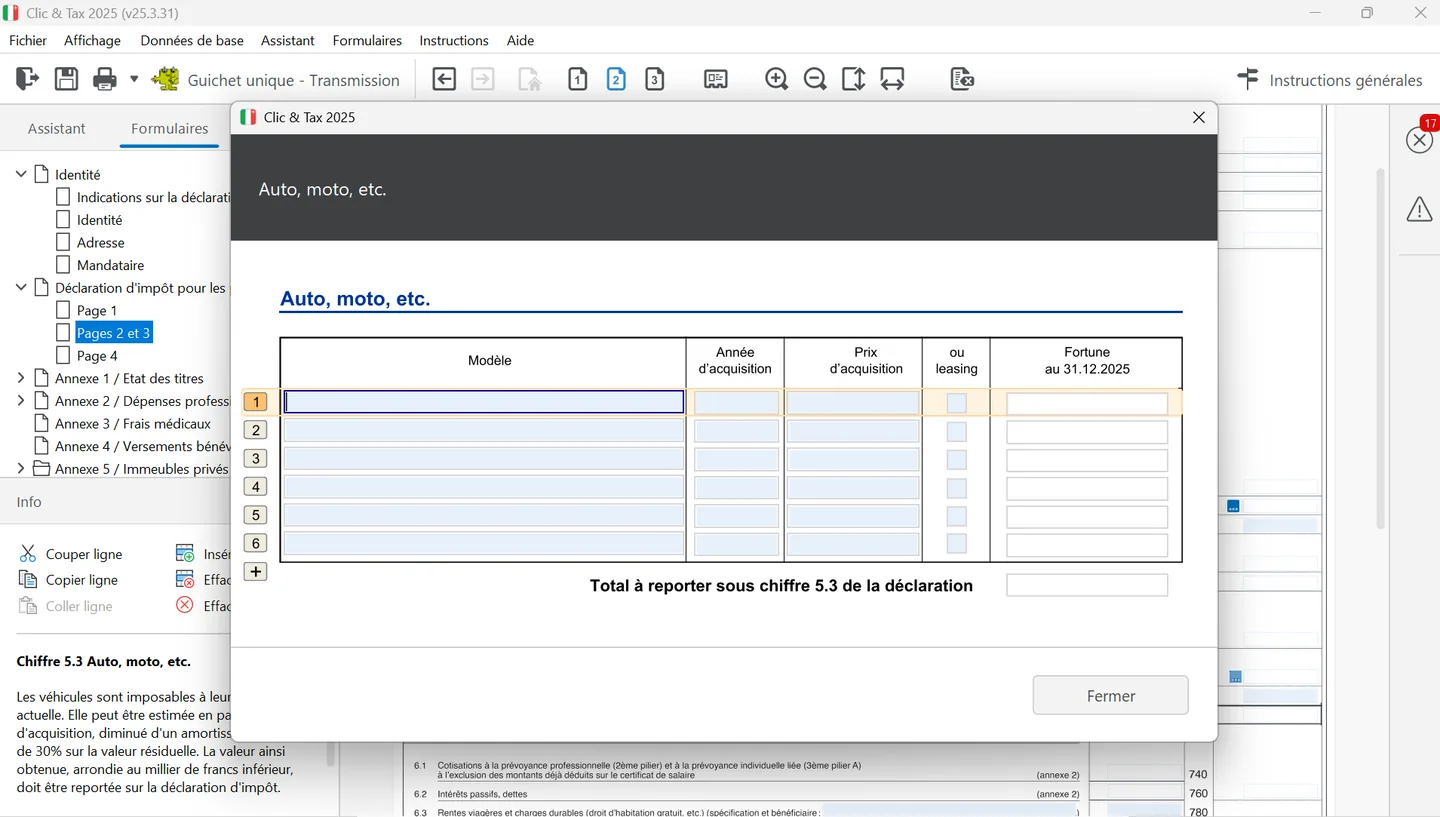
Vehicles are taxable at their market value. The tax service accepts starting from the purchase price, less depreciation of 30% a year on the remaining value, then rounding down to the thousand francs. Enter the model, year and purchase price. A leased vehicle is not taxable as wealth: just tick the corresponding box (« leasing »). In Clic&Tax, the small blue « ... » button of item 5.3 opens the « Auto, moto, etc. » table: model, year of purchase, purchase price, « ou leasing » box and wealth on 31 December, whose total is carried to item 5.3.
Boats, works of art, collections and other valuables are declared at market value in item 5.4, stating what they are.
Debts and interest paid: item 6.2
On the back of annex 2, the list of debts on 31 December 2026 (« État des dettes ») shows for each debt the creditor's exact name and address, the amount owed and the interest due in 2026. Total debts are deducted from wealth and total interest from income, in item 6.2. Fees, late-payment interest and commissions on these debts are also deductible.
- Cap: private interest paid is deductible up to the gross taxable income from wealth, plus CHF 50,000. Business interest is deductible without limit.
- Not deductible: debt repayments, interest on a construction loan, leasing interest, the penalty for terminating a fixed-rate mortgage on a sale (deductible from property gains tax instead).
- Non-repayable federal interest reductions granted to owners reduce mortgage interest.
In item 6.3, giving the beneficiary's name and address, you can deduct the income portion of life annuities you pay, the value of a free right of residence you grant and permanent charges (land charge, easement). Ground rent for a building right is not deductible.
The wealth tax scale
| Taxable wealth | Rate for each band |
|---|---|
| CHF 0 to 50,000 | 0‰ |
| CHF 50,001 to 200,000 | 3‰ |
| CHF 200,001 to 350,000 | 4‰ |
| CHF 350,001 to 500,000 | 5‰ |
| Above CHF 500,000 | 3.6‰ on all wealth |
Married couples living together and single parents living with their children benefit from splitting: the rate is calculated on 52% of wealth. Taxable wealth is rounded down to the thousand francs. Pillar 2 and pillar 3a assets are not included. There is no federal wealth tax. Next, move on to property.
Frequently asked questions
How do I declare my car on the Neuchâtel return?
In item 5.3, at market value. Start from the purchase price and deduct 30% a year on the remaining value, then round down to the thousand francs. A leased vehicle is not taxable: tick the leasing box.
What is the cap on deducting interest paid in Neuchâtel?
Private interest paid is deductible up to the gross taxable income from wealth, plus CHF 50,000. Debt repayments and leasing interest are not deductible.
From what level of wealth do you pay wealth tax in Neuchâtel?
The scale starts at 0‰ up to CHF 50,000 of taxable wealth, then 3‰ up to CHF 200,000. For couples and single parents, the rate is calculated on 52% of wealth, which pushes these thresholds higher.
Do I have to declare life insurance in Clic&Tax?
Yes, on the back of annex 2 and in item 5.2, at its surrender value on 31 December, bonuses included. A pure risk policy without a surrender value has no tax value.
Rather hand it over?
NeoFidu prepares and files your Neuchâtel tax return for you, including property, securities and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from the 2025 general instructions (« Instructions générales ») of the Neuchâtel cantonal tax service (Service des contributions), the overview of deductions for 2026 published in its 2026 interim instructions, its leaflets (« notices ») and the Swiss Federal Tax Administration's Neuchâtel cantonal sheet (February 2026). Clic&Tax is not available in English: we quote the French labels, followed by a translation, so you can find them on screen. If in doubt, the tax service's general instructions prevail.