Clic&Tax · Chapter 4/11
Work expenses in Clic&Tax: annex 2, commuting, meals, 3% flat rate and home working (item 6.4)
Key points
- Work expenses are entered on annex 2 and carried to item 6.4. Clic&Tax calculates the flat rates itself.
- Commuting: actual cost of public transport. A car is only allowed if public transport cannot reasonably be used: CHF 0.60 per km up to 10,000 km, 0.40 for the next 5,000, 0.30 beyond. For federal tax, at most CHF 3,300.
- Meals: CHF 15 per day, at most CHF 3,200 a year, or CHF 7.50 (max. CHF 1,600) with a canteen or allowance.
- Other expenses: flat rate of 3% of net salary, at least CHF 2,000 and at most CHF 4,000, plus, for regular home working, 10% of net salary (max. CHF 4,000) prorated by days.
The principle: annex 2, item 6.4
Employees can deduct the expenses needed to earn their income that their employer does not reimburse. On the Neuchâtel return they are detailed on annex 2, « Dépenses professionnelles liées au revenu d'une activité dépendante principale » (work expenses for main employment), one part per spouse, and the total is carried to item 6.4. The annex starts with your activity rate (« Taux d'activité »): part-time, enter the number of full days and half days worked per week. Training costs do not go here but in item 6.14 (see Deductions).
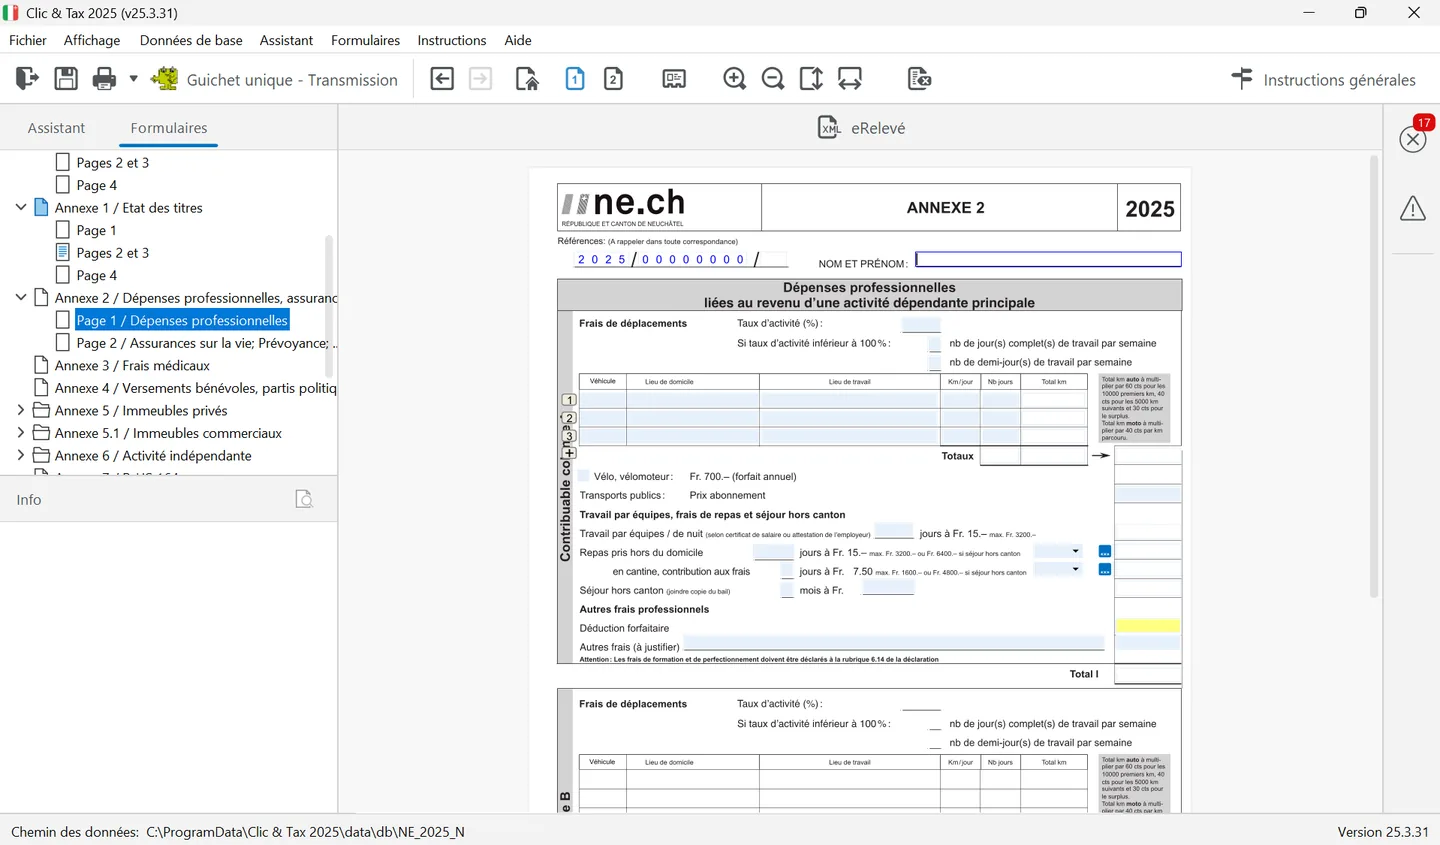
For commuting, the table asks for each journey the vehicle (« Véhicule »), home (« Lieu de domicile »), workplace (« Lieu de travail »), km per day and number of days: Clic&Tax calculates the total kilometres and applies the per-km rates. Tick « Vélo, vélomoteur » for the CHF 700 flat rate, or enter the season ticket price on the « Transports publics » line. Meals are entered as a number of days. The flat-rate deduction (« Déduction forfaitaire ») for other expenses, in yellow, is calculated automatically; the « Autres frais (à justifier) » line is for actual costs. The same grid is repeated below for taxpayer column B, and Total I + Total II is carried to item 6.4.
Commuting costs
| Means of transport | Cantonal and municipal tax | Direct federal tax |
|---|---|---|
| Public transport | Actual cost (season ticket price) | Actual cost |
| Bicycle, light motorcycle (50 cc) | CHF 700 a year (flat rate) | CHF 700 a year |
| Motorcycle | CHF 0.40 per km | CHF 0.40 per km |
| Car, first 10,000 km | CHF 0.60 per km | CHF 0.75 per km |
| Car, next 5,000 km | CHF 0.40 per km | CHF 0.75 per km |
| Car, beyond | CHF 0.30 per km | CHF 0.75 per km |
| Cap | None | CHF 3,300 in total |
In principle, only the cost of public transport is deductible. Car or motorcycle costs are allowed if you show that there is no public transport, or that it cannot reasonably be used (unsuitable timetable, disability). Your workplace must be far enough away: at least 1.5 km per journey or 15 minutes on foot.
- A return home at lunchtime counts for at most CHF 15 per day and CHF 3,200 a year.
- A parking space is included in the mileage allowance.
- A spouse using the same vehicle, or car-sharing, does not deduct extra costs.
- With a company car provided free for the commute, no commuting deduction is allowed.
Meals, shift work and weekly stays outside the canton
| Situation | Per day | Maximum per year |
|---|---|---|
| Meals away from home, no employer allowance | CHF 15 | CHF 3,200 |
| Meals with a canteen or allowance (meal vouchers, reimbursement) | CHF 7.50 | CHF 1,600 |
| Shift work, continuous hours or night work | CHF 15 | CHF 3,200 |
| Weekly stay outside the canton, no allowance | CHF 30 | CHF 6,400 |
| Weekly stay outside the canton, with allowance or canteen | CHF 22.50 | CHF 4,800 |
The meal flat rate requires a real extra cost caused by the distance between home and work. The shift or night work deduction requires the employer to state the number of days on the salary certificate and night work of at least 8 consecutive hours, and cannot be combined with the meal flat rate. If you stay outside the canton during the week, you can add the rent of a room (attach the lease) and the cost of returning home weekly. In Clic&Tax, a small blue « ... » button on annex 2 opens a list to detail meals away from home and meals in a canteen.
Other work expenses: flat rate or actual costs
Other expenses essential to your job (tools, computer and software, professional books, a study, work clothing, union fees) are covered by a flat rate of 3% of net salary, at least CHF 2,000 and at most CHF 4,000. If your net salary is below CHF 20,000, the flat rate is 10%. Instead, you can deduct your actual costs with a detailed list, but never both. A private share is withheld on computer equipment; a study is only allowed if it is mainly and regularly reserved for work.
For secondary employment (item 1.12), a flat rate of 20% of net income, at least CHF 800 and at most CHF 2,400, is deducted in item 6.5; if you earned less than CHF 800, the deduction cannot exceed it. Actual costs are possible with a separate list.
Once your work expenses are entered, move on to retirement savings: pension fund buy-ins and pillar 3a.
Frequently asked questions
How much can I deduct for my car in the canton of Neuchâtel?
CHF 0.60 per km for the first 10,000 km, CHF 0.40 for the next 5,000 and CHF 0.30 beyond, if public transport cannot reasonably be used. For federal tax the rate is CHF 0.75 per km, but the total deduction is capped at CHF 3,300.
What is the flat rate for other work expenses in Neuchâtel?
3% of net salary, at least CHF 2,000 and at most CHF 4,000, or 10% if your net salary is below CHF 20,000. Actual costs can be deducted instead, with a detailed list.
Can I deduct home working on the Neuchâtel return?
Yes, for regular home working: 10% of net salary, at most CHF 4,000, prorated by home-working days per week, on top of the ordinary flat rate. Commuting and meals then only count for office days.
How much can I deduct for lunches in Neuchâtel?
CHF 15 per day, at most CHF 3,200 a year, if you cannot go home to eat. With a canteen or an employer allowance, CHF 7.50 per day and at most CHF 1,600 a year.
Rather hand it over?
NeoFidu prepares and files your Neuchâtel tax return for you, including property, securities and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from the 2025 general instructions (« Instructions générales ») of the Neuchâtel cantonal tax service (Service des contributions), the overview of deductions for 2026 published in its 2026 interim instructions, its leaflets (« notices ») and the Swiss Federal Tax Administration's Neuchâtel cantonal sheet (February 2026). Clic&Tax is not available in English: we quote the French labels, followed by a translation, so you can find them on screen. If in doubt, the tax service's general instructions prevail.