Clic&Tax · Chapter 8/11
Property in Clic&Tax: annex 5, cadastral value, imputed rental value and upkeep costs (items 4.1 and 4.2)
Key points
- Each property is detailed on annex 5: a Neuchâtel property goes in item 4.1, a property outside the canton or abroad in item 4.2.
- Wealth: the cadastral value (« estimation cadastrale »). Income: the imputed rental value of the home you live in (generally 3.5% of the cadastral value up to CHF 500,000) and gross rents received.
- Upkeep: each year and for each property, a flat rate of 10% of gross yield (max. CHF 7,200) for a building under 10 years old, 20% (max. CHF 12,000) above that, or actual costs invoiced in 2026.
- Investments that save energy are deductible; those that increase the property's value are not. Attach each invoice from CHF 5,000.
Annex 5: one property per annex
Annex 5 is filled in for each privately held property: type (villa, condominium « PPE », apartment building « locatif », land « terrain », other), municipality, address, ownership share, cadastral value and the answer to « L'immeuble a-t-il plus de 10 ans » (is the building over 10 years old). It calculates the gross income (rental value, rents, other income), subtracts upkeep costs, then carries the net income to item 4.1 (Neuchâtel property) or 4.2 (outside the canton). In the tree, properties sit in three folders, « Neuchâtel », « Hors canton » and « Etranger »; the « Ajouter un formulaire » button creates an annex for another property. Mortgage interest and the debt do not go here but in item 6.2 (see Wealth and debts). Business property falls under annex 5.1 and « NOTICE 3 ».
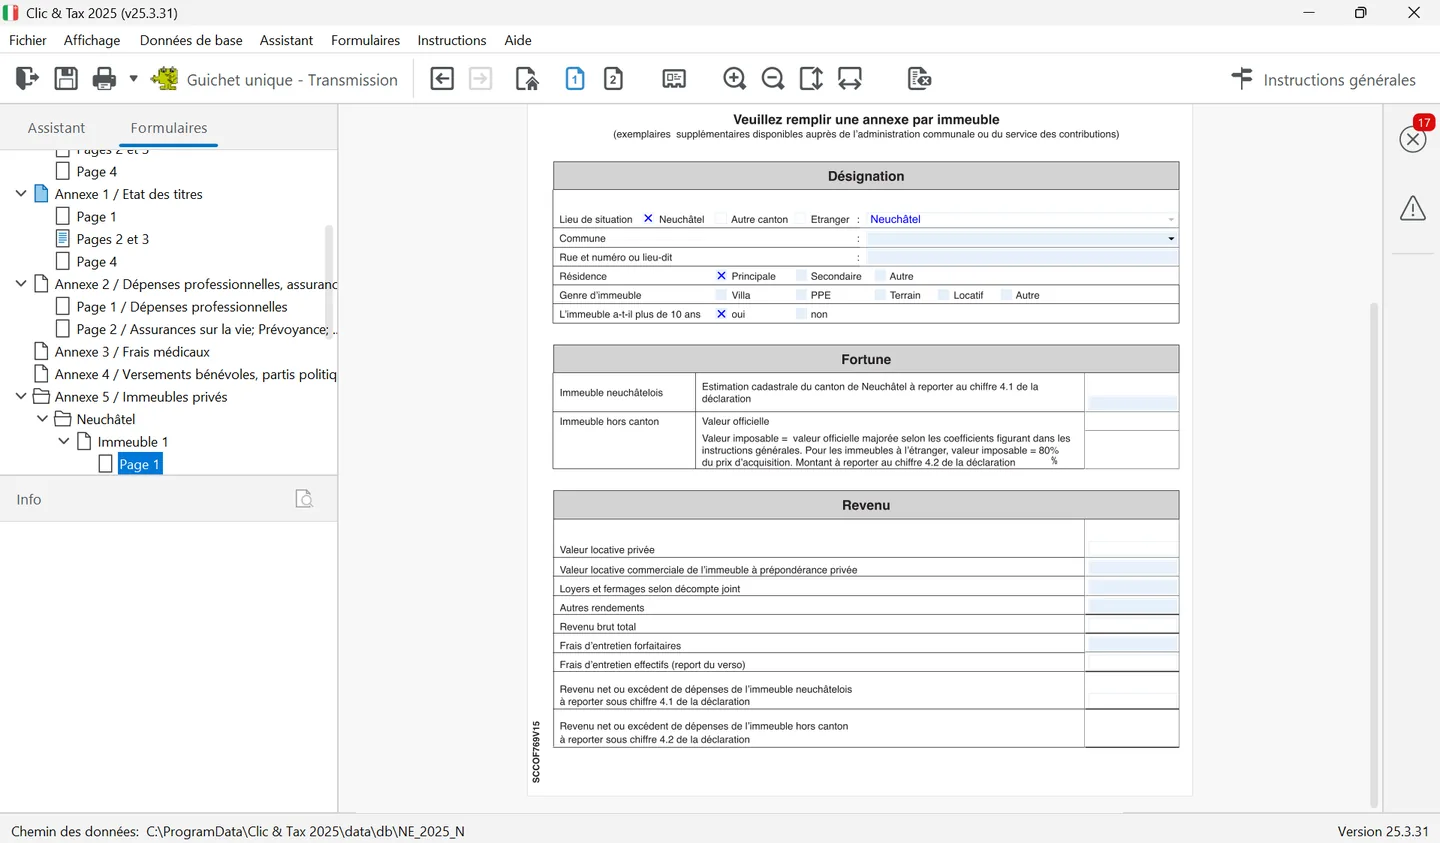
Cadastral value and imputed rental value
A privately held Neuchâtel property is subject to wealth tax at its cadastral value, set by the tax authority. If you bought it at a price 10% to 20% away from that value, you can ask for a review, at your own expense. Beyond 20%, or after construction or conversion work, the authority reviews it automatically. The imputed rental value of the home you live in is in principle 70% of the rent for a comparable property; for simplicity, the tax service calculates it as a percentage of the cadastral value.
| Portion of cadastral value | Rental value rate |
|---|---|
| CHF 0 to 500,000 | 3.50% |
| CHF 500,001 to 1,000,000 | 3.30% |
| CHF 1,000,001 to 1,500,000 | 2.70% |
| CHF 1,500,001 to 2,000,000 | 1.80% |
| Above CHF 2,000,000 | 0.80% |
- Rents and leases: the gross amount, including tenants' shares of water, lift and stairwell lighting, but without heating costs charged directly. Attach the management statements.
- Change of owner during the year: the rental value is prorated.
- Solar panels: only the energy exceeding your own consumption is taxable income.
- Partial business use by the owner: the rent charged in the accounts is declared as commercial rental value.
Upkeep costs: flat rate or actual costs
| Building age | Cantonal and municipal tax | Direct federal tax |
|---|---|---|
| Under 10 years | 10% of gross yield, max. CHF 7,200 | 10% of gross yield, no maximum |
| Over 10 years | 20% of gross yield, max. CHF 12,000 | 20% of gross yield, no maximum |
You choose each year and for each property between the flat rate and actual costs. The flat rate is not allowed for leased farms or for property mainly used by third parties for business. With actual costs, only work invoiced in 2026 counts: down payments are not deductible. Attach each invoice from CHF 5,000. For a rented property, further costs are added: caretaking, and energy or charges if they are included in the rent. The tax service's « NOTICE 4 » lists, item by item, what is deductible.
| Home you live in: deductible | Not deductible |
|---|---|
| Repairs and renovations that maintain value | Work that increases value |
| Third-party management fees, fire (ECAP), water damage and glass breakage insurance, owner's liability insurance | Household contents and private liability insurance |
| Payments into a condominium renovation fund, upkeep of common areas | Costs paid out of the renovation fund, condominium running costs |
| Maintenance contracts (lift, heating), boiler servicing, chimney sweeping, property tax | Fuel, energy and water, sewage and waste charges, snow clearing, caretaking |
| Garden upkeep, capped: 5% of cadastral value × 3.5%, max. CHF 2,000 | Notary fees, increasing a mortgage note, legal protection insurance |
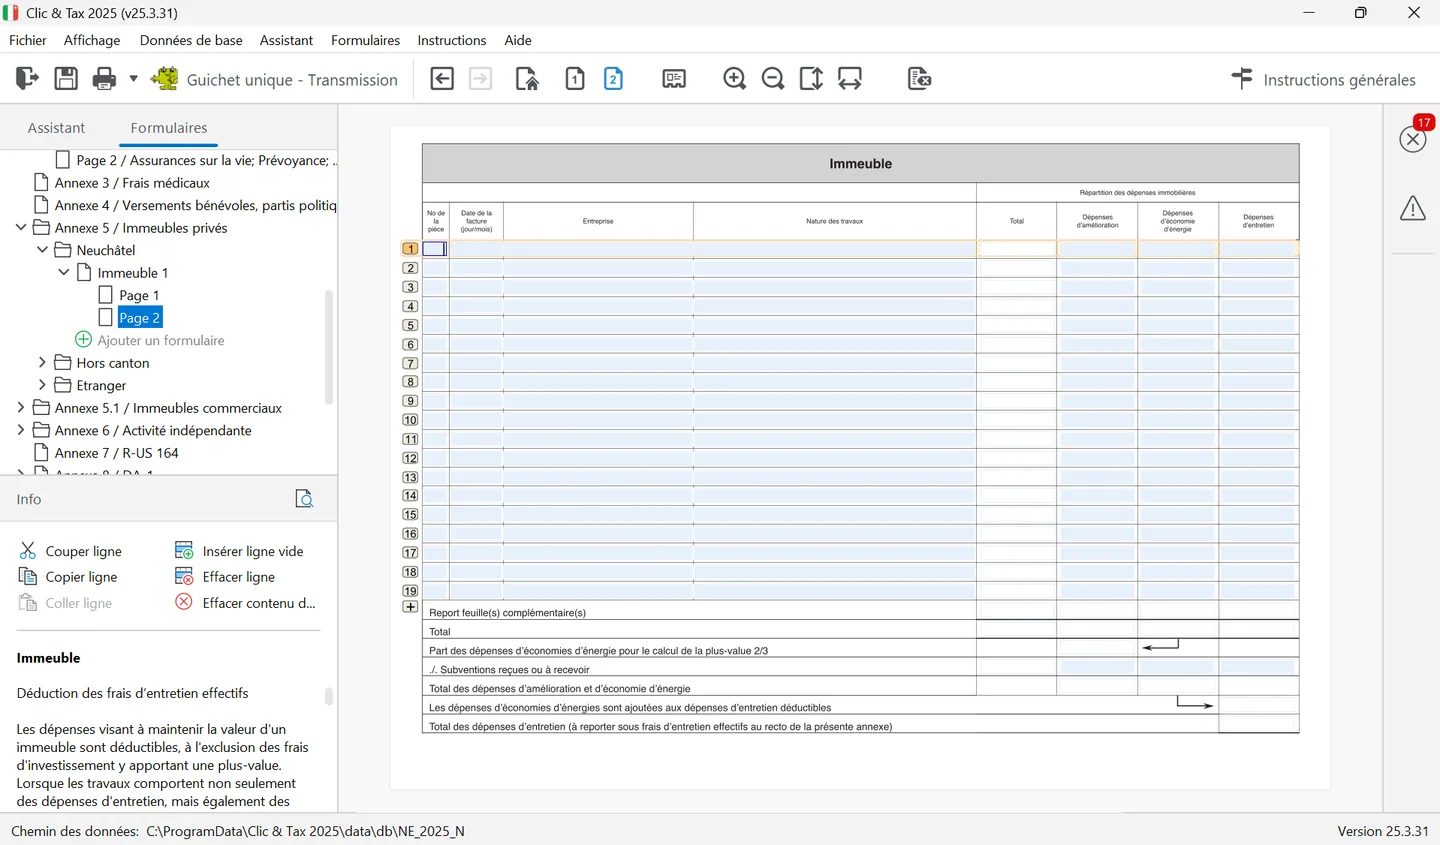
Actual costs are itemised on page 2 of annex 5, invoice by invoice: document number, date, contractor, type of work and amount, split between improvement, energy savings and upkeep, net of subsidies. The total is carried to the front page.
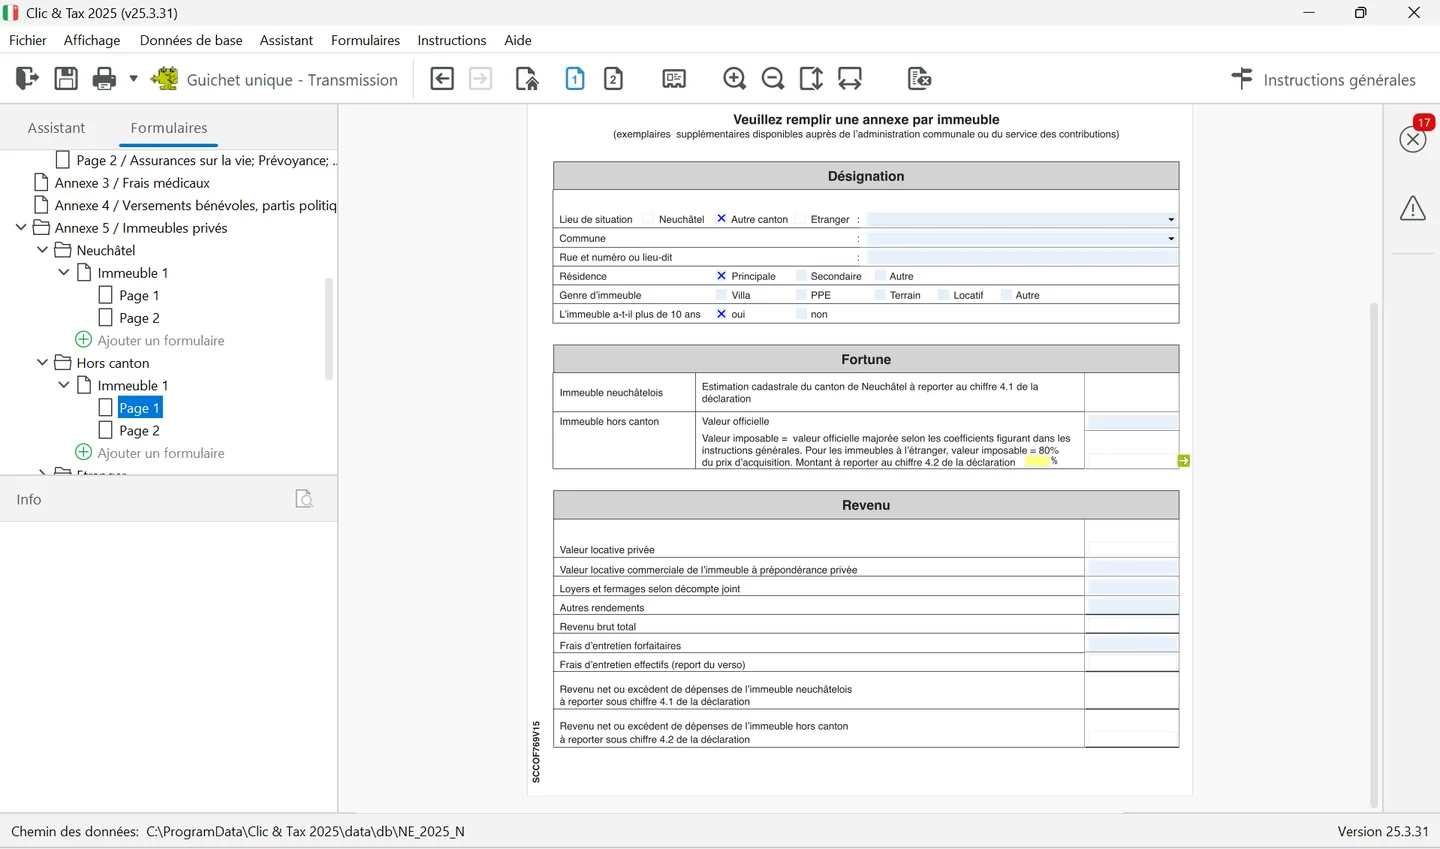
Property outside the canton and abroad: item 4.2
A private property in another canton is taxed at that canton's official value, adjusted by the Swiss Tax Conference coefficients. A property abroad counts at 80% of its purchase price, converted into francs at the 31 December rate set by the Federal Tax Administration. The rental value of a second home outside the canton uses the same scale as in Neuchâtel; rents and upkeep costs follow the same rules. These properties are not taxed in Neuchâtel, but they count for the rate: the tax service allocates them automatically, and a proportional share of your debts and interest is attributed to the other canton or country.
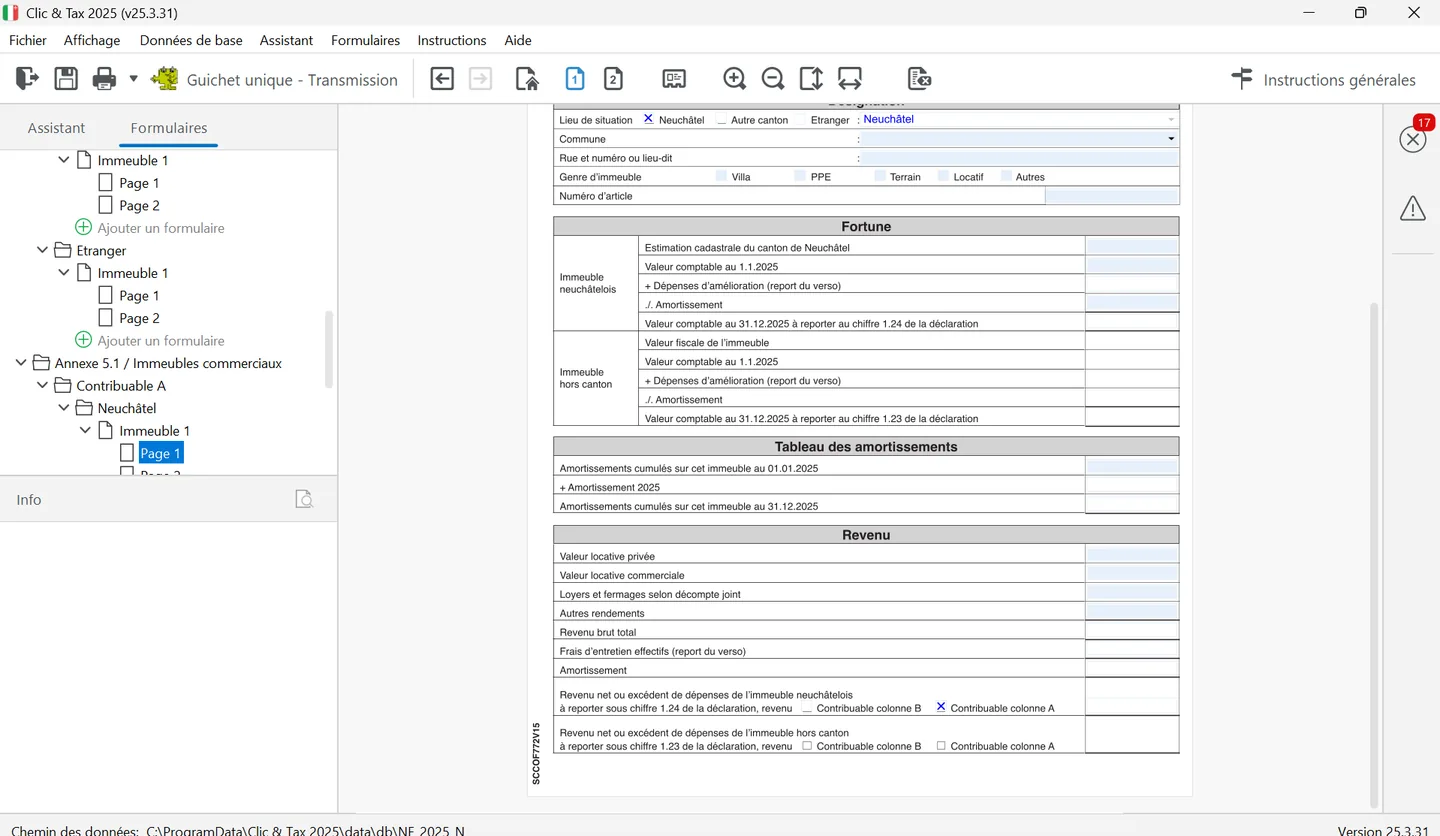
Business property: annex 5.1
A property that belongs to a self-employed person's business assets is declared on annex 5.1, sorted by taxpayer (A or B) then by location. It takes the cadastral value (or the tax value outside the canton), the book value on 1 January, improvement spending and the year's depreciation, a table of accumulated depreciation, then income (rental values, rents, other income) less actual upkeep costs and depreciation. Net income goes to item 1.24 for a Neuchâtel property or 1.23 for one outside the canton, in the column of the taxpayer concerned (see Salary and income).
Frequently asked questions
How is the imputed rental value calculated in the canton of Neuchâtel?
As a percentage of the cadastral value: 3.5% up to CHF 500,000, 3.3% from 500,001 to 1,000,000, 2.7% up to 1,500,000, 1.8% up to 2,000,000 and 0.8% above. For a villa valued at CHF 600,000, the rental value is CHF 20,800.
What is the upkeep flat rate for a property in Neuchâtel?
10% of gross yield, at most CHF 7,200, for a building under 10 years old; 20%, at most CHF 12,000, above that. For federal tax, the same percentages apply without a maximum. You can choose actual costs instead, each year and for each property.
How do I declare a flat abroad in Clic&Tax?
On annex 5, carried to item 4.2. Its tax value is 80% of the purchase price, converted into francs at the 31 December rate. It is not taxed in Neuchâtel but is used to determine your tax rate.
Do I have to attach upkeep invoices to the Neuchâtel return?
Yes, each invoice of CHF 5,000 or more, as well as management statements for managed properties. Only costs invoiced during the year are deductible, not down payments.
Rather hand it over?
NeoFidu prepares and files your Neuchâtel tax return for you, including property, securities and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from the 2025 general instructions (« Instructions générales ») of the Neuchâtel cantonal tax service (Service des contributions), the overview of deductions for 2026 published in its 2026 interim instructions, its leaflets (« notices ») and the Swiss Federal Tax Administration's Neuchâtel cantonal sheet (February 2026). Clic&Tax is not available in English: we quote the French labels, followed by a translation, so you can find them on screen. If in doubt, the tax service's general instructions prevail.