Clic&Tax · Chapter 5/11
Retirement savings in Clic&Tax: pillar 3a, pension fund buy-ins, 3a catch-up and lump sums (item 6.1)
Key points
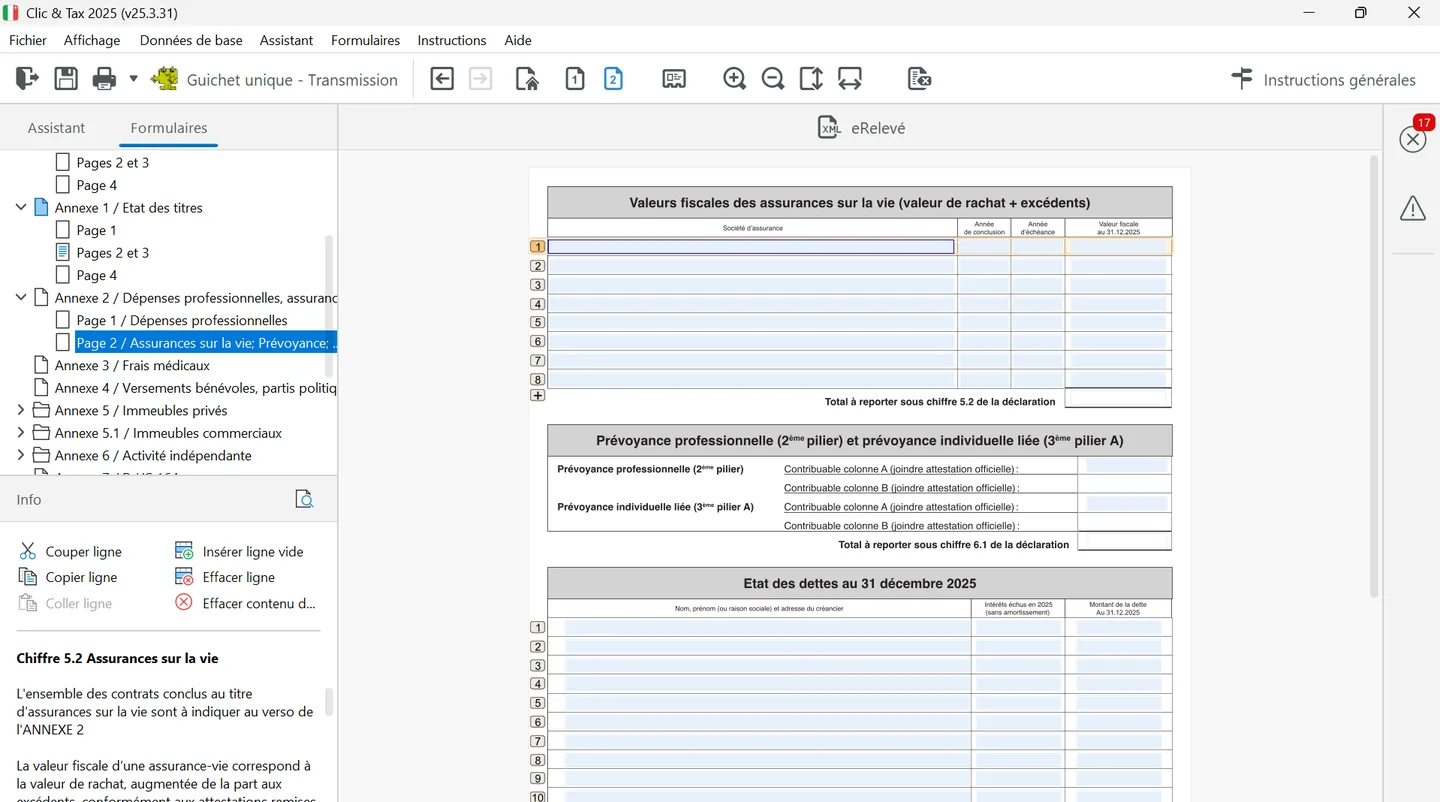
- Pillar 3a contributions and pension fund buy-ins are detailed on the back of annex 2 and carried to item 6.1, for each spouse, with the certificates.
- Pillar 3a 2026: CHF 7,258 at most with a pension fund; without pillar 2, 20% of earned income, at most CHF 36,288.
- New: 3a gaps from 2025 can be made up in 2026 and deducted on the 2026 return, on top of the ordinary contribution.
- A pillar 2 or pillar 3a lump sum is taxed separately: for cantonal and municipal tax, at the rate of one quarter of the scale.
Where to enter it: back of annex 2, item 6.1
The back of annex 2 has a table « Prévoyance professionnelle (2ème pilier) et prévoyance individuelle liée (3ème pilier A) » (occupational pension and tied personal pension), with one line per spouse for each pillar. The total is carried to item 6.1 of the return. Do not enter ordinary pension fund contributions already deducted from your salary on the certificate: only buy-ins and contributions you paid yourself go there. Attach the official certificates from the pension fund and the bank or insurer.
Pillar 3a
| Situation | Maximum deduction 2026 |
|---|---|
| Member of a pension fund (pillar 2) | CHF 7,258 |
| Without pillar 2 (self-employed, for example) | 20% of earned income, at most CHF 36,288 |
The deduction requires earned income subject to AHV. For an employee, the reference income is gross salary after AHV/disability/APG/unemployment contributions; for the self-employed, the result of their business. During a temporary interruption (military service, unemployment, illness, accident), the right remains if you receive replacement income. Each working spouse has their own cap. Only payments made by 31 December 2026 into a recognised 3a account or policy count.
Pension fund buy-ins
Buy-ins of contribution years into pillar 2 are deductible, within the limits of federal occupational pension law. Attach the buy-in certificate and, the first time, the buy-in potential calculated by the fund. Note: under the federal occupational pensions act, a lump sum withdrawn within three years of a buy-in cannot come from that buy-in; otherwise the deduction is generally refused. Self-employed people insured personally with a pension foundation deduct half of their contributions in the business income statement and carry the rest to annex 2 (« NOTICE 3 »).
Lump-sum benefits: taxed separately
| Tax | Calculation |
|---|---|
| Cantonal and municipal tax | Full annual tax, at the rate corresponding to one quarter (1/4) of the scale; married couple: lump sums added together, rate calculated on 52% of the total |
| Direct federal tax | Full annual tax, at the rate corresponding to one fifth (1/5) of the scale |
Lump sums from a pension fund, pillar 3a, military insurance or an insurer in case of death or disability are taxed separately from other income. All lump sums received during the year are added together. The institution normally reports them to the tax service itself, but also list them in question 3 of the additional information, with the certificates. A lump sum is not entered as a pension. The child tax rebate does not apply to this tax. To estimate it, the tax service's online calculator has a « Prestation en capital » (lump sum) option.
Pillar 2 and pillar 3a assets are not taxed as wealth until they are paid out. Next, move on to accounts and securities.
Frequently asked questions
How much can I deduct for pillar 3a in 2026 in the canton of Neuchâtel?
At most CHF 7,258 if you belong to a pension fund. Without pillar 2, 20% of earned income, at most CHF 36,288. The amounts are the same for federal tax.
Where do I declare a pension fund buy-in in Clic&Tax?
On the back of annex 2, in the occupational pension table, carried to item 6.1. Attach the buy-in certificate and, the first time, the fund's calculation of your buy-in potential.
Can I deduct a pillar 3a catch-up payment on the 2026 return?
Yes, to fill a gap from 2025, provided you paid the maximum 2026 contribution. Catch-up payments are capped at CHF 7,258 a year. Years before 2025 cannot be bought back.
How is a pillar 2 lump sum taxed in Neuchâtel?
Separately from other income. For cantonal and municipal tax, at a quarter of the ordinary scale rate; for federal tax, at a fifth of the scale rate. For a couple, the lump sums are added together and the rate is calculated on 52% of the total.
Rather hand it over?
NeoFidu prepares and files your Neuchâtel tax return for you, including property, securities and subsequent ordinary assessment (TOU) cases, with a check for missed deductions. Service in English available.
This guide is for information only and is not personalised advice. Amounts come from the 2025 general instructions (« Instructions générales ») of the Neuchâtel cantonal tax service (Service des contributions), the overview of deductions for 2026 published in its 2026 interim instructions, its leaflets (« notices ») and the Swiss Federal Tax Administration's Neuchâtel cantonal sheet (February 2026). Clic&Tax is not available in English: we quote the French labels, followed by a translation, so you can find them on screen. If in doubt, the tax service's general instructions prevail.